
What should a deed of estate distribution include? Checklist 2026

The Swedish Inheritance Code requires that the estate distribution (arvskifte) be drawn up in writing and signed by the estate beneficiaries. The law does not provide a single exhaustive standard template, but a practically functional estate distribution document should clearly show who is partitioning the estate and exactly how the assets are distributed.
Checklist: information that should be included
- The deceased: name, personal identity number, and date of death.
- Estate beneficiaries: names and identifying information.
- Reference to the registered estate inventory and any will.
- Assets to be distributed: for example, bank funds, securities, real estate, and movable property.
- Agreed values and valuation date where necessary.
- The distribution: who receives which asset and any cash adjustments (skifteslikvid).
- Handling of advancements of inheritance, bequests, or waivers when relevant.
- Signatures from all beneficiaries participating in the distribution.
Do witnesses need to sign?
The Inheritance Code's rule on estate distribution does not generally require two witnesses for the distribution document itself to be valid. Other legal acts performed in connection with the distribution may, however, have their own formal requirements.
Must the values be the same as in the estate inventory?
No. If the beneficiaries agree, they can use different values for the distribution. It is still wise to document which values were used and why, especially for real estate, businesses, or other assets whose value may have changed.
Does the document need to be registered?
No, it is normally not sent to the Swedish Tax Agency (Skatteverket). It should, however, be saved and used as documentation when the assets are transferred.
Check debts, disbursements, and final balance before distribution
When an inheritance is paid out in several stages, a written reconciliation of the first partial distribution against the final distribution is important. See the guide on partial estate distribution and how partial payments are documented.
An estate distribution document should not merely reflect the assets at the time of death. Before you decide on the distribution, you also need to check the estate's current assets, known debts, and any costs that any beneficiary has paid on behalf of the estate. According to Chapter 23, Section 2 of the Inheritance Code, an estate distribution cannot be carried out against the objection of a beneficiary until the conditions of the provision are met, including those regarding known debts. Rules regarding the reversal of a premature distribution can also be found in Chapter 21, Section 4.
- Retrieve the current account statement and check for any interest entries, tax refunds, and payments made after the date of the estate inventory.
- Reconcile which debts and costs have been paid and whether money needs to be set aside for remaining obligations.
- Document and substantiate any disbursements a beneficiary has made for the estate. Distinguish compensation for disbursements from the beneficiary's share of the inheritance.
- Calculate and document the amounts or assets that are actually to be distributed according to the applicable order of inheritance, marital property division, will, and agreement.
Practical example: balance and disbursements before estate distribution
Simplified calculation example, not a real estate: The estate inventory states 120,000 SEK in bank funds. When the estate distribution is prepared, there is 125,000 SEK in the account. Known and accepted debts as well as reimbursable estate expenses totaling 25,000 SEK are paid or handled according to current rules. If no other assets, costs, or rights affect the distribution, 100,000 SEK remains. If two beneficiaries, according to the actual inheritance conditions, are to receive half each, that results in 50,000 SEK per person.
The difference between the amount in the estate inventory and the final balance must be traceable in the supporting documentation. It is recommended to attach a separate balance and reconciliation statement with dates, transactions, disbursements, any reservations, and the final distribution. The amounts in the signed document must match the distribution that the beneficiaries actually decide upon.
Estate inventory, final accounting, and estate distribution – three different documents
When property has not yet been distributed, the estate may continue to be managed under special rules. See the guide on undivided estates and how a management agreement can be terminated.
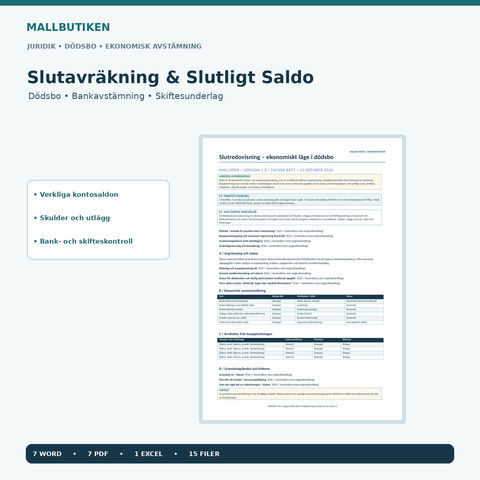
The documents serve different functions. The estate inventory describes, among other things, the beneficiaries and the assets and debts at the time of death. A final accounting (slutavräkning) is a practical working document showing what is actually left before payment. The estate distribution document records the distribution agreed upon by the beneficiaries. The latter two are not the same document.
| Document | Main purpose | What should you check? |
|---|---|---|
| Estate inventory (Bouppteckning) | List the estate's circumstances at the time of death and who represents the estate. | That the estate inventory has been correctly drawn up and registered with the Swedish Tax Agency for cases where a registered inventory is needed. |
| Final accounting (Slutavräkning) | Reconcile current balances, transactions, acceptable disbursements, and debts before distribution. | That the documentation can be traced to account statements, receipts, and actual payments. |
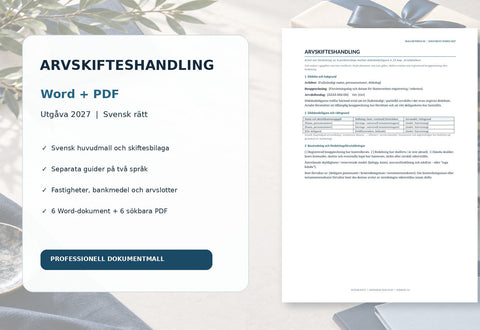
| Estate distribution document (Arvskifteshandling) | Show what the estate beneficiaries have agreed that each person should receive. | That all relevant beneficiaries sign and that the distribution matches the estate's current conditions. |
Does the estate need to document the difference between the estate inventory's balances and the funds available for payment? See the template package for final accounting and final balance in an estate (Word/PDF/Excel). It complements, but does not replace, the estate distribution document.
Legal basis: Inheritance Code Chapters 20 and 23. For practical handling of the estate inventory, see the Swedish Tax Agency's FAQ on estate inventories.
Which documents may be needed at the bank?
Check the bank's own instructions before requesting any payment. The bank may need the registered estate inventory, the signed estate distribution document, and information about who represents the estate. Authorization and power-of-attorney requirements may vary. Also read our guide on estate inventories and deadlines. In the event of a dispute, unclear debts, complicated assets, or disagreement about the distribution, individual legal help may be needed.
Also read how the entire estate distribution process works and whether the estate distribution document is a public record.
Ready-made structure for the estate distribution
A tenant-owned apartment (bostadsrätt) has specific membership rules and should not be treated as a real property with a title deed (lagfart). See the guide on tenant-owned apartments in estates and the distribution document.
A real property (fastighet) in the estate requires, among other things, the complete property designation and correct shares in the distribution document. See our checklist for estate distribution involving real property, buyouts, and title deeds for the specific requirements.
Template in Word/PDF to document beneficiaries, assets, distribution, and signatures.
See Estate Distribution Template – 49 SEKSources
Templates in this article
Explore the topic
 Estate distribution & estate inventory – guides & templates
Partial distribution of estate 2026 – partial distribution, partial payment and debts
Partial estate distribution 2026: when can a partial division and partial payment be made? Guide to debts, reversal according to the Inheritance Co...
 Estate distribution & estate inventory – guides & templates
Undistributed estate 2026 – agreements, joint administration and termination
Undistributed estate 2026: joint administration pursuant to Chapter 18 of the Swedish Inheritance Code, agreements pursuant to Chapter 24, power of...
 Estate distribution & estate inventory – guides & templates
Estate inventory 2026 – deadlines, summons and new regulations
Complete guide to estate inventory 2026: three-month procedure, filing, summons, assets and liabilities, and the amendments effective July 1, 2026.


