
Contingency balance sheet – implementation, questions and answers

A "kontrollbalansräkning" (statutory balance sheet for liquidation purposes) is not a voluntary internal quality check of the bookkeeping. It is a specific balance sheet that the board of directors of a limited company must act upon when any of the situations in Chapter 25, Section 13 of the Swedish Companies Act is met. Here is a practical walkthrough of the process and answers to the most common questions.
When must a statutory balance sheet be prepared?
The obligation lies with the board of directors. The threshold is not that it has been definitively established that the capital is depleted. It is sufficient that there is reason to assume that the company's equity, calculated according to the rules for a statutory balance sheet, is less than half of the registered share capital.
The second statutory situation is that enforcement under Chapter 4 of the Enforcement Code has shown that the company lacks assets for full payment of the distrained debt.
Also read our in-depth article: When is a statutory balance sheet required? Rules and examples.
How does the process work?
- Identify the warning signal. The board monitors the company's financial position and assesses whether Chapter 25, Section 13 of the Swedish Companies Act has been triggered.
- Prepare the statutory balance sheet immediately. It must be based on applicable Annual Accounts Act legislation but may include the specific adjustments permitted by Chapter 25, Section 14 of the Swedish Companies Act.
- Have the company's auditor review it, if the company has an auditor.
- Assess the result. If the statutory balance sheet shows that equity is less than half of the registered share capital, the board must convene the first general meeting for control purposes as soon as possible.
- First general meeting for control purposes. The meeting decides whether the company should go into liquidation.
- Possible reflection period. If business continues, a second general meeting for control purposes may need to be held within eight months from the first one.
- Restore the entire share capital. At the second general meeting, the goal is not just to reach above half of the share capital. The new statutory balance sheet must show that equity amounts to at least the full registered share capital for the obligation to liquidate to cease on that basis.
For a step-by-step guide, see How is a statutory balance sheet prepared?.
Must an auditor review the statutory balance sheet?
The Swedish Companies Act states that the board shall have the company's auditor review the statutory balance sheet. If the company has an elected auditor, the auditor must therefore be involved in accordance with the rules. A private limited company that legally lacks an auditor naturally has no company auditor to conduct the review. It is therefore important to distinguish between companies with and without an auditor in the practical process.
The auditor's role is not to "approve" the business decision regarding whether the company should continue. The auditor reviews the statutory balance sheet and issues an opinion; the decision on continued operations or liquidation is handled according to the rules of the Swedish Companies Act.
When are the first and second general meetings for control purposes needed?
If the first statutory balance sheet shows that equity is less than half of the registered share capital, the board must convene the first general meeting for control purposes as soon as possible.
If the statutory balance sheet presented there does not show that the equity at the time of the meeting amounts to at least the full registered share capital and the meeting does not decide on liquidation, the matter must normally be re-examined at a second general meeting for control purposes within eight months from the first general meeting for control purposes. This is an important distinction compared to the common but incorrect phrasing that the eight-month period is calculated from the first statutory balance sheet.
When can personal payment liability arise?
According to Chapter 25, Section 18 of the Swedish Companies Act, board members can become jointly and severally liable for the company's obligations if the board neglects certain actions, such as preparing a statutory balance sheet, convening the first general meeting for control purposes, or applying for liquidation when required by law.
Frequently asked questions
Is a statutory balance sheet the same as an ordinary balance sheet?
No. It is based on the accounts but has a specific purpose according to the Swedish Companies Act and allows for certain specific valuation adjustments. Read how items may be valued in a statutory balance sheet.
Must the statutory balance sheet be sent to the Swedish Companies Registration Office?
The statutory balance sheet is not an annual report that is routinely sent to the Swedish Companies Registration Office (Bolagsverket). However, it is central to the statutory capital shortfall process and may be significant in later legal proceedings. Documentation should therefore be traceable and well-substantiated.
Can a shareholder contribution restore the capital?
A correctly executed capital contribution can affect the company's equity, but how a contribution is structured, accounted for, and potentially conditioned must be assessed separately. The capital shortfall process does not end just because money is deposited; the company's position must be proven according to the rules.
How are valuation adjustments documented?
Adjustments according to Chapter 25, Section 14 of the Swedish Companies Act must be reported separately. See our guide on supporting documents, notes, and appendices.
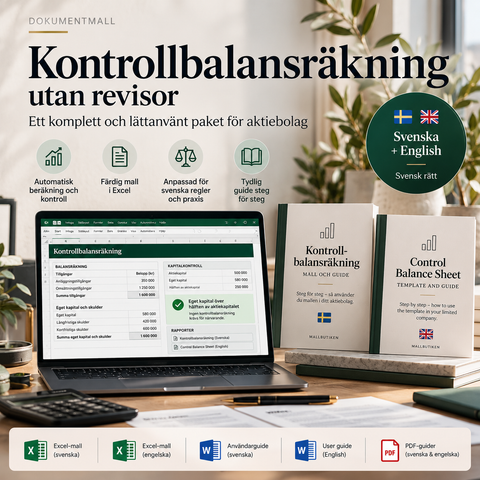
For limited companies lacking an auditor, Mallbutiken offers the Statutory Balance Sheet Template – Without Auditor (Excel). The template costs SEK 49. Always ensure it is adapted to the company's actual circumstances and current accounting regulations.
Does this also apply to a housing cooperative?
No, not the same statutory balance sheet procedure. This guide describes the rules in Chapter 25 of the Swedish Companies Act for limited companies. A housing cooperative is an economic association and does not have the share capital upon which the half-threshold of the statutory balance sheet rules is based.
Choose the right type of working document:
- Limited company without an elected auditor: statutory balance sheet in Excel without an auditor.
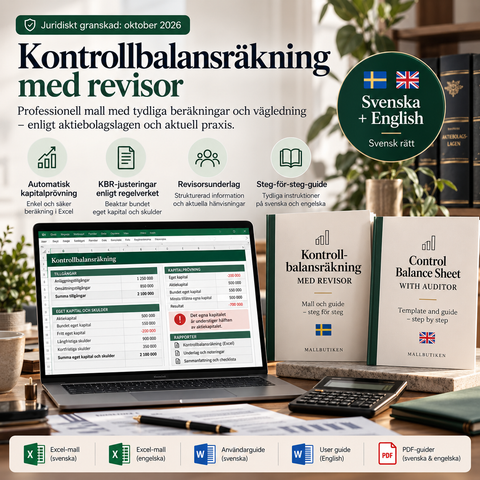
- Limited company with an elected auditor: statutory balance sheet in Excel with auditor documentation.
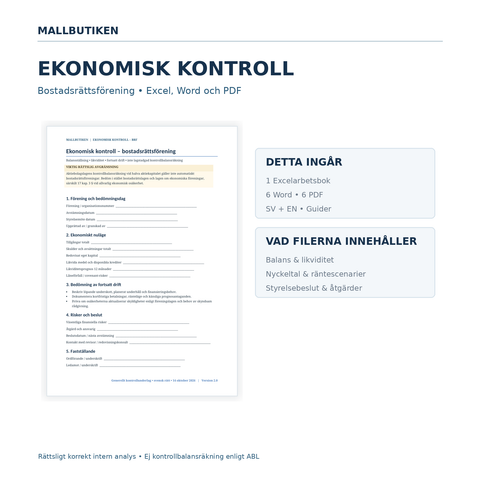
- Housing cooperative: financial control for housing cooperatives regarding liquidity, risks, and board documentation – not a formal statutory balance sheet under the Swedish Companies Act.
The board's responsibility in an association needs to be assessed according to the rules applicable to that association form. The documents are not interchangeable.
Sources and further reading
Templates in this article
Explore the topic
 Control balance sheet – guides & guidance
When is a balance sheet for liquidation purposes required? Rules and examples
When is a balance sheet for liquidation purposes required? A guide to the two statutory situations in Chapter 25, Section 13 of the Swedish Compani...
 Control balance sheet – guides & guidance
How is a control balance sheet prepared? Step by step
Step-by-step guide to the balance sheet for liquidation purposes: from capital deficiency and BSL to the first special general meeting, eight-month...
 Control balance sheet – guides & guidance
Control balance sheet – valuation of assets and liabilities
How assets, liabilities, receivables, and untaxed reserves are valued in a control balance sheet according to Chapter 25, Section 14 of the Swedish...

