
Which promissory note should I choose? Checklist for private loans and businesses
Checklist for choosing between simple and promissory notes based on parties, need for transfer, repayment, interest, security, and area of use.

The choice should primarily be between a simple and a negotiable promissory note – not between arbitrary categories based on what the loan will be used for. Start with who is to receive payment and whether the claim actually needs to be structured for circulation.
- Is the creditor a specific person? For private loans between friends, relatives, or cohabitants, a simple promissory note is often natural.
- Does the document need to be negotiable? If it is to be transferable with the specific legal effects of a negotiable promissory note, a bearer or order note may be relevant.
- Are the parties a consumer and a business? In that case, the Consumer Credit Act and other mandatory rules may become important in addition to the Promissory Notes Act.
- Is there collateral? Pledges or other security are regulated separately. The fact that a loan has security does not in itself create a specific type of promissory note.
- How is the loan to be repaid? Specify a due date or amortization schedule and how extra payments are handled.
- Is interest to be charged? Specify the interest rate, basis for calculation, and when the interest is paid. Distinguish between ordinary interest and default interest.
- What happens in the event of default? Regulate consequences clearly and check the rules of the Interest Act.
- Can the creditor be changed? Understand the differences in the debtor's right of objection before choosing a negotiable form.
- How are payments documented? Provide receipts for partial payments and final payment.
- How is limitation handled? A document lying in a drawer does not prevent the claim from becoming statute-barred.
What happens if the borrower stops paying?
First check what is actually due, which partial payments have been made, and whether interest has been agreed upon. The promissory note should distinguish standard loan interest from default interest. Save account statements and payment confirmations, and check the limitation period and any interruptions; a signed promissory note does not stop the limitation period on its own.
If a monetary claim has fallen due, the creditor can in some cases apply for a summary application for a writ of payment (betalningsföreläggande) with the Swedish Enforcement Authority (Kronofogden). Such a procedure does not automatically mean that a disputed claim is materially correct. Read the Swedish Enforcement Authority's guidance, questions and answers about interest and payment, as well as the guide on limitation.
Quick choice
- Private loan to a named person: normally a simple promissory note.
- Loan between cohabitants: often a simple promissory note; assess separately if a cohabitation agreement is needed.
- Claim document intended to circulate: consider a negotiable promissory note.
- Loan with pledge: choose the type of promissory note based on the payment relationship and document the security separately.
Decision support: simple or negotiable promissory note?
| Situation | What should you consider? |
|---|---|
| Loan between two private individuals with a named lender | Simple promissory note is often a suitable starting point: the claim is issued to a specific person. |
| Business loan with the same identified creditor during the contract period | Here too, a simple promissory note may be relevant. Review security, interest, due date, and any mandatory rules separately. |
| Claim intended to be able to circulate as an order or bearer note | Negotiable promissory note may be suitable but entails specific transfer and objection rules. Do not choose this form just because it seems more flexible. |
Legal basis: Section 11 of the Promissory Notes Act defines negotiable promissory notes; Section 26 defines a simple promissory note, and Section 27 regulates objections upon the transfer of a simple promissory note. A simple promissory note can also be transferred, but with different legal effects.
For details on the legal effects, read simple or negotiable promissory note – the differences, and for practical terms, promissory note FAQ on interest and repayment.
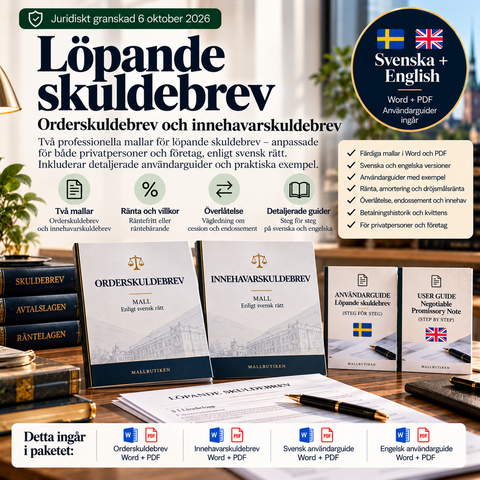
Promissory note templates
Simple promissory note: 29 SEK. Negotiable promissory note: 49 SEK.
Simple NegotiableTemplates in this article

Explore the topic
 Promissory notes – guides, rules & templates
Frequently asked questions about promissory notes – interest, transfer, and statute of limitations
Current answers regarding promissory notes: simple or negotiable, signature, witnesses, interest, payment, transfer, and prescription according to ...
 Promissory notes – guides, rules & templates
When do debts become time-barred? 10 years, 3 years, and interruption of the limitation period
Guide to the statute of limitations for claims: the main rule is 10 years, consumer claims are 3 years, exceptions for promissory notes, and how th...
 Promissory notes – guides, rules & templates
Simple or negotiable promissory note – what is the difference?
Compare the two main categories of the Promissory Notes Act: simple promissory notes and negotiable bearer and order promissory notes. See how tran...


