
Why use a promissory note for a private loan? 8 reasons and key terms
Why a promissory note is valuable for private loans: evidence, repayment, interest, installments, late payments, statute of limitations, and clarity between the parties.

A private loan can be binding even without a comprehensive promissory note, but a clear written promise to pay makes it significantly easier to prove what was actually agreed upon. The most important value, therefore, is not an alleged "formal validity" but clarity and evidence.
- The amount becomes clear. Document exactly how much is being lent and when the disbursement takes place.
- The due date can be established. Specify a single payment or an amortization schedule and what happens if an installment is missed.
- Interest can be regulated. State whether the loan is interest-free or interest-bearing, and distinguish between standard interest and penalty interest.
- Installments can be tracked. Determine how payments should be acknowledged and how the remaining debt is calculated.
- Both parties get the same picture. It reduces the risk of a gift later being claimed as a loan, or vice versa.
- The issue of assignment becomes understandable. A simple promissory note is made out to a specific creditor and functions differently than a negotiable promissory note.
- Statute of limitations can be managed. A promissory note does not stop the statute of limitations by itself. The creditor must understand the rules of the Limitations Act and document any interruptions of the statute of limitations.
- Disputes become easier to resolve. Dates, amounts, payment plans, and terms are all collected in the same document.
What should a simple promissory note contain?
For a standard private loan, it is often appropriate to include the identity of the parties, the debt amount, the date, payment terms, any interest, default terms, and how early repayment or changes should be handled. The debtor's signature is central as evidence of the promise to pay.
Promissory notes between cohabiting partners
If cohabitants finance a home differently, a promissory note can sometimes be combined with a cohabitation agreement, but the documents serve different functions. A promissory note regulates a claim. A cohabitation agreement regulates whether certain cohabitation property should be excluded from the rules on division of property. One document therefore does not automatically replace the other.
Interest and default
If the parties want agreed-upon interest, it should be stated clearly. The Interest Act serves as supplementary legislation. If penalty interest is to be calculated according to Section 6 of the Interest Act, it corresponds to the reference rate plus eight percentage points at any given time.
When is a negotiable promissory note relevant?
For a standard family or personal loan, a simple promissory note is often natural because the creditor is identified. A negotiable promissory note is designed for easier circulation and entails different rules regarding objections, possession, and payment. Do not choose it just because the word "negotiable" sounds flexible.
Repayment terms for a private loan
Document the amount, payment, creditor, any interest and the agreed final or on-demand repayment date. A loan without instalments still has to be repaid. In the absence of an agreed due date, Section 5 of the Promissory Notes Act generally applies.
Compare the Swedish simple promissory note and the English-language private loan note. An ordinary simple promissory note is distinct from an order/bearer note; see the comparison of simple and negotiable promissory notes.
For the 2026 income year, interest on loans without qualifying security is normally not tax-deductible; check the Swedish Tax Agency's current rules.
Private loan without regular instalments? If the parties agree to repay the principal on a specified final date, see the template for a promissory note without ongoing amortisation. Clearly specify the payment terms. The template is not intended for professional consumer lending. View the template
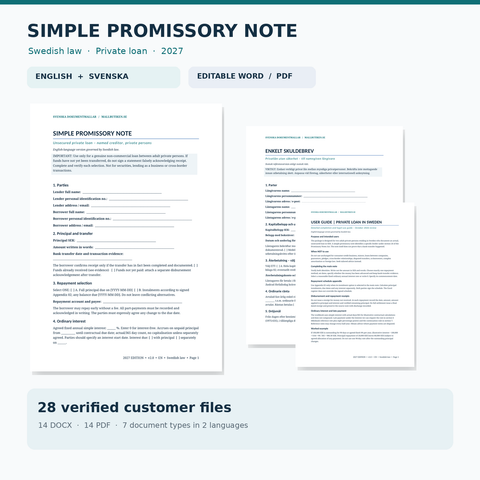
Simple Promissory Note Template
Editable Word/PDF for private loans. Price in store: 29 SEK.
See the promissory note templateIn-depth information
Simple vs. negotiable promissory notes · When can a claim or document be challenged?
Sources
Templates in this article

Explore the topic
 Promissory notes – guides, rules & templates
Simple or negotiable promissory note – what is the difference?
Compare the two main categories of the Promissory Notes Act: simple promissory notes and negotiable bearer and order promissory notes. See how tran...
 Promissory notes – guides, rules & templates
When can a promissory note or a claim be invalid or unenforceable?
The difference between invalidity, objections, statute of limitations, and evidentiary issues regarding promissory notes – and which common misconc...


