Svenska Dokumentmallar
Gift Deed Money Template 2027 – Word/PDF + English reference + guide
Gift Deed Money Template 2027 – Word/PDF + English reference + guide
- File format
- DOCX, PDF
- Document language
- Swedish + English
- Number of files
- 8
Digital download. No physical product is shipped.
Couldn't load pickup availability
About this template
Deed of Gift for money – Swedish template in Word and PDF, updated 2027. Document a monetary gift between private individuals with clear information regarding the donor, recipient, amount, bank transfer, terms and conditions, advance on inheritance, and any separate property. The package includes a main Swedish template, Swedish user guide, English reference version, and English guide – all in DOCX and PDF.
Legal framework verified October 8, 2026.
The template pertains to a genuine gift of money without consideration, either already completed or intended to be completed in connection with the documentation. It is not a template for salary, loans, purchases, a purely future promise of a gift, or tax planning. A signed Deed of Gift does not automatically imply that a monetary gift has been completed.
Money gift deed PDF and editable Word template
Price SEK 29. The digital ZIP gavobrev-pengar-2027.zip is attached to this product in Shopify. The product description lists eight Word/PDF files, including a Swedish main document, Swedish guide and English reference documents. File attachment is verified; ZIP contents have not been independently examined.
Use Word to adapt the details and PDF for reading or printing. Review advance-on-inheritance and separate-property clauses before signing.
What is included in the 2027 package
| Swedish Deed of Gift for money – DOCX + PDF | 13 sections, choices for advance on inheritance and separate property, signatures, receipt of payment, and control appendix. |
| Swedish User Guide – DOCX + PDF | 11 guidance sections on completion, inheritance law, tax, gifts between spouses, and minors. |
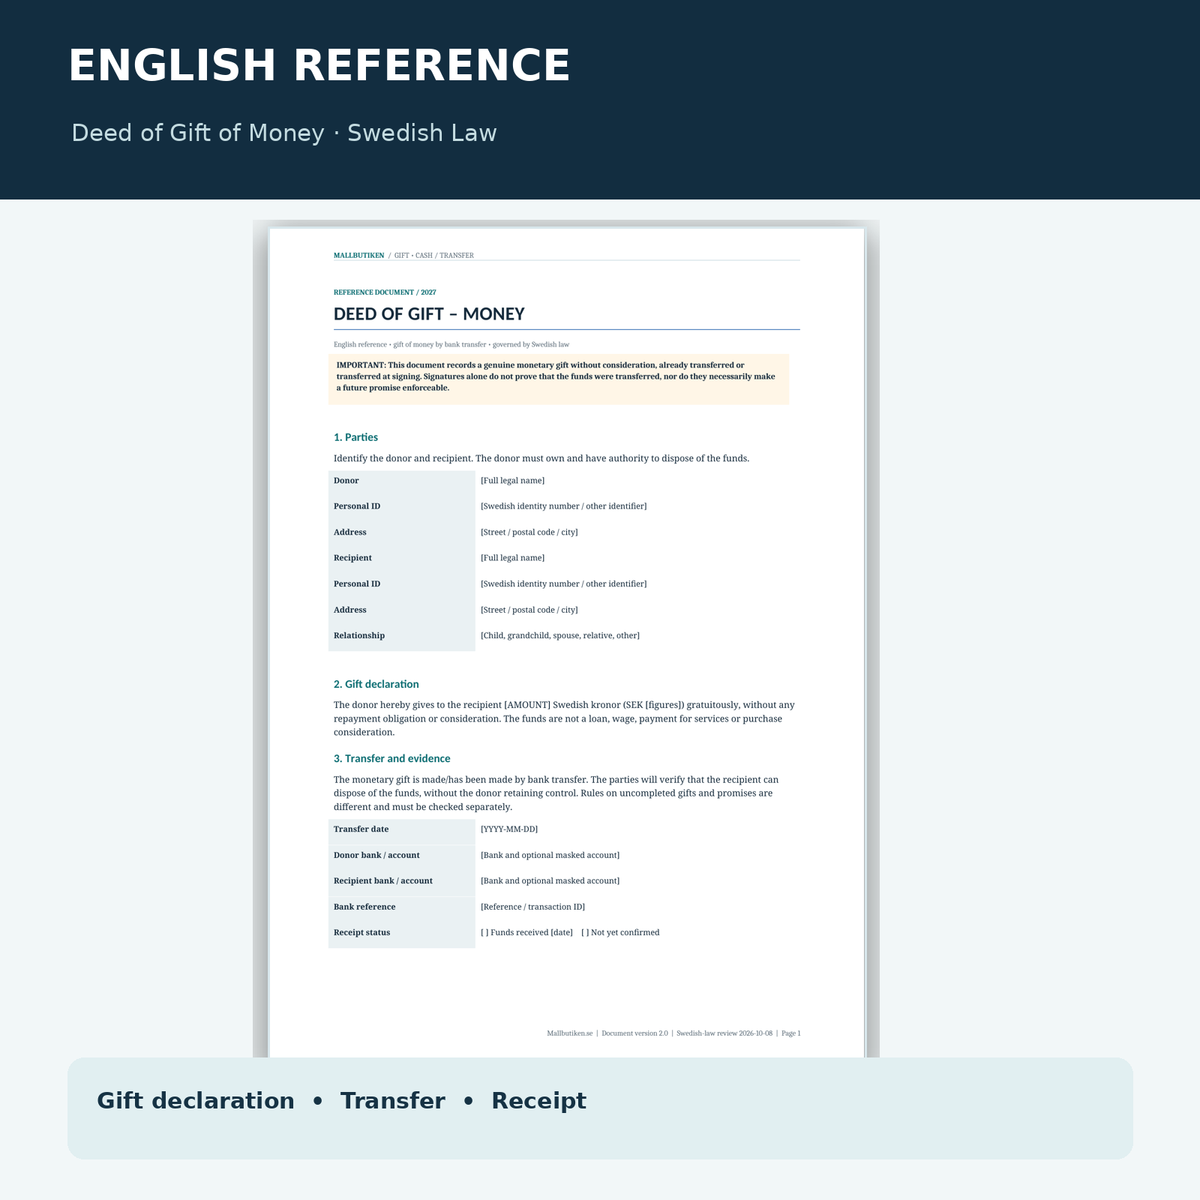
| Deed of Gift – Money, English reference – DOCX + PDF | English reference of the corresponding monetary gift under Swedish law. |
| English User Guide – DOCX + PDF | English instructions and explanations of Swedish regulations. |
Total of 8 files. Editable Word documents and searchable A4 PDFs. Digital ZIP delivery for the new edition.
When is a Deed of Gift for money needed?
For a standard monetary gift, there is no general legal requirement for a written Deed of Gift. However, a document can have significant evidentiary value, especially when money is given to children, grandchildren, a married recipient, or when the donor wishes to establish what should apply during a future inheritance.
A Deed of Gift can help show who gave the money, to whom, how much, and on what terms. The document is particularly useful in conjunction with separate supporting documentation from the bank.
Completed gift vs. promise of a gift – two different issues
Do not write that the gift has been received before the money has actually been transferred.
The Act (1936:83) on Certain Promises of a Gift contains specific rules regarding both promises and completion. According to Section 4, a gift via bank can be completed when the bank has received the money on behalf of the donee, without the donor having reserved the right of disposal. A signed document alone is not always sufficient.
The main template therefore contains separate fields for transfer date, bank reference, and receipt status, as well as a specific receipt of payment to be filled out after the transfer has been verified. Full bank account numbers do not need to be disseminated in the document; masked information and a separate bank receipt may be more appropriate.
Monetary gift to children – is it an advance on inheritance?
Accounting for advances and restitution of gifts resembling testaments are different rules. Read the guide on gifts that may infringe upon the statutory share (laglott).
If a child has already received money before death, the accounting may affect the later estate distribution. See calculation of advance on inheritance in estate distribution with two or three children.
According to Chapter 6, Section 1 of the Inheritance Code, what a parent gives to a descendant (bröstarvinge) shall, as a starting point, be accounted for as an advance on inheritance, unless the donor has stipulated otherwise or circumstances show otherwise. The rules are different for other heirs.
The new template allows the donor to actively choose whether the gift should or should not be an advance on inheritance. It is particularly important not to leave conflicting options remaining. Customary gifts of proportional value and gifts that can be equated to testamentary dispositions may require further assessment.
If you wish to specifically regulate such situations, there is also the Mallbutiken's separate template package for advance on inheritance.
Separate property – when can the condition be used?
Anyone giving money to someone other than their own spouse can normally specify that the gift shall be the donee's separate property pursuant to Chapter 7, Section 2 of the Marriage Code. This can be relevant, for example, when parents want to give money to a married child.
Separate property can include money that later replaces the gift. It is important to also decide whether returns (yields) should be covered by the condition. The main template therefore includes separate choices for separate property, replacement property, and returns.
Important: this third-party rule cannot automatically be used for gifts between spouses. Such family law conditions may require a separate, correct prenuptial agreement.
Gift between spouses – special registration rules
Spouses may give each other money, but according to Chapter 8, Section 2 of the Marriage Code, a promise of a future gift during marriage is ineffective. A completed gift, however, can be valid between spouses.
For a gift between spouses to receive protection against the donor's creditors, registration with the Swedish Tax Agency (Skatteverket) is normally required. There is an exception for certain personal gifts whose value is reasonable in relation to the donor's finances. See the Swedish Tax Agency's rules for gifts between spouses.
The Swedish Tax Agency registers gift documents between spouses – not standard Deeds of Gift between parents and children, friends, or cohabitants.
Giving money to children under 18
When giving a gift to a minor, you must check who represents the child, how the bank account is set up, and whether any special guardianship control needs to be applied. According to Chapter 13 of the Parental Code, there are rules regarding management and special guardianship control for, among other things, larger assets or specifically conditioned gifts.
The money must be treated as the child's asset, not as the parent's own money. Large, complicated, or conditioned gifts should be checked with the bank and the chief guardian before the transfer.
Is a monetary gift tax-free?
A genuine private gift without consideration is normally tax-free for the donee according to Chapter 8, Section 2 of the Income Tax Act. Sweden has no separate gift tax.
A payment that in reality constitutes salary, compensation for work, a sale, or other consideration is not automatically tax-free because the document is called a "Deed of Gift." Gifts from employers are assessed according to special rules, and cash payments are normally not tax-free employer gifts.
What does the Deed of Gift itself contain?
- Identification of donor and donee.
- Gift amount and clear declaration of transfer.
- Bank transfer, bank reference, and receipt status.
- Purpose of the gift and right to dispose of the money.
- Advance on inheritance – selectable, clearly defined options.
- Separate property and any return conditions.
- Any special, legally permissible conditions.
- Check if donor and recipient are spouses.
- Check for minor donee.
- Confirmation that the gift lacks consideration.
- Signatures and location/date.
- Receipt of payment after completed bank transfer.
- Voluntary witnessing and separate checklist.
How to use the new Word template
- Check that it really is a monetary gift – not a loan or payment for something.
- Open the Swedish Word file and fill in names, amount, date, and relevant information.
- Select a clear option for advance on inheritance.
- Decide if the condition regarding separate property is relevant and legally applicable.
- Check special rules regarding spouses or minors.
- Remove unused options and replace all placeholders within brackets.
- Execute and document the bank transfer.
- Fill in the receipt of payment only after the money has actually been received.
- Save the signed document and bank receipt in a secure manner.
Common questions about Deeds of Gift for money
Must a Deed of Gift for money be written?
No, not generally. However, a written Deed of Gift is often valuable for documenting larger gifts and terms. Special rules apply to promises and gifts between spouses.
Is it enough to sign the Deed of Gift?
Not always. One must distinguish the legal effect of a gift promise from when a gift has been completed. Therefore, also document the bank transfer itself.
Does the Deed of Gift need to be witnessed?
There is no general requirement for two witnesses for a standard monetary gift. Voluntary witnessing can be used as extra evidence.
Must the Deed of Gift be registered with the Swedish Tax Agency?
Standard monetary gifts between parents and children or other private individuals are not registered there. For gifts between spouses, however, there are special registration rules.
Can I give money to my child without it becoming an advance on inheritance?
Yes, the donor can normally stipulate that the gift shall not be accounted for as an advance. It is important to document the intention clearly and at the same time understand that other inheritance law limitations may be triggered.
Can the money be made separate property?
Yes, for example, through a correct gift condition from a parent to a married child. Gifts between spouses must be handled in another way.
Is the gift tax-free even for large amounts?
A genuine private gift without consideration is, as a main rule, tax-free regardless of the fact that the amount may be large. However, the donor and recipient may need to explain the origin of the money to the bank, and special relationships or cross-border situations may affect the assessment.
Is an English version included?
Yes. The package contains an English reference and English user guide, both based on Swedish law.
Related templates
- Deed of Gift for money – English primary product
- Deed of Gift – advance on inheritance
- Deed of Gift for tenant-owned apartment
- Deed of Gift for real estate
Official legal sources
The Act (1936:83) on Certain Promises of a Gift, especially Sections 1–4 and 6.
The Inheritance Code (1958:637), Chapter 6, Sections 1–2 and Chapter 7, Section 4.
The Marriage Code (1987:230), Chapter 7, Section 2 and Chapter 8, Sections 1–2.
The Income Tax Act (1999:1229), Chapter 8, Section 2.
The Parental Code (1949:381), Chapter 13, regarding minors.
Edition 2027. Legal framework verified against official sources October 8, 2026. The template is general documentation support and does not replace individual family law, tax law, or bank-related advice.
Before and after the monetary gift: practical guides
In addition to documenting the gift's amount, donor, recipient, and conditions, it can be valuable to save transfer documentation.
- Five common mistakes with Deeds of Gift for money
- Tax, the bank's supporting questions, and gifts to or from abroad
A Deed of Gift does not automatically mean that the bank approves a transfer or that all tax law issues are resolved.
Read more before a monetary gift to children
A monetary gift can, according to the main rule, become an advance on inheritance if the recipient is a descendant. Read how the gift is deducted from future inheritance and what you should document in a Deed of Gift. The condition of advance is a different issue than whether the gift should be separate property.
Related guides