Svenska Dokumentmallar
Different Down Payments Cohabiting 2026/2027 – Promissory Note + Cohabitation Agreement Word/PDF
Different Down Payments Cohabiting 2026/2027 – Promissory Note + Cohabitation Agreement Word/PDF
 Downloading the template is available immediately after purchase. Our document templates are always delivered in customizable formats.
 If you are unsure which template is appropriate or how you should complete it, please see the relevant information under the 'Legal Information' tab in our main menu.
 Our templates are designed in accordance with current legislation and practice in each area to ensure that the documents you create are legally correct.


Couldn't load pickup availability
Different Down Payments for Cohabiting Partners 2026/2027 – Promissory Note + Cohabitation Agreement Word/PDF
This is a specialized template package for cohabiting partners or those planning to move in together who are purchasing a joint home but contributing different amounts as a down payment or other equity. The package combines a cohabitation agreement with a simple promissory note and a separate calculation appendix, ensuring that both the division of property issue and the financial difference can be clearly documented.
The template package was legally reviewed on October 4, 2026, and developed for use during 2026/2027. It is specifically designed for the common situation where partners, for example, intend to own the home 50/50, but one party pays a larger share of the down payment.
Delivery: 4 documents in both Word (DOCX) and PDF – a total of 8 files and 13 A4 pages. The product is delivered digitally.
Included in this package
- Cohabitation Agreement – different down payments 2026/2027, 3 pages.
- Simple Promissory Note – different down payments 2026/2027, 4 pages.
- Calculation Appendix – different down payments, 3 pages.
- Detailed User Guide, 3 pages.
- All four documents in both Word and PDF.
Why both a promissory note and a cohabitation agreement?
A home purchased for the joint use of cohabiting partners may constitute cohabitation property according to the Cohabitation Act. If the cohabitation ends and one party requests a division of property, the home may be subject to the provisions of the Cohabitation Act even if the partners paid different amounts at the time of purchase.
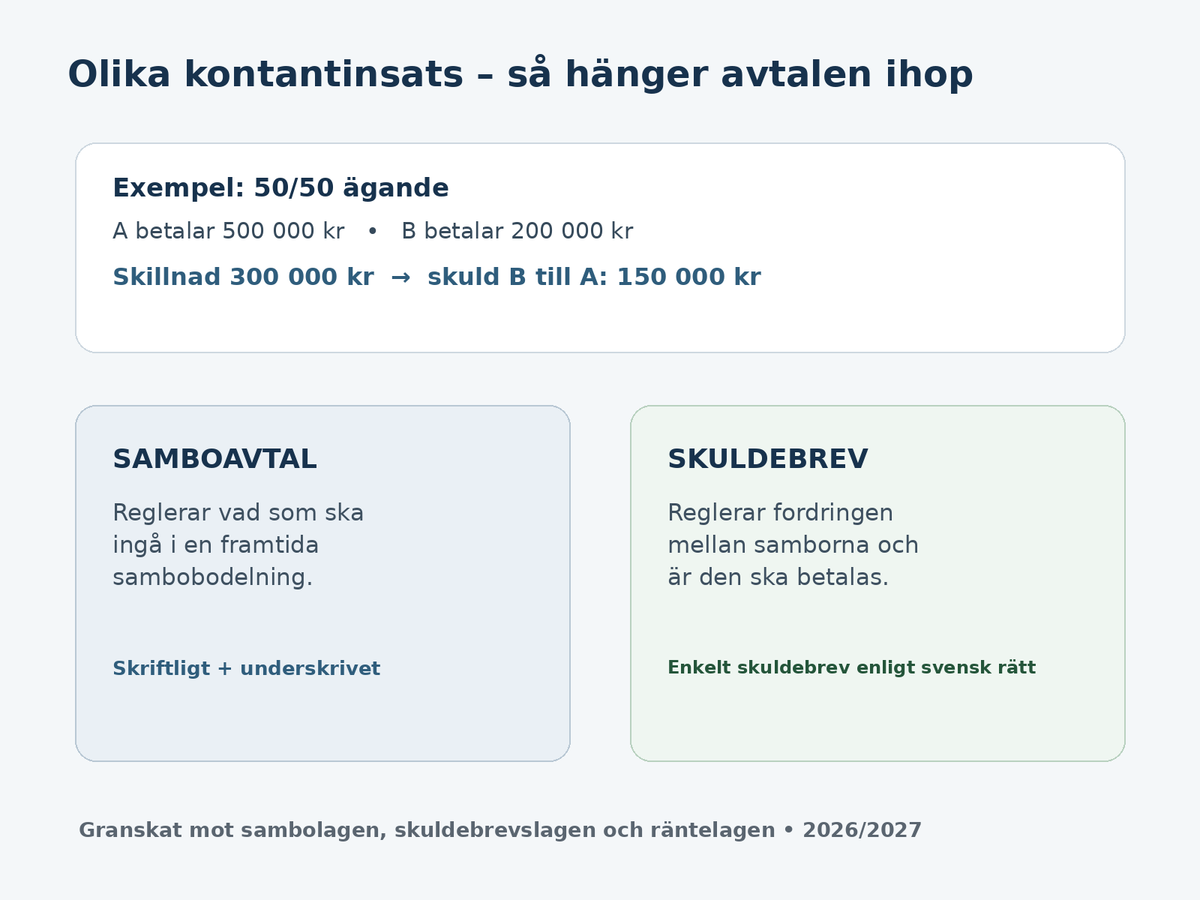
The promissory note documents the actual debt between the partners. The cohabitation agreement simultaneously stipulates that the specified home shall not be included in the division of cohabitation property, if that is the solution chosen by the parties. Thus, the documents fulfill different functions and are designed to be used together.
Example – 50/50 ownership but different down payments
Assume two cohabiting partners are to own 50% of the home each:
- Partner A pays 500,000 SEK as their own contribution.
- Partner B pays 200,000 SEK.
- Total own contribution is 700,000 SEK.
- With 50/50 ownership, each partner's economic share is 350,000 SEK.
- Partner A has therefore financed 150,000 SEK more than their own share.
In this example, the debt is therefore 150,000 SEK from Partner B to Partner A. It is not the entire difference of 300,000 SEK, but the amount required for each party to economically bear their 50-percent share.
Also works with other ownership shares
The package is not limited to 50/50. The calculation appendix also includes a model for, for example, 60/40 or other ownership shares.
With other ownership shares, each party's target contribution is calculated based on the total own contribution and the actual ownership share. The party who has paid more than their target contribution has financed a portion of the other party's economic share.
The Cohabitation Agreement
The cohabitation agreement includes, among other things:
- identification of both partners,
- identification of the property in question,
- co-operative apartment, detached house/property, or other housing type,
- ownership shares,
- a clause to exclude the home in question from the division of cohabitation property,
- a choice between excluding only the home or all cohabitation property,
- a link to the separate promissory note,
- clarification regarding ownership and external bank loans,
- provisions on amendments and validity,
- signature section.
A cohabitation agreement according to Section 9 of the Cohabitation Act must be in writing and signed by both partners. It is not registered with the Swedish Tax Agency or any other authority.
Simple Promissory Note
The promissory note is designed as a simple promissory note to a specific creditor and includes, among other things:
- creditor and debtor,
- the home and ownership shares,
- each party's actual contribution,
- calculated debt amount,
- choice between interest-free debt and agreed interest,
- several clear models for maturity date,
- amortization,
- prepayment,
- penalty interest according to the Interest Act where applicable,
- settlement upon sale of the home,
- handling if ownership shares or capital contributions change later,
- assignment of claim,
- payment history.
Calculation Appendix
A separate calculation appendix helps the parties document exactly how the debt has been calculated. It contains:
- purchase price,
- ownership shares,
- joint mortgage and other financing,
- actual own contribution for each partner,
- target contribution according to ownership share,
- calculated over-contribution,
- final debt amount,
- examples for both 50/50 and 60/40,
- control questions and recommended documentation to save.
The mortgage is a separate issue
The promissory note and the cohabitation agreement regulate the partners' internal relationship. They do not change the bank's rights under the mortgage agreement. If both partners are jointly liable for a loan, the bank can still demand payment according to the loan documents, regardless of the internal distribution between the partners.
Interest and delay
The package makes it possible to choose that the debt shall be interest-free until the maturity date or accrue interest at an agreed rate. In case of late payment, penalty interest can be calculated according to the Interest Act.
The statutory penalty interest under Section 6 of the Interest Act is linked to the current reference rate plus eight percentage points. Therefore, no permanent fixed percentage is stated in the standard clause itself.
When might the agreements need to be updated?
The documents should be reviewed if, for example:
- ownership shares change,
- a partner makes a larger additional capital contribution,
- the partners amortize different amounts and want that difference to affect their internal finances,
- the home is sold and replaced by a new one,
- the debt is paid down or settled,
- the partners get married,
- the parties want to change what is to be included in the division of cohabitation property.
Co-operative apartment and house
The package can be used for both co-operative apartments and real estate/houses. The cohabitation agreement does not, however, change the registered ownership share. The ownership structure must be correctly documented in the purchase/transfer deed and, for real estate, through correct registration of title (lagfart).
Detailed User Guide
The user guide explains step by step:
- why the promissory note and cohabitation agreement fulfill different functions,
- how the debt is calculated at 50/50,
- how it is calculated for other ownership shares,
- how the cohabitation agreement is completed,
- how the promissory note is completed,
- how interest and maturity dates should be documented,
- the difference between internal debt and the bank mortgage,
- when the agreements should be updated,
- common mistakes,
- final checklist before signing.
Common mistakes the package helps to avoid
- Setting the debt to the full difference between contributions despite 50/50 ownership.
- Using the same 50/50 formula even if ownership shares are, for example, 60/40.
- Writing only a promissory note but forgetting how the Cohabitation Act affects the home in a division of property.
- Believing that the cohabitation agreement changes liability for bank mortgages.
- Forgetting future large capital contributions or uneven amortizations.
- Believing that the cohabitation agreement must be registered.
Death and wills
A cohabitation agreement and promissory note do not regulate inheritance rights. Cohabiting partners do not automatically inherit from each other in the same way as spouses. If the goal is also to protect the surviving partner, the need for a will and any insurance solutions should be assessed separately.
Legally reviewed for 2026/2027
The documents were reviewed on October 4, 2026, based on, among other things:
- The Cohabitation Act (2003:376), especially the rules regarding cohabitation property, division of property, and cohabitation agreements.
- The Promissory Notes Act (1936:81), especially the rules regarding simple promissory notes.
- The Interest Act (1975:635).
- The Contracts Act (1915:218), in applicable parts.
Format and delivery
- Word (DOCX) – fully editable documents.
- PDF – print-ready A4 versions.
- 4 documents / 8 files / 13 A4 pages.
- Digital delivery – no physical product is sent.
Frequently Asked Questions
Do we need both a cohabitation agreement and a promissory note?
They fulfill different functions. The promissory note regulates the claim while the cohabitation agreement regulates what is to be included in the division of cohabitation property.
Is the debt always half the difference?
No. That is a practical formula when ownership shares are 50/50 and only the own contribution differs. For other ownership shares, the calculation must be made against each party's target contribution.
Can the package be used for a house?
Yes. It can be used for both real estate/houses and co-operative apartments.
Must the cohabitation agreement be registered?
No. It must be in writing and signed by both partners but is not registered with any authority.
Can the debt be interest-free?
Yes. The template contains a clear option for an interest-free debt until the maturity date.
Does the promissory note change our mortgage?
No. The bank's rights and the parties' payment obligations according to external loan documents are not automatically affected.
Important
The template package is a general professional document framework and must be completed based on the actual financing and actual ownership shares. In cases involving large values, complex loan financing, foreign assets, children from previous relationships, or other specific circumstances, individual legal advice may be needed.