Svenska Dokumentmallar
Gift Deed Housing Cooperative Template 2027 – Word/PDF + English reference + guide
Gift Deed Housing Cooperative Template 2027 – Word/PDF + English reference + guide
- File format
- DOCX, PDF
- Document language
- Swedish + English
- Number of files
- 8
Digital download. No physical product is shipped.
Couldn't load pickup availability
About this template
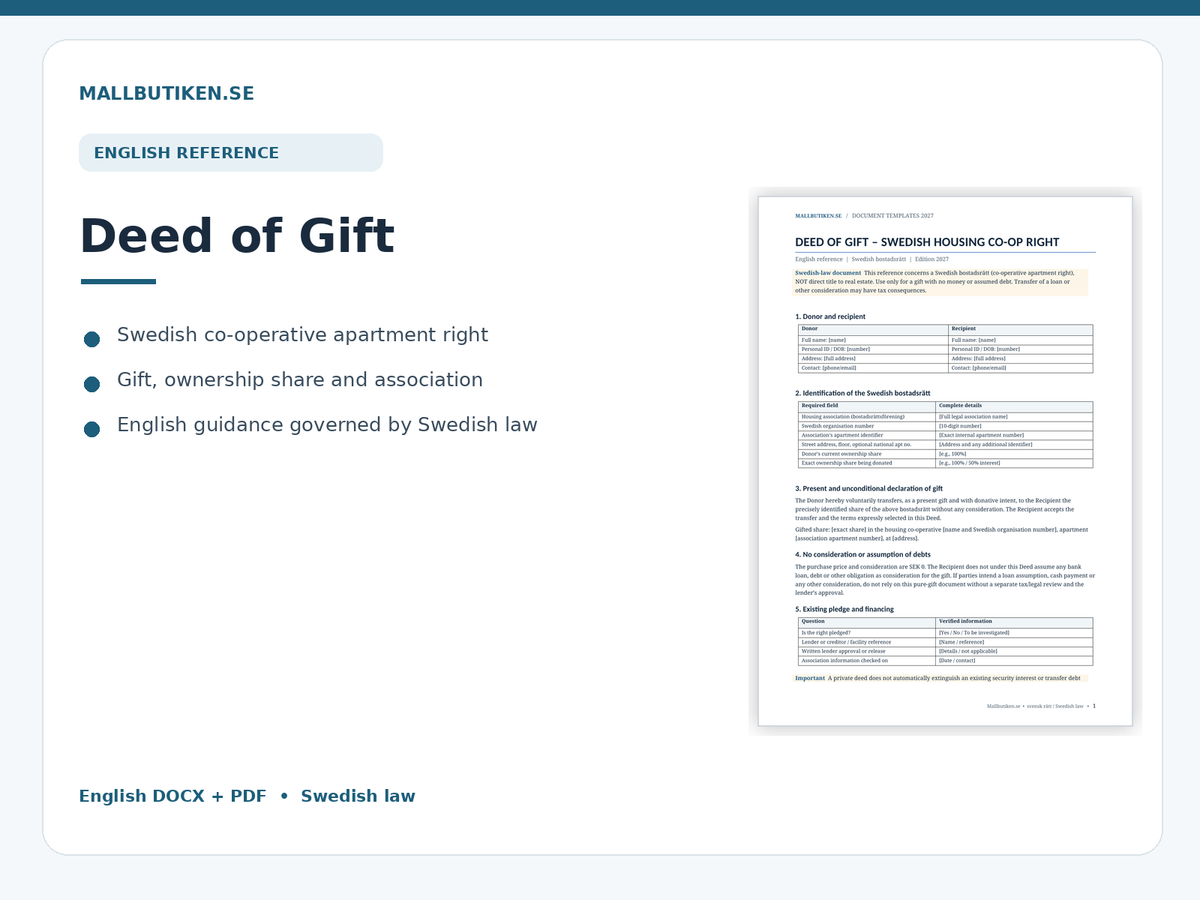
Deed of Gift for a cooperative apartment – Swedish template in Word and PDF, updated for 2027. Transfer the entirety or a specified share of a cooperative apartment as a pure gift without consideration, using a structured document where you fill in the donor, recipient, housing cooperative, apartment details, share of the gift, and the conditions that are to apply. The package includes the main Swedish template and guide, as well as an English reference and English guide.
Legal framework verified October 8, 2026.
The Cooperative Housing Act (1991:614), specifically Chapter 2 on membership and Chapter 6, sections 4–5 regarding transfers. In cases of payment, assumption of debt, pledging, deferred tax amounts, or complex family conditions, the agreement and tax situation require specific investigation.
What you get – 8 customer files
| Swedish Deed of Gift – DOCX + PDF | Main template including parties, cooperative/apartment, share of the gift, declaration of transfer, pledge, loan, membership, conditions and signatures, as well as a control appendix. |
| Swedish User Guide – DOCX + PDF | Step-by-step instructions and specific checks for loan assumption, tax, deferrals, separate property, advance on inheritance, and gifts between spouses. |
| Deed of Gift – English reference, DOCX + PDF | English reference version of the deed of gift, explicitly under Swedish law. |
| English User Guide – DOCX + PDF | English user instructions and legal limitations. |
Format: editable Word (DOCX) + searchable A4 PDF. Language: Swedish and English. Delivery: digital ZIP. Total of eight files.
Deed of Gift for a cooperative apartment – what formal requirements apply?
According to Chapter 6, Section 4 of the Cooperative Housing Act, an agreement regarding the transfer of a cooperative apartment must be made in writing and signed by the transferor and the acquirer. The document must identify the cooperative apartment and the terms of the transfer. This provision also applies to gifts. The new template therefore has specific fields for the cooperative's full name and corporate identity number, the cooperative's internal apartment number, address, and the exact share transferred.
In the case of a pure gift, the main template states that consideration and the purchase price are 0 SEK and that the recipient does not assume loans or any other counter-performance through the deed of gift.
Formal errors may result in invalidity under Chapter 6, Section 5 of the Cooperative Housing Act. However, there is no general requirement in this section for two people to witness a deed of gift for a cooperative apartment. Optional witness fields are included for documentation support nonetheless.
Membership in the housing cooperative is crucial
A signed gift document is not always enough.
The donee must normally be admitted as a member of the housing cooperative. If membership is refused, the transfer is as a main rule invalid according to Chapter 6, Section 5 of the Cooperative Housing Act. For gifts of only a share, Chapter 2, Section 6 and the cooperative’s bylaws must also be checked. Special rules apply to, among others, spouses and cohabitants.
The donee should submit the membership application and deed of gift to the cooperative in accordance with the cooperative's instructions. A cooperative apartment should not be confused with direct ownership of a real property, and a standard deed of gift for real estate cannot therefore be used as if the rules were identical.
Gift of half of the cooperative apartment or another share
The template has clear fields for the donor's current ownership share and the exact share being given away, for example, 50 percent. This is important both for identification and for the membership assessment. According to Chapter 2, Section 6 of the Cooperative Housing Act, a person who has acquired a share in the cooperative apartment may in certain cases be refused entry into the cooperative, unless the bylaws or special provisions for spouses and cohabitants dictate otherwise.
Therefore, check share transfers with the cooperative before signing. It is not sufficient to simply write "50%" in a document.
Loans and pledging – the gift does not automatically transfer the loan
A cooperative apartment can be pledged as security for a loan. The new template therefore has control fields for the lender, pledge, bank statements, and the cooperative's details.
If the recipient is to assume a mortgage or pay consideration, the transaction is no longer the simple gift that the main template is intended for. The bank must cooperate if the loan liability is to be changed, and the tax assessment must be made separately. A gift document alone cannot force the bank to accept a new borrower or release an existing security.
Gift or partial sale – tax consequences
Sweden does not have a gift tax. A pure gift without consideration does not normally trigger capital gains taxation solely due to the transfer. As a main rule, the donee assumes the donor's previous acquisition cost and other relevant tax circumstances according to the continuity principle (Chapter 44, Section 21 of the Income Tax Act).
For cooperative apartments, however, the split principle applies to certain transfers with consideration below market value and with a gift intention. A part of the transfer may then be a sale that is subject to taxation, while the rest is a gift. The Swedish Tax Agency explicitly describes this even when the parties have written a deed of gift.
Swedish Tax Agency – Sale of cooperative apartment and mixed gifts.
Does the donor have a tax deferral from a housing profit?
It is important to check if the cooperative apartment is a replacement property with a deferred tax amount from a previous home sale. In the event of a gift to a new owner, the deferral must in many cases be reversed for taxation, either fully or proportionally, even if the gift itself has no purchase price.
Swedish Tax Agency – When the replacement property is transferred via gift.
Separate property – for gifts from someone other than a spouse
Under certain conditions, a donor can stipulate that the gifted cooperative apartment shall be the donee's separate property according to Chapter 7, Section 2 of the Marriage Code. The main template contains an optional formulation with instructions to remove it if it is not to apply.
There is an important difference regarding gifts between spouses: the provision on separate property through gift conditions from a third party cannot simply be used for a gift from one spouse to the other. For separate property between spouses, a suitable prenuptial agreement and a separate check of family law formal requirements are normally required.
Advance on inheritance when parents give a cooperative apartment to children
When a parent gives a gift to a descendant, the gift is as a main rule presumed to be an advance on inheritance according to Chapter 6, Section 1 of the Inheritance Code, unless otherwise stipulated or if circumstances lead to a different assessment. The template therefore contains a clear choice between whether the gift shall count as an advance on inheritance or not.
Larger gifts and multiple descendants can give rise to further inheritance law issues, such as reinforced protection of the legal share. Request an individual assessment in such situations.
Is consent from a spouse or cohabitant required?
If the cooperative apartment constitutes a joint home, consent from a spouse or cohabitant may be needed according to, among other things, Chapter 7, Section 5 of the Marriage Code and Section 23 of the Cohabitants Act. This is a separate issue from the donee's membership. The template contains control fields for when consent is needed and whether a separate consent document has been attached.
Gift between spouses and the Marriage Register
For gifts between spouses, there are special rules regarding the gift's protection against the donor's creditors. According to the Swedish Tax Agency's guidance, registration with the Tax Agency may be necessary for this protection. Registration in the Marriage Register is different from the housing cooperative's membership review. The Tax Agency's registration service for gifts between spouses should not be used for gifts between other people.
Swedish Tax Agency – Gift between spouses.
Appendix: check the transfer before signing
The separate control appendix in the deed of gift helps you document that the following checks have been performed:
- Correct housing cooperative, corporate identity number, and apartment number.
- The donor's current ownership share and the exact share being transferred.
- That the gift is without money or assumption of debt.
- Any pledge, lender, and bank statements.
- Membership and the cooperative's rules regarding share acquisition.
- Consent from a spouse or cohabitant when needed.
- Deferrals, previous acquisition cost, and inheritance law conditions.
- Signing, the cooperative's receipt acknowledgment, and storage of documents.
How to use the template – step by step
- Open the Swedish DOCX file and verify that you intend a pure gift without consideration.
- Fill in complete information about both parties and the housing cooperative.
- Specify the cooperative's apartment number and which ownership share is being transferred.
- Check loans, pledges, and the cooperative's membership rules before signing.
- Actively choose whether conditions regarding separate property and advance on inheritance should apply.
- Check if a spouse or cohabitant needs to provide consent.
- Examine whether previous housing deferrals or other tax reasons need to be handled.
- Remove unused options and replace all placeholders within square brackets.
- Have both the donor and the donee sign the document.
- Send the deed of gift and membership application to the housing cooperative and save the original, decision support, and any bank statements.
Frequently asked questions about deeds of gift for cooperative apartments
Must a deed of gift for a cooperative apartment be in writing?
Yes. According to Chapter 6, Section 4 of the Cooperative Housing Act, a written agreement with both parties' signatures and identification of the apartment is required for gifts.
Must the deed of gift be witnessed by two people?
There is no general formal requirement of this kind for the gift transfer itself under Chapter 6, Section 4 of the Cooperative Housing Act. Optional witness fields are included in the template.
Can I give away half of my cooperative apartment?
Yes, but a gift of a share may lead to specific membership problems according to Chapter 2, Section 6. Check the cooperative's bylaws and any exemptions for spouses/cohabitants.
Does the donee need to be approved by the housing cooperative?
Normally, the donee must become or be a member. If membership is refused, the transfer is as a main rule invalid according to Chapter 6, Section 5.
Does the recipient automatically assume the loan on the cooperative apartment?
No. This normally requires separate handling and the lender's cooperation. Assumption of debt can also change the tax treatment.
Is the gift tax-free?
There is no Swedish gift tax, but a gift with consideration may contain a taxable sale portion. A previous deferred tax amount may need to be reversed even in the case of a pure gift.
Can the gift be separate property?
Yes, under the right circumstances. Conditions in a gift from someone other than a spouse work differently than the rules for gifts between spouses, where a prenuptial agreement may be required.
Are both Swedish and English included?
Yes. Deed of gift and guide in Swedish, as well as an English reference and English guide, all in Word and PDF according to Swedish law.
Related document templates
- Deed of Gift for Cooperative Apartment – English-first sister product
- Deed of Gift – advance on inheritance
- Prenuptial agreement – specifically indicated property
- Deed of Gift for real estate – separate template with other formal requirements
Official legal sources and guidance
The Cooperative Housing Act (1991:614), specifically Chapter 2, sections 3–6 and 10, and Chapter 6, sections 1 and 4–5.
Swedish Tax Agency – Sale of cooperative apartment and rules regarding deferrals for gifts. The Income Tax Act (1999:1229) Chapters 44 and 47; the Marriage Code Chapters 7–8; the Cohabitants Act Section 23; the Inheritance Code Chapter 6, Section 1.
Edition 2027. Legal framework verified against official sources October 8, 2026. The template pertains to a pure gift of a cooperative apartment in Sweden and does not replace individual legal, tax, or bank-related advice. Always check applicable rules and the housing cooperative's bylaws before use.
Read more about gifting a cooperative apartment
A written gift document needs to specify the correct cooperative apartment and share, be signed by both parties, and be handled with regard to the cooperative's membership rules.
- Deed of gift for cooperative apartment – formal requirements, membership, and tax
- Gift to children – how to document an advance on inheritance
A template needs to be adapted to the specific transfer. Also check bank, pledging, cooperative bylaws, and any family law consents.