About this template
Deed of Gift for movable property – Word and PDF. An updated, editable Swedish deed of gift template for ordinary movable property – for example, furniture, art, antiques, equipment, and other physical items. The template helps donors and donees document what is being gifted, who owns the item, when the gift is handed over, and any conditions regarding advancement of inheritance or separate property.
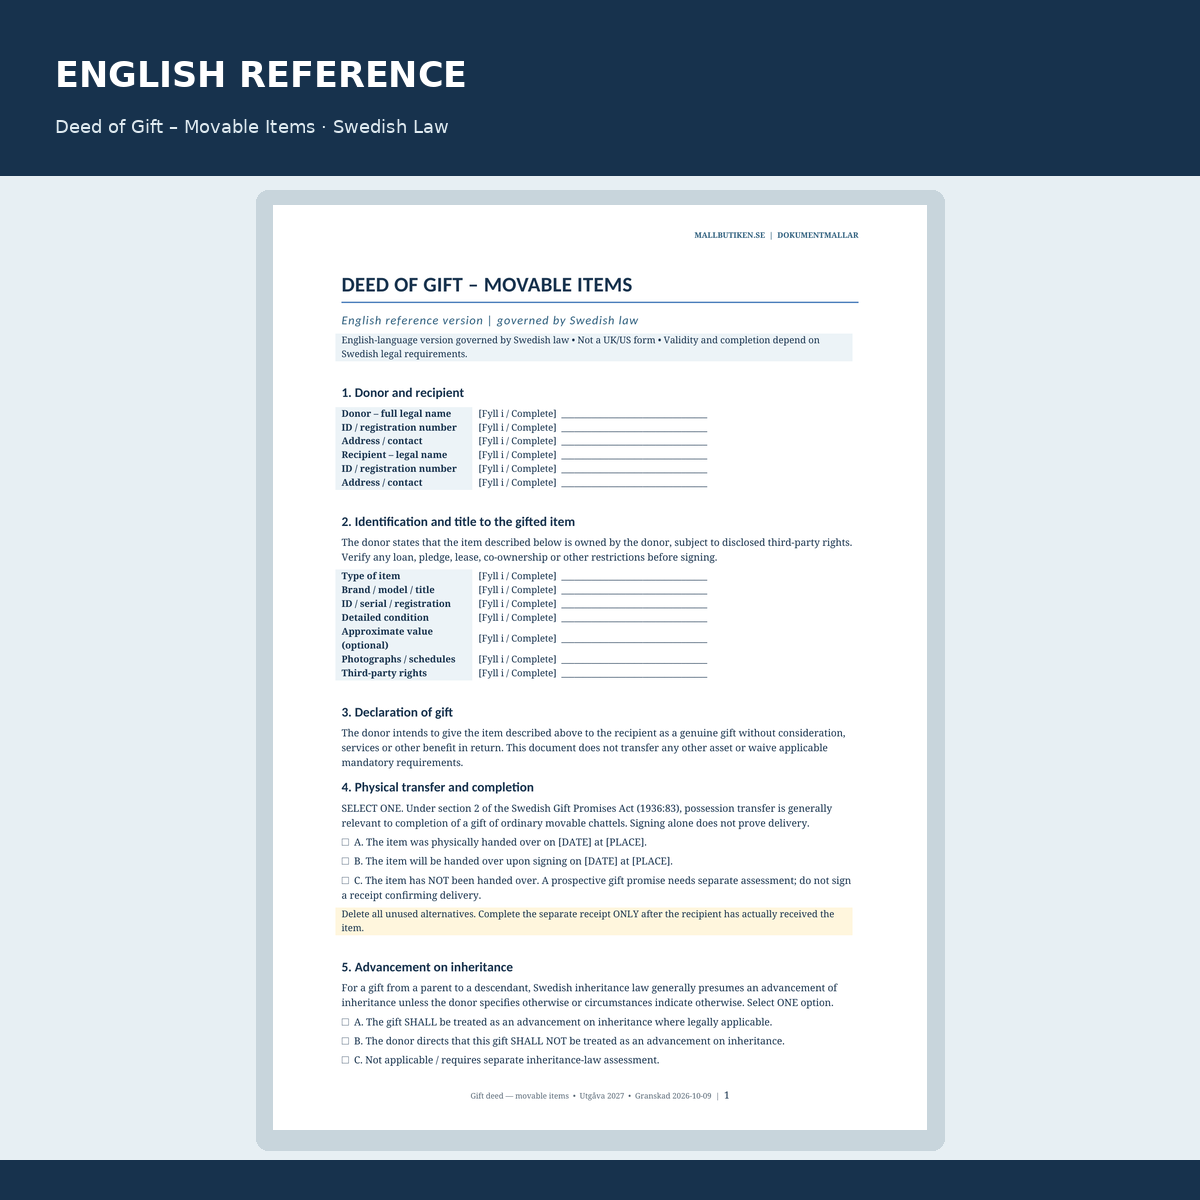
The new document delivery includes the main Swedish template and a Swedish user guide, as well as an English reference template and a separate English User Guide, all in Word and PDF. The English version is based on Swedish law and should not be considered a British or American deed of gift.
Designed based on the Act (1936:83) on Certain Promises of Gifts, the Inheritance Code, and the Marriage Code. The deed of gift is documentation support. Signing the document does not automatically mean that a gift of movable property has been completed.
This is included in the package
| Document | Usage |
|---|---|
| 01. Deed of Gift Movable Property – Swedish main template | Item description, gift declaration, conditions, signature, handover, and separate receipt. |
| 02. Swedish user guide | Step-by-step instructions, examples, legal regulations, and checklists. |
| 03. Deed of Gift – Movable Items | English reference template, governed by Swedish law. |
| 04. English User Guide | English guide to Swedish gift law and how to fill out the forms. |
8 new delivery files in total: each document is available as an editable DOCX and a searchable A4-PDF. The new ZIP file is connected manually by the store owner; existing digital delivery files are preserved in the meantime.
What is a deed of gift for movable property?
A deed of gift documents that a person intends to give certain property to another without consideration. The term movable property is legally broad, while this general template is primarily designed for physical movable items (chattels). For real estate, tenant-owned apartments, site leasehold rights, certain registered vessels, account-registered securities, and monetary gifts, there are other considerations and often more precise special templates.
When is the template suitable – practical examples
- A parent gives a piece of art, a piece of furniture, or a collector's item to their adult child.
- A grandparent gives identifiable equipment to a relative.
- Two individuals want to document an actual gift of tools, furniture, or home electronics.
- The donor wants to clarify whether a gift to a forced heir should be counted as an advancement of inheritance.
- The gift comes from a person other than the donee's spouse, and the donor wishes to stipulate that the property shall be separate property.
What does the new deed of gift template regulate?
1. Donor, donee, and accurately identified property
Information about the parties and the item – description, model, identification number, condition, any photos, and estimated value. Appendix A provides space for multiple items. Check that the donor has the right to dispose of the property and disclose any liens, leasing, or co-ownership relationships.
2. Handover – a deed of gift does not replace transfer of possession
According to Sections 1–2 of the Act (1936:83) on Certain Promises of Gifts, one must distinguish between an as-yet uncompleted promise of a gift and a completed gift. For ordinary movable property, it is generally significant that the donee actually takes the item into their possession. A signed deed of gift is therefore not in itself proof that the handover has already taken place. The template contains three exclusive choices for delivery status and a special receipt to be signed only after actual receipt.
3. Advancement of inheritance
According to Chapter 6, Section 1 of the Inheritance Code, a gift from a parent to a forced heir shall, as a starting point, be deducted as an advancement of inheritance, unless otherwise stipulated or apparent from the circumstances. For customary gifts, special assessment rules apply according to Chapter 6, Section 2. You can choose a clear formulation stating that the gift shall or shall not be deducted, or that the issue is not applicable.
4. Separate property
The donor can, in an appropriate third-party gift, stipulate that the item shall be the donee's separate property according to Chapter 7, Section 2 of the Marriage Code. The template distinguishes between property replacing the gift and returns. Gifts between spouses have special rules; the third-party clause cannot be used as an automatic alternative to a marriage settlement.
5. Handover receipt, signatures, and voluntary witnesses
The donee can acknowledge the actual receipt of the item with time and place, and there are separate signature fields. Two witnesses are not a general legal requirement for ordinary gifts of movable property. Witnesses can sometimes facilitate proof but do not replace handover or special rules for certain assets.
When should you not use this template alone?
- Real estate or site leasehold: special transfer and registration rules. Use a specifically designed gift document.
- Tenant-owned apartment (bostadsrätt): legally movable property but has its own formal requirements in the Tenant-Ownership Act, including a written transfer document and the association's membership rules.
- Money, shares, and securities: other rules regarding the completion of the gift may apply; choose a more specific template.
- Gift between spouses: assess registration, creditor protection, and the limitation of future gift promises according to Chapter 8 of the Marriage Code. The Swedish Tax Agency only registers ordinary gifts between spouses, not between, for example, parents and children.
- Gift to children: check representation, any conflict of interest situation, and guardianship administration according to the Children and Parents Code.
- Vehicles, boats, and other specific property: check ownership transfer/registration issues, any security, and insurance. A general deed of gift often needs to be supplemented.
How to use the deed of gift
- Open the Swedish main template in Word and read the user guide.
- Fill in the donor's and donee's details and identify the item carefully.
- Check that it is truly a gift without payment or other consideration.
- State whether the item has already been handed over, is being handed over simultaneously, or has not yet been handed over. Choose only one option.
- Determine the stance on advancement of inheritance and separate property; choose one option per section.
- Delete unselected options and clear square brackets that are not filled in.
- Sign the deed of gift and document the actual handover. Do not sign the receipt before the item is received.
- Keep a signed copy, photos, receipt, and any documents regarding origin or registration.
Practical example: gift of an artwork
A parent transfers a specific painting to their adult child. The deed of gift contains artist, title, photograph, and identification information. The parent states that the gift shall not be deducted as an advancement of inheritance and that the painting and its replacement shall be separate property. The handover receipt is filled in and signed only when the donee has actually collected the painting. If the circumstances deviate, an individual assessment is required.
Common mistakes
- Claiming that an ordinary gift of movable property must always be witnessed by two people.
- Dating the receipt of receipt before the gift has actually been handed over.
- Specifying the property so imprecisely that it cannot be identified.
- Treating a gift with consideration as an ordinary pure gift.
- Confusing third-party terms regarding separate property with a gift between spouses.
- Using a general template for a tenant-owned apartment, real estate, or registered property without regard to special rules.
Frequently asked questions
Must a deed of gift for movable property have two witnesses?
No, not as a general rule for an ordinary gift of movable property. Some other types of gifts are subject to special requirements. Voluntary witnesses can be used for evidentiary reasons.
Is a signed deed of gift always sufficient?
No. For an ordinary gift of movable property, the actual transfer of possession is of great importance for completion. An as-yet uncompleted promise of a gift is assessed according to other rules.
Does the deed of gift need to be registered with the Swedish Tax Agency?
Not an ordinary deed of gift between, for example, a parent and an adult child. The Swedish Tax Agency can register gifts between spouses, where special issues may arise.
Is a gift tax-free in Sweden?
A true gift is normally tax-free as an acquisition for Swedish income tax purposes according to Chapter 8, Section 2 of the Income Tax Act. Subsequent disposal, corporate transactions, and international conditions may require separate analysis.
Is an English version included?
Yes, an English-language reference governed by Swedish law and a separate English guide are included. The English template is not designed for American or British law.
Can I use the same document for a tenant-owned apartment?
No, not as the only document. A tenant-owned apartment is movable property in a legal sense but has special formal and membership rules.
Related document templates
- Deed of Gift – Movable Property (English sister product)
- Deed of Gift for money – Swedish main product
- Deed of Gift for tenant-owned apartment
Official legal sources
- Act (1936:83) on Certain Promises of Gifts, especially Sections 1–4.
- Inheritance Code (1958:637), Chapter 6, Sections 1–2.
- Marriage Code (1987:230), Chapter 7, Section 2 and Chapter 8, Sections 1–2.
- Income Tax Act (1999:1229), Chapter 8, Section 2.
- Swedish Tax Agency – gift between spouses.
Edition 2027. Legally reviewed against official sources on October 9, 2026. The template is general documentation support according to Swedish law and does not replace individual legal or tax advice. No guarantee is provided regarding legal validity, completion, or creditor protection in each individual case.