Svenska Dokumentmallar
Deed of Gift for Movable Property – Word/PDF Template
Deed of Gift for Movable Property – Word/PDF Template
- File format
- DOCX, PDF
- Document language
- Swedish (master version) + English (reference according to Swedish law)
- Number of files
- 8
Digital download. No physical product is shipped.
Couldn't load pickup availability
About this template
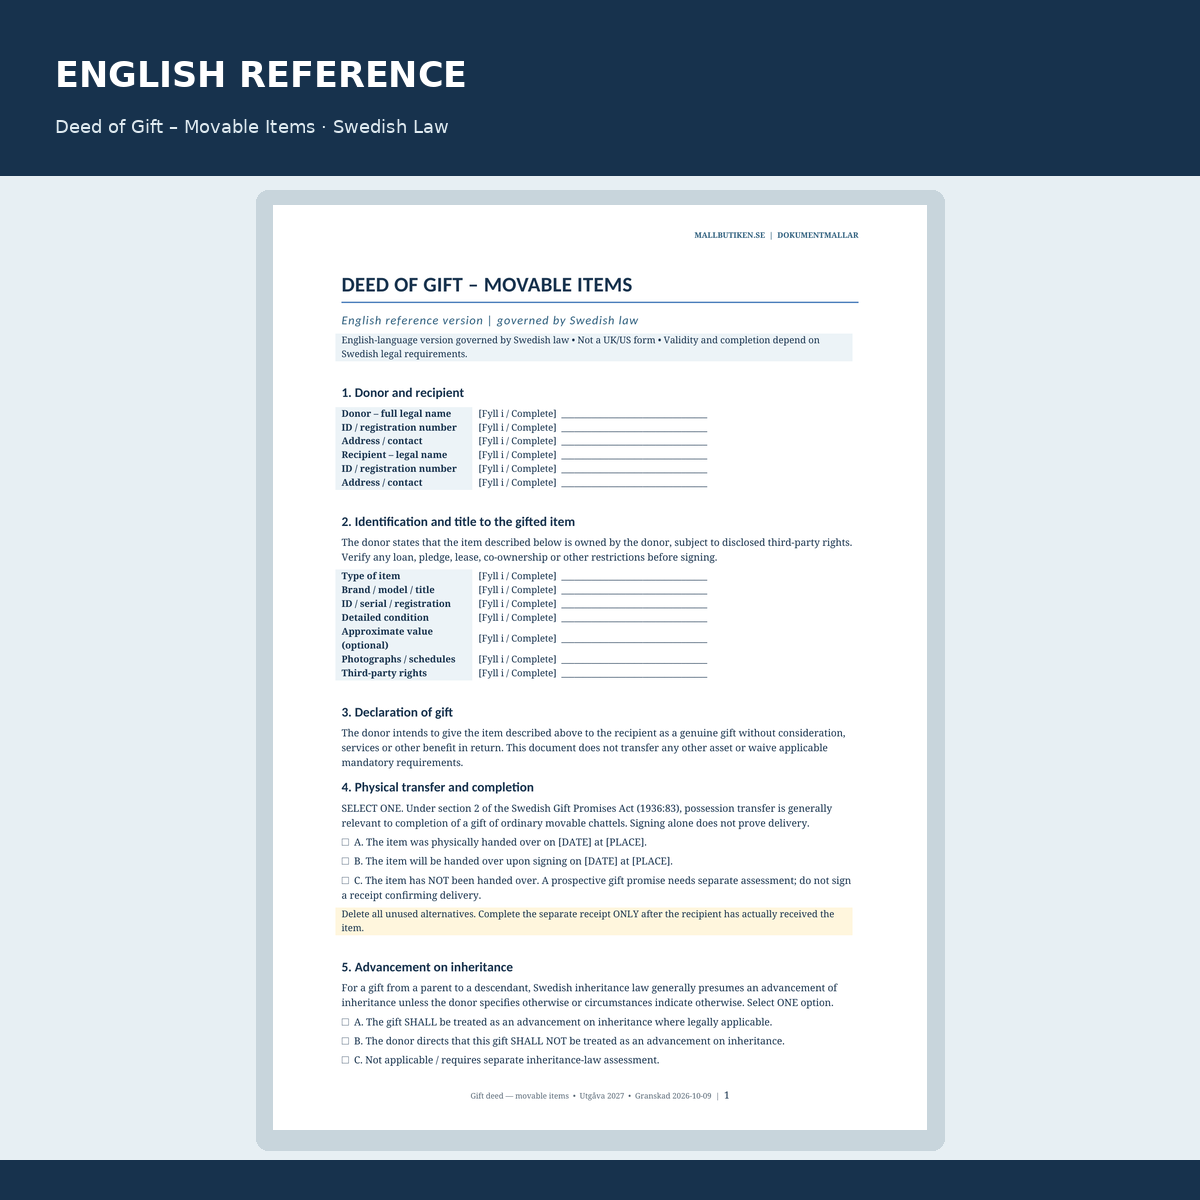
Deed of Gift for movable property – Word and PDF. An updated, editable Swedish deed of gift template for common movable property – for example, furniture, art, antiques, equipment, and other physical items. The template helps donors and donees document what is being given away, who owns the item, when the gift is handed over, and any conditions regarding advancement of inheritance or separate property.
The new document package includes a Swedish master template and a Swedish user guide, as well as an English reference template and a separate English User Guide, all in Word and PDF. The English version is based on Swedish law and should not be considered a British or American deed of gift.
Designed based on the Swedish Act (1936:83) on Certain Promises of Gifts, the Inheritance Code, and the Marriage Code. The deed of gift serves as documentation support. Signing the document does not automatically mean that a gift of movable property has been completed.
Included in the package
| Document | Usage |
|---|---|
| 01. Deed of Gift – Movable property – Swedish master template | Item description, gift declaration, conditions, signature, handover, and separate receipt. |
| 02. Swedish User Guide | Step-by-step instructions, examples, legal rules, and checklists. |
| 03. Deed of Gift – Movable Items | English reference template, governed by Swedish law. |
| 04. English User Guide | English guide to Swedish gift law and completion. |
8 delivery files are described in the package: each document is supplied as an editable DOCX and a searchable A4-PDF. The 2027 ZIP package is already attached to this product's digital delivery. Previously attached downloads remain available.
What is a deed of gift for movable property?
A deed of gift documents that a person intends to give certain property to another without consideration. The term movable property is legally broad, while this general template is primarily designed for physical movable objects (chattel). For real estate, tenant-owned apartments, leaseholds, certain registered vessels, account-based securities, and monetary gifts, there are other considerations and often more precise specialized templates.
When is the template suitable – practical examples
- A parent gives a work of art, a piece of furniture, or a collectible to their adult child.
- A grandparent gives identifiable equipment to a relative.
- Two individuals want to document an actual gift of tools, furniture, or home electronics.
- The donor wants to clarify whether a gift to a forced heir should be considered an advancement of inheritance.
- The gift comes from someone other than the donee's spouse, and the donor wants to stipulate that the property shall be separate property.
What does the new deed of gift template regulate?
1. Donor, recipient, and precisely identified property
Information about the parties and the object – description, model, identification number, condition, any photos, and estimated value. Appendix A allows room for multiple items. Verify that the donor has the right to dispose of the property and disclose any liens, leasing, or co-ownership relationships.
2. Handover – a deed of gift does not replace transfer of possession
According to Sections 1–2 of the Act (1936:83) on Certain Promises of Gifts, one must distinguish between an incomplete gift promise and a completed gift. For common movable property, it is generally significant that the recipient actually takes possession of the item. A signed deed of gift is therefore not in itself proof that the handover has already taken place. The template includes three exclusive choices for delivery status and a separate receipt to be signed only after actual receipt.
3. Advancement of inheritance
According to Chapter 6, Section 1 of the Inheritance Code, a gift from a parent to a forced heir shall as a starting point be deducted as an advancement of inheritance, unless otherwise prescribed or apparent from the circumstances. For customary gifts, special assessment rules apply under Chapter 6, Section 2. You can choose a clear formulation stating that the gift shall or shall not be deducted, or that the issue is not applicable.
4. Separate property
The donor can, in an appropriate third-party gift, stipulate that the object shall be the recipient's separate property in accordance with Chapter 7, Section 2 of the Marriage Code. The template distinguishes between property replacing the gift and the yield thereof. Gifts between spouses have special rules; the third-party clause cannot be used as an automatic alternative to a prenuptial agreement.
5. Handover receipt, signatures, and optional witnesses
The donee can acknowledge the actual receipt of the object with time and place, and there are separate signature fields. Two witnesses are not a general legal requirement for ordinary gifts of movable property. Witnesses can sometimes facilitate evidence but do not replace handover or special rules for certain assets.
When should you not use this template alone?
- Real estate or leasehold: special transfer and registration rules. Use a specially designed gift deed.
- Tenant-owned apartment (bostadsrätt): legally movable property but subject to specific formal requirements in the Tenant-Ownership Act, including written transfer documents and the association's membership rules.
- Money, shares, and securities: other rules regarding the completion of the gift may apply; choose a more specific template.
- Gift between spouses: assess registration, creditor protection, and the restriction on future gift promises under Chapter 8 of the Marriage Code. The Swedish Tax Agency only registers ordinary gifts between spouses, not between, for example, parents and children.
- Gift to children: check representation, potential conflicts of interest, and guardianship administration according to the Parental Code.
- Vehicles, boats, and other special property: check ownership transfer/registration issues, any security, and insurance. A general deed of gift often needs to be supplemented.
How to use the deed of gift
- Open the Swedish master template in Word and read the user guide.
- Fill in the donor's and recipient's information and identify the item accurately.
- Verify that it is indeed a gift without payment or other consideration.
- Indicate whether the item has already been handed over, is being handed over simultaneously, or has not yet been handed over. Select only one option.
- Decide on advancement of inheritance and separate property; choose one option per section.
- Delete unselected options and clear brackets that have not been filled in.
- Sign the deed of gift and document the actual handover. Do not sign the receipt before the item has been received.
- Keep a signed copy, photos, receipt, and any documents regarding origin or registration.
Practical example: gift of an artwork
A parent transfers a specific painting to their adult child. The deed of gift contains the artist, title, photograph, and identification details. The parent specifies that the gift shall not be deducted as an advancement of inheritance and that the painting and its replacement shall be separate property. The handover receipt is filled out and signed only when the recipient has actually collected the painting. If the circumstances differ, an individual assessment is required.
Common mistakes
- Claiming that an ordinary gift of movable property must always be witnessed by two people.
- Dating the receipt of receipt before the gift has actually been handed over.
- Specifying the property so imprecisely that it cannot be identified.
- Treating a gift with consideration as an ordinary pure gift.
- Confusing third-party clauses regarding separate property with gifts between spouses.
- Using a general template for a tenant-owned apartment, real estate, or registered property without regard to special rules.
Common questions and answers
Must a deed of gift for movable property have two witnesses?
No, not as a general rule for an ordinary gift of movable property. Certain other types of gifts are subject to special requirements. Optional witnesses can be used for evidentiary reasons.
Is a signed deed of gift always sufficient?
No. For an ordinary gift of movable property, the actual transfer of possession is of great importance for completion. An as-yet incomplete gift promise is assessed according to other rules.
Does the deed of gift need to be registered with the Swedish Tax Agency?
Not an ordinary deed of gift between, for example, a parent and an adult child. The Swedish Tax Agency can register gifts between spouses, where special issues may arise.
Is a gift tax-free in Sweden?
A true gift is generally tax-free as an acquisition in Swedish income taxation under Chapter 8, Section 2 of the Income Tax Act. Subsequent disposal, business transactions, and international relationships may require separate analysis.
Is an English version included?
Yes, an English-language reference governed by Swedish law and a separate English guide are included. The English template is not designed for American or British law.
Can I use the same document for a tenant-owned apartment?
No, not as the only document. A tenant-owned apartment is movable property in a legal sense but has special formal and membership rules.
Related document templates
- Deed of Gift – Movable Property (English sister product)
- Deed of Gift for money – Swedish main product
- Deed of Gift for tenant-owned apartment
Official legal sources
- Act (1936:83) on Certain Promises of Gifts, especially Sections 1–4.
- Inheritance Code (1958:637), Chapter 6, Sections 1–2.
- Marriage Code (1987:230), Chapter 7, Section 2, and Chapter 8, Sections 1–2.
- Income Tax Act (1999:1229), Chapter 8, Section 2.
- Swedish Tax Agency – Gifts between spouses.
Edition 2027. Legally reviewed against official sources October 9, 2026. The template is a general documentation aid under Swedish law and does not replace individual legal or tax advice. No guarantee is provided regarding legal validity, completion, or creditor protection in any individual case.
Guides: gift of movable property and validity of the gift
Giving away movable property differs from giving away real estate or a tenant-owned apartment. The written document can prove the content of the gift, but how the gift is completed must also be assessed.
- When does a gift become binding and what rules apply to movable property?
- Deed of Gift FAQ – common questions about formal requirements, conditions, and gift types
Special formal requirements may apply to certain registered assets. Therefore, verify which property is actually being transferred.