About this template
Board remuneration and fee resolutions – template package for limited companies
Does a limited company need to determine or administer compensation for the chairman of the board and board members? This package provides proposals for board remuneration, shareholder meeting resolutions, minutes attachments, fee notifications, payment journals, control checklists, and an Excel register. The templates help you document decisions per individual and follow up on payments without conflating company law, tax issues, and internal authorization.
01. Package contents
7 editable Word documents (DOCX), 7 corresponding searchable PDF files, and 1 Excel workbook (XLSX). A total of 15 files in a digital ZIP package. Five Swedish working templates, one Swedish user guide, and one separate English user guide. 2027 edition.
02. What the files contain
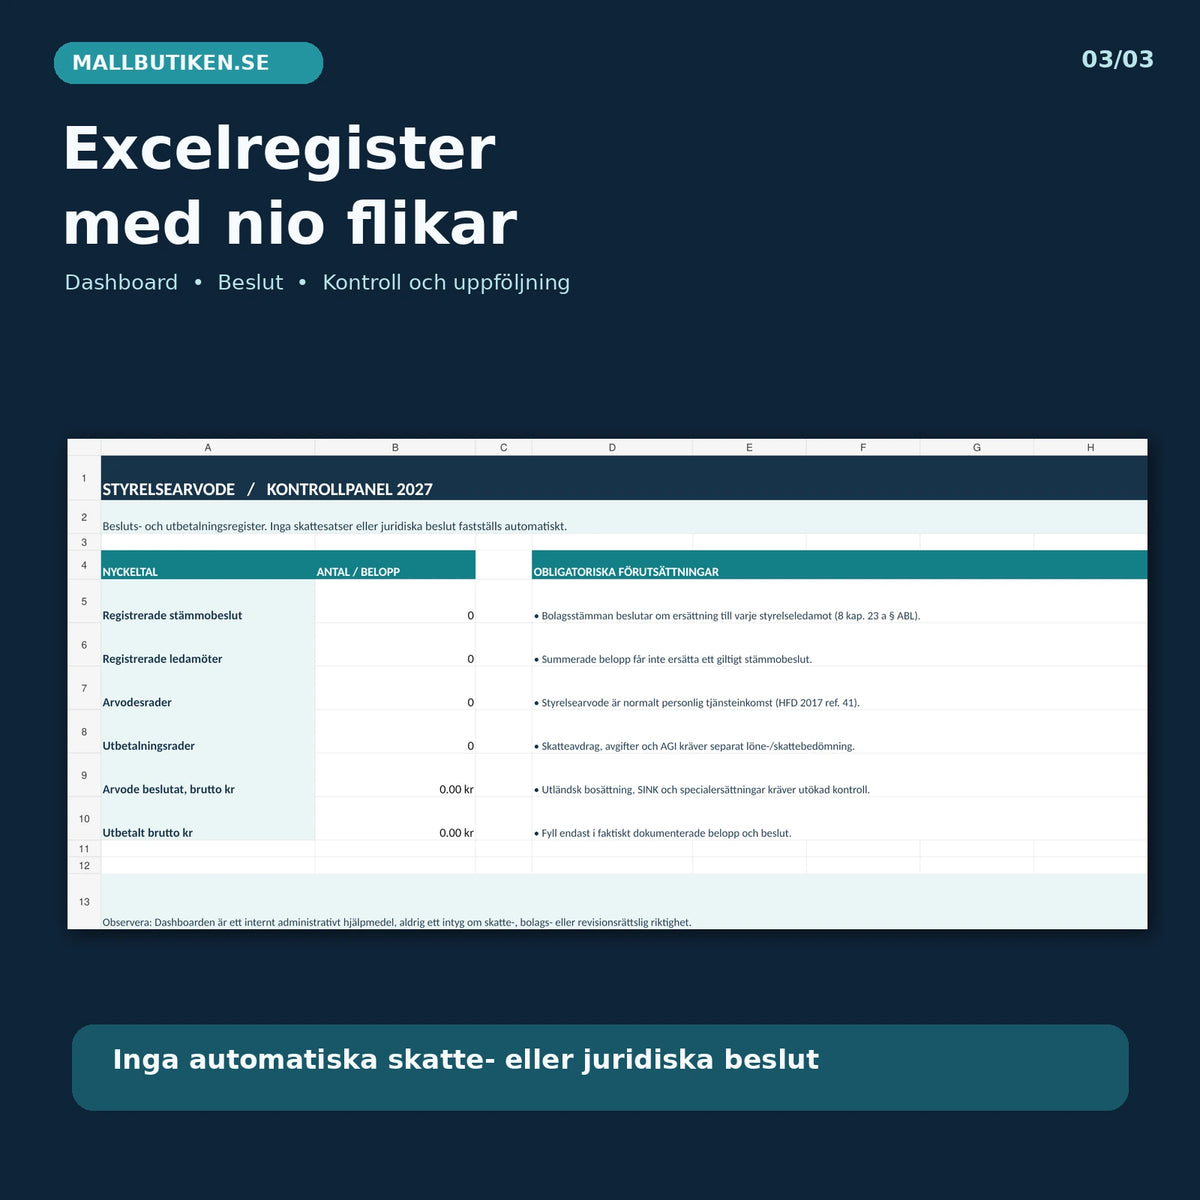
Individual remuneration proposals, meeting minutes attachment, notifications to board members, payment and authorization documentation, control and discrepancy checklists, and an administrative Excel tool. The Excel file contains nine tabs: dashboard, shareholder resolutions, board members, fees, payments, expense reimbursements, controls, discrepancies, and reading instructions.
Complete file list – 15 files
| No. | Document | Usage | Format |
|---|---|---|---|
| 01 | Proposal for board remuneration | Individual fee proposal for the general meeting. | DOCX + PDF |
| 02 | Shareholder resolution on board remuneration | Minutes attachment with compensation decisions per member. | DOCX + PDF |
| 03 | Fee notification and receipt | Information for the member and confirmation of receipt. | DOCX + PDF |
| 04 | Payment and authorization documentation | Administrative journal for gross fees and separately assessed tax. | DOCX + PDF |
| 05 | Control and discrepancy checklist | Decision, reporting, and archiving control. | DOCX + PDF |
| 06 | Swedish user guide | Legal boundaries, workflow, examples, and sources. | DOCX + PDF |
| 07 | English User Guide | English guidance for the Swedish working templates. | DOCX + PDF |
| 08 | Excel register for board remuneration 2027 | Nine tabs with dashboard and administrative registers. No automatic tax rates. | XLSX |
Who decides on board remuneration?
According to Chapter 8, Section 23 a of the Swedish Companies Act (2005:551), the general meeting shall decide on remuneration and other compensation for board assignments to each of the board members. It is therefore important to specify the recipient, gross remuneration, any other compensation, and the period the decision covers. Special compensation under Chapter 16 of the Companies Act is subject to additional rules and is not automatically covered by this standard package.
A minutes attachment is not always a complete set of meeting minutes; the regular minutes must also comply with the rules regarding, among other things, notices of meeting, resolutions, voting lists, and verification. The individual receipt is not a new fee decision.
How is board remuneration taxed?
According to the Swedish Tax Agency's guidance and precedent from HFD 2017 ref. 41, board remuneration is generally taxed as income from employment. The fact that a board member has F-tax (self-employment tax) or invoices through their own limited company does not automatically mean the compensation can be taxed as business income. Board remuneration is normally compensation subject to social security contributions; deductions, employer contributions, and employer returns need to be handled for the individual payment according to current regulations.
No fixed percentages for tax deductions or employer contributions have been pre-programmed. A special assessment is needed for, among other things, limited tax liability, international board assignments, other forms of compensation, age-related contributions, and any exemptions.
Excel for board remuneration – nine tabs
The workbook helps keep track of decision IDs, members, decided gross amounts, actual payments, expense reimbursements, and controls. A net amount can only be calculated after the user has manually entered both the gross amount and the correct tax deduction based on separate payroll processing. The dashboard displays registered items but can never prove that a shareholder resolution is valid or that the tax is correct.
How to use the templates
- Review existing shareholder resolutions, articles of association, appointment periods, and the role of each member.
- Prepare fee proposals separately for each member, including zero amounts where applicable.
- Pass resolutions at a duly convened general meeting and use the fee attachment with the complete minutes.
- Inform each member and reconcile that no notification deviates from the decided compensation.
- Perform individual tax and employer contribution assessments before payment.
- Document payment, authorization, verification, and employer return checks.
- Follow up on administrative discrepancies and preserve documentation with reasonable access restrictions.
Frequently asked questions
Can the board decide its own remuneration?
Standard board remuneration is decided by the general meeting in accordance with Chapter 8, Section 23 a of the Companies Act, not by the board deciding on its own compensation in a regular board meeting.
Is a total sum for the entire board sufficient?
The general meeting's resolution must include remuneration and other compensation for each of the board members. Therefore, use an individual allocation in the resolution.
Can the board member invoice the fee from their own company?
That does not automatically change the tax treatment. Board remuneration is normally taxed as income from employment per HFD 2017 ref. 41; exceptions must be assessed separately.
Does the Excel file calculate employer contributions and tax?
No. The Excel register is for administrative control only. For net amounts, tax deductions must be entered manually after separate assessment.
Are English contract documents included?
No. The working documents are in Swedish. An English user guide is included.
Related templates for limited companies
- Minutes of Annual General Meeting – limited company
- Declaration of conflict of interest and conflict protocol – limited company
- Agenda for constituent board meeting
Official legal sources
- The Swedish Companies Act (2005:551), especially Chapter 8, Section 23 a and Chapter 7 on general meetings
- Swedish Tax Agency – board remuneration and income from employment
- Swedish Tax Agency – compensation for work subject to contributions
Internal AI-assisted legal source and file review conducted on October 20, 2026. No external attorney or tax advisor has reviewed this product. The templates are general documentation aids and must be adapted to the individual company.