Svenska Dokumentmallar
DAC7 – seller-vetting, reporting basis and control log for digital platforms | Word/PDF/Excel
DAC7 – seller-vetting, reporting basis and control log for digital platforms | Word/PDF/Excel
- File format
- DOCX, PDF, XLSX
- Document language
- Five Swedish working documents Swedish User Guide English User Guide Swedish Excel workbook (nine tabs).
- Number of files
- 7
Digital download. No physical product is shipped.
Couldn't load pickup availability
About this template
DAC7 for digital platforms: a practical working basis for Swedish platform operators who need to assess reporting obligations, request and check seller information, and prepare the annual reporting to the Swedish Tax Agency. The package contains editable Swedish templates, searchable PDF files, and an Excel workbook. Excel does not submit control information or legally determine who must be reported.
Quick facts: Sweden and Swedish DAC7 rules · 7 independent documents (5 Swedish working documents, Swedish guide, English guide) · 7 Word DOCX + 7 searchable, static PDFs + 1 Excel XLSX = 15 customer files · Version 1.0 · digital ZIP download when the product is later activated. DOCX files can be edited, and PDFs can be read and printed, but are not interactively fillable. The English guide does not translate the main documents.
01. Package contents
Five Swedish working documents for applicability assessment, requesting information, checking, supplementing, and annual reconciliation. Two guides: one in Swedish and one in English. All seven documents are available as DOCX and PDF. In addition, an XLSX workbook with nine tabs is included. 15 files in total, not 15 different legal documents.
02. What the files contain
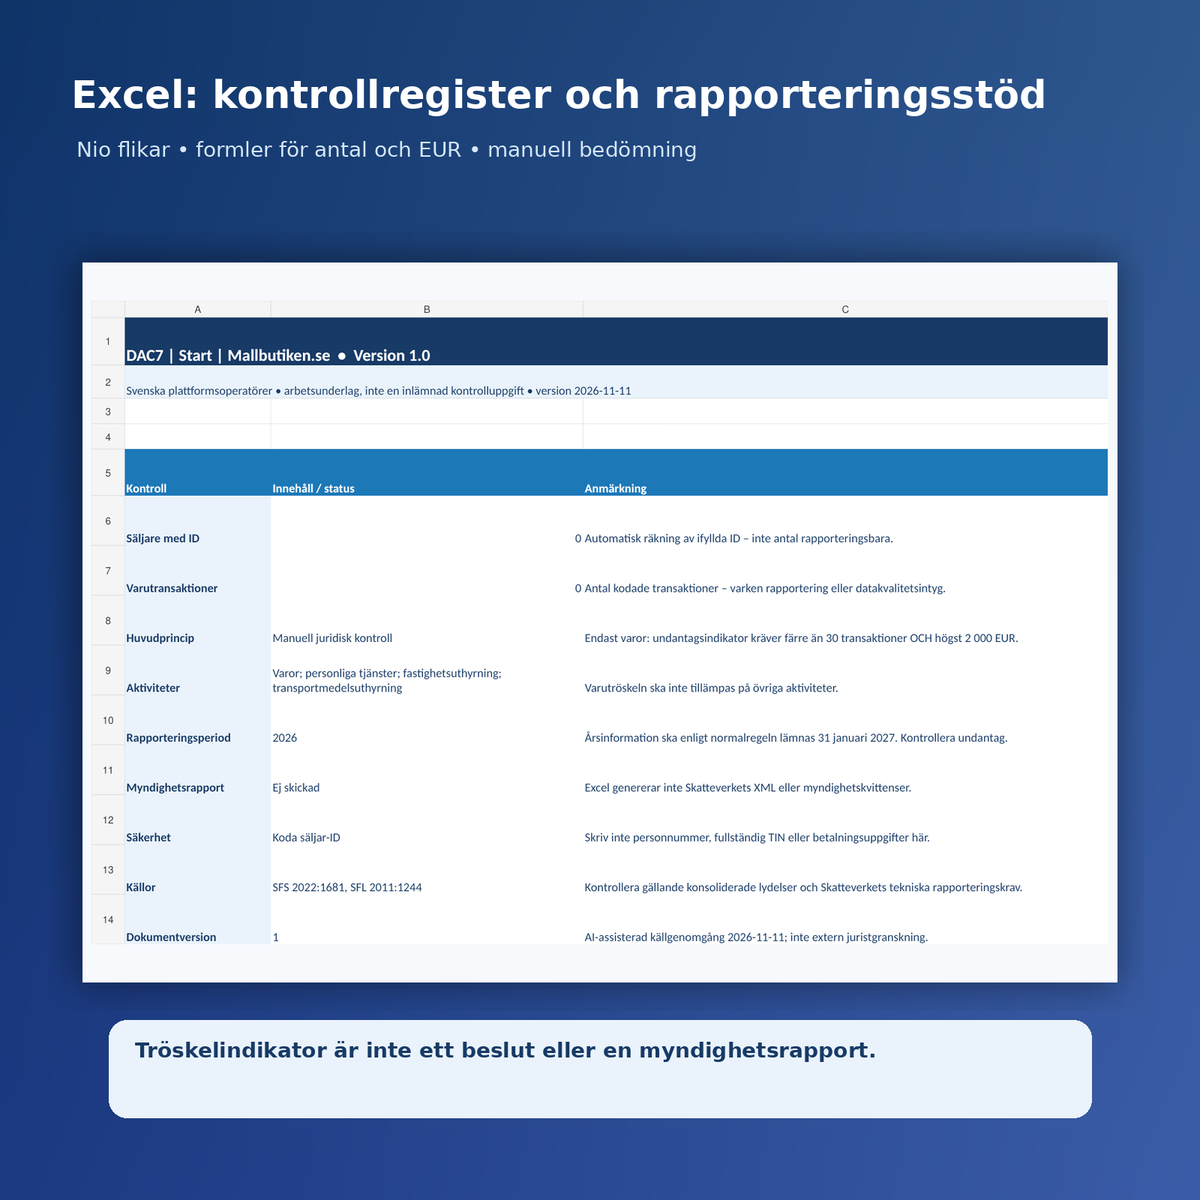
Identification of the platform operator and activity, secure seller inquiries, verification trails, and non-compliance management, documentation of reminders, annual reconciliation, decision-making support, and actual receipt from the authority. Excel shows the number of goods sales and the total verified remuneration in EUR per coded seller. The indicator must always be reviewed manually.
Who is the package for?
Example 1: a Swedish online marketplace that gathers many goods sellers and needs to check whether certain sellers are covered by a specific goods exemption. Example 2: a platform for renting out goods or personal services that needs to collect relevant seller information and document the year's reporting decisions. Not the right tool: a company that only handles payments, advertising, or forwarding without being a relevant platform – a specific applicability assessment is required.
All files and languages
| Document | Use | Language | Format |
|---|---|---|---|
| Applicability assessment | Assess operator, platform, activities, and exemptions | Swedish | DOCX + searchable PDF |
| Request for seller information | Request relevant information via a secure channel | Swedish | DOCX + searchable PDF |
| Control and verification protocol | Verify sellers, sources, and assessed exemptions | Swedish | DOCX + searchable PDF |
| Reminder and supplementation | Document missing information and contact attempts | Swedish | DOCX + searchable PDF |
| Annual reconciliation and reporting decision | Reconcile period, invoices, seller information, and archives | Swedish | DOCX + searchable PDF |
| User guide | Swedish instructions and control checklist | Swedish | DOCX + searchable PDF |
| English User Guide | English instructions for the Swedish forms | English | DOCX + searchable PDF |
| Excel workbook | Nine tabs for register, goods transactions, and threshold indicator | Swedish | XLSX |
Excel tool – what counts and what requires a decision?
The nine tabs are Start, Seller, Goods Transactions, Threshold Check, Know Your Customer, Supplementation, Annual Reconciliation, Decision, and Read Me. In the threshold check, the number and EUR amount from the registered goods transactions are used. A possible goods exemption indicator is displayed only when there are registered sales and both limits are met at the same time: fewer than 30 goods sales and at most 2,000 euros during the calendar year. Example: 29 sales and a total of 2,000 euros may result in an indicator, but 30 sales will not. The information must be verified, recalculated in case of corrections, and assessed against other legal conditions.
Amounts in EUR and any conversion must be checked and documented by the user. The workbook contains 80 registration rows for each relevant register and support for manual follow-up; it contains no live connection to the Swedish Tax Agency, no automatic exchange rate, and no legally binding reportability classification. Use internal seller IDs in Excel and store sensitive identity information in permission-controlled systems.
Workflow – from assessment to documented reporting
- Assess the platform's function and which activities are covered.
- Collect and verify only relevant seller and tax information via a secure channel.
- Review applicable exemptions, goods transactions, and currency basis.
- Follow up on any deficiencies and document reminders without automated sanctions.
- Perform the annual reconciliation, use the Swedish Tax Agency's actual reporting process, and document the receipt.
- Inform affected sellers and retain documentation in accordance with applicable storage and data protection requirements.
Legal prerequisites and limitations
The Swedish law (2022:1681) contains rules on which platforms, activities, and sellers are covered, as well as on the collection and checking of information. The goods exemption's number and amount conditions do not generally apply to personal services, property rental, or vehicle rental. See the law (2022:1681), especially Chapters 2 and 6.
The regular annual control information report and information to sellers should normally be submitted no later than January 31 of the year following the reporting year. For the calendar year 2026, this normally means January 31, 2027. Check the applicable prerequisites in the Tax Procedure Act (2011:1244), Chapter 22 c. as well as the Swedish Tax Agency's guidance. The Swedish Tax Agency's current e-service and technical file specification are still required.
Which document should you choose?
This package applies to DAC7 seller information and annual reporting. For a digital marketplace, questions about reporting illegal content and traceability under the Digital Services Act make another document package more relevant: DSA Marketplace Compliance.
Frequently asked questions
Are all Swedish online stores subject to reporting obligations under DAC7?
No. The decisive factors are the platform's actual function, activities, and the operator's status under the law. A regular online store that sells only its own goods is not automatically a DAC7 platform.
Is a goods seller always exempt under 2,000 euros?
No. The specific goods exemption requires fewer than 30 goods sales and at most 2,000 euros in remuneration during the period, with other legal conditions considered.
Can the Excel file be submitted directly to the Swedish Tax Agency?
No. The spreadsheet is an internal working register. The control information itself must be submitted through a current accepted reporting method and confirmed with actual receipt.
Are the PDF files fillable?
No. The PDF files are searchable and printable. The DOCX files are the editable main versions.
Are the main templates in English?
No. The five working documents and Excel are in Swedish. A separate English User Guide explains the use in English.
Sources, product version, and transparency
Document version: 1.0 (November 11, 2026). AI-assisted legal source check: November 11, 2026, against the official sources mentioned above. External independent legal review: not performed. The package is designed generally and does not replace an individual assessment of tax reporting, data protection, or cross-border issues.