Svenska Dokumentmallar
Consumer Credit 2026 – Payment Difficulties, Forbearance and Customer Actions | Word/PDF/Excel
Consumer Credit 2026 – Payment Difficulties, Forbearance and Customer Actions | Word/PDF/Excel
- File format
- DOCX, PDF, XLSX
- Document language
- Five Swedish work templates and a Swedish user guide; an English-language guide to the Swedish templates; Excel registers in Swedish
- Number of files
- 7
Digital download. No physical product is shipped.
Couldn't load pickup availability
About this template
Is a consumer having difficulty paying their credit? Document what the creditor needs to do when financial difficulties are detected, what contact and support measures have been carried out, whether a tailored payment offer is appropriate, and how special requirements for overdrafts should be checked. The specialist package provides creditors with an operational workflow before enforcement measures.
Current: The new Consumer Credit Act (2026:1011) comes into force on 20 November 2026. The package is a template for preparedness and actual individual processing; it is not a general rule that all credits must be renegotiated.
Package contents
Five Swedish work templates and two guides – all in editable Word (DOCX) and searchable, printable PDF: 01 early detection of payment difficulties, 02 customer letter and budget/debt counseling, 03 individual suitability assessment, 04 offer of payment relief/contract amendment, 05 overdraft and special twelve-month offer, 06 Swedish user guide and 07 English User Guide. In addition, 08 Excel – case and action register. Total 7 Word + 7 PDF + 1 Excel = 15 customer files.
What the files contain
Fields for credit type and contract date, transition check, early warning signs, counseling referral, verified default, individualized suitability assessment, customer communication, possible payment options, authorized attestation, chain of evidence, and follow-up. In Excel, only anonymized case IDs and status are stored – not names, personal identity numbers, account numbers, credit balances, or sensitive customer data.
Exactly which files do you get?
| Work file | Practical function | Language and format |
|---|---|---|
| 01 Early detection procedure | Establish risk indicators, responsible function, follow-up, and path to budget/debt counseling. | Swedish · editable DOCX + searchable PDF |
| 02 Customer letter about counseling | Inform factually about detected difficulties and where the customer can turn for support. | Swedish · DOCX + PDF |
| 03 Individual suitability assessment | Assess personal circumstances, repayment ability, possible options, and documented decision in case of default. | Swedish · DOCX + PDF |
| 04 Offer of contract amendment | Basis for an offer of an adjusted payment plan or other suitable alternative; requires actual contract check and acceptance. | Swedish · DOCX + PDF |
| 05 Overdraft – 12 months | Separate assessment of information before termination or reduction, and the possibility of twelve equal monthly payments according to applicable terms. | Swedish · DOCX + PDF |
| 06 Swedish user guide | Work order, exceptions, transition rules, examples, and source references. | Swedish · DOCX + PDF |
| 07 English User Guide | Explains how the Swedish templates should be used. The work templates are not translated into English. | English · DOCX + PDF |
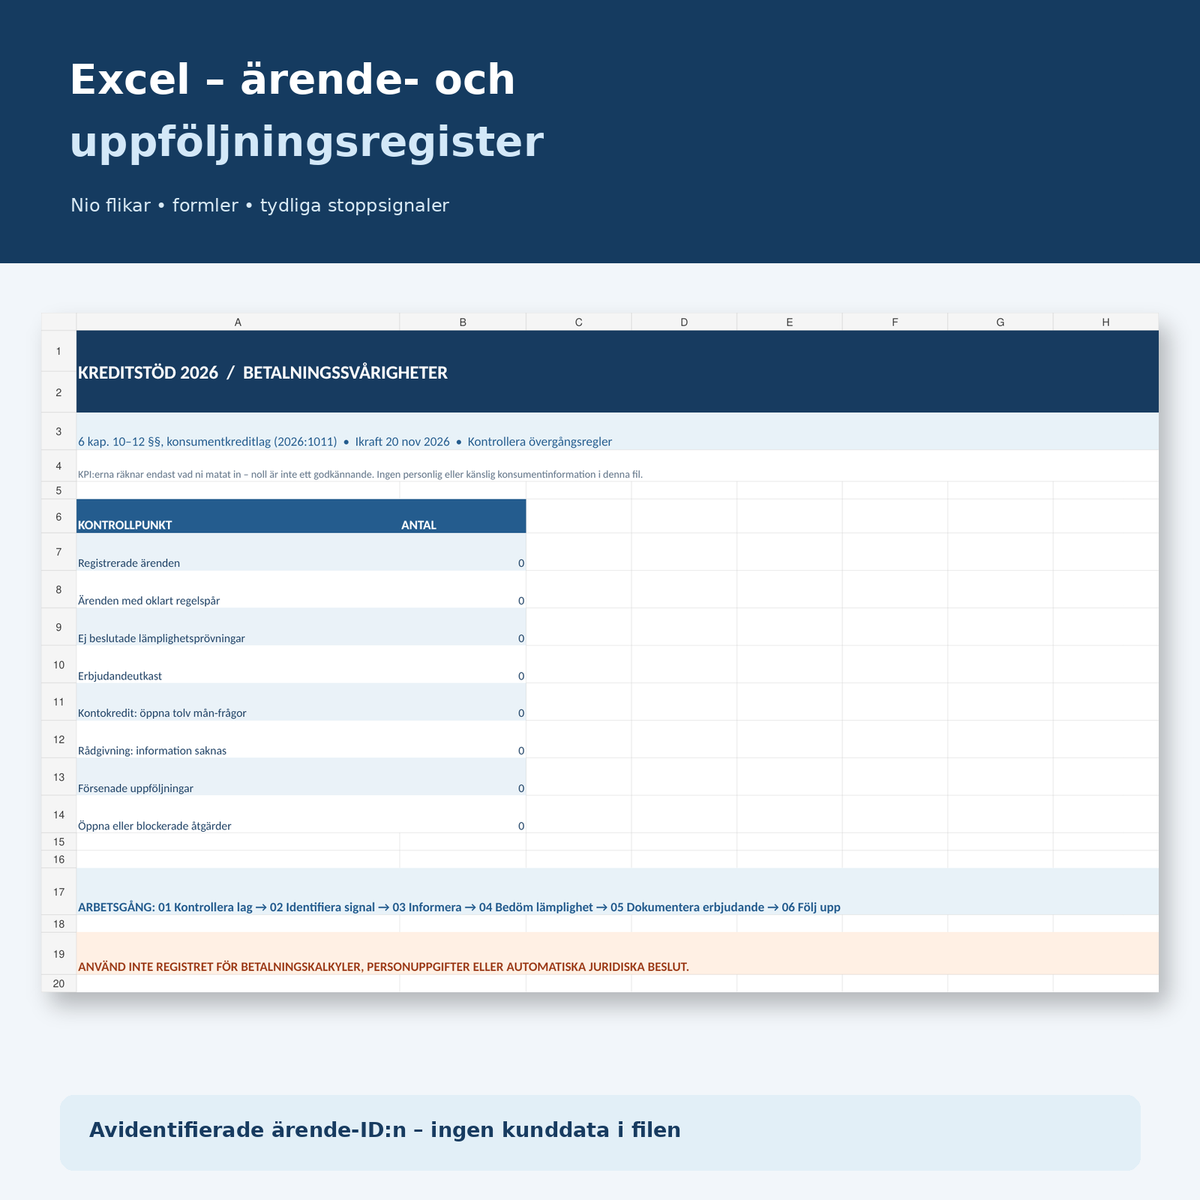
| 08 Excel register | Nine tabs with manual case status, basis, checkpoints, and formula-based compilation. | Swedish · editable XLSX |
Nine Excel tabs with checkpoints
Overview, Cases, Suitability, Offers, Overdraft, Counseling, Follow-up, Actions, and Read me. There are status options and formulas that count registered cases, unclear transition issues, open suitability assessments, offer drafts, special overdraft issues, missing counseling information, delayed follow-ups, and open or blocked actions.
Excel only counts what the user actually registers. Zero cases or warnings does not automatically mean that the requirements of the law are met. The register file contains no personal data, no interest calculator, and no automatic legal decision engine.
Legal basis – important differences
Chapter 6, Section 11 – early detection: the creditor shall have procedures and guidelines to detect financial difficulties to fulfill the credit agreement early. When such difficulties are detected, the customer shall receive information about where he or she can turn for support in budget and debt issues.
Chapter 6, Section 12 – alternatives in case of default: if the consumer is in default, the creditor shall, when appropriate, offer alternatives to enforcement measures that involve changing the credit agreement. The individual assessment shall consider the consumer's personal circumstances and repayment ability. It is not an unconditional right to stay of execution or an automatic prohibition of collection.
Chapter 6, Sections 9–10 – certain overdrafts: a termination or reduction of the credit limit in certain agreed overdrafts requires special information, in affected cases at least 30 days before the change takes effect. The creditor shall, under the conditions in Section 10, offer the possibility to pay the overdue amount in twelve equal monthly payments together with credit interest before enforcement measures are taken. It is a special rule, not a general twelve-month guarantee for all loans.
Chapter 6, Section 13 – exceptions: certain special invoice credit is exempt from Chapter 6, Section 8, while securities credits are exempt from Chapter 6, Sections 11–12, among others. The exact scope of the exceptions must be examined before a template is used.
Transitional provisions: credit agreements entered into before November 20, 2026 are generally still covered by the older consumer credit act with special specified exceptions. A creditor should therefore not mechanically apply all new process rules to older agreements.
For background: Consumer Agency information from November 2026 and Financial Supervisory Authority general advice FFFS 2026:32. The FI's general advice has a different legal status than binding legal provisions.
How to use the package
- Identify the creditor, credit type, licensing/supervision conditions, and contract date.
- Check which regulatory framework and which exceptions apply in the individual case.
- Document early signs and information about municipal budget and debt counseling.
- In case of verified default: individually assess whether contract amendment or payment relief is appropriate.
- Separately assess whether the overdraft is covered by the 30-day information and twelve-month offer.
- Decide with the authorized function, check the actual amounts and terms in the business's credit/financial system, and provide correct customer information.
- Save the basis in a protected customer file and use only anonymized case references in Excel.
Difference from other Mallbutiken templates
BNPL – checkout and credit check focuses on consumer credits before credit is granted. Automated credit assessment refers to human review and rejection. Contesting collection demands is for those who object to a demand. This product concerns the creditor's actions when a consumer already has or risks payment difficulties.
Frequently asked questions
Must a creditor always grant a payment stay?
No. Chapter 6, Section 12 presupposes an individual assessment of whether a contract-amending alternative is appropriate in case of payment default.
Must the customer receive information about debt counseling?
For creditors covered by Chapter 6, Section 11, there is an information obligation when financial difficulties are detected. Credit law, exceptions, and transition rules must be examined.
Do all customers have the right to twelve months of installment payments?
No. The special twelve-month rule in Chapter 6, Section 10 refers to certain situations when the creditor terminates or reduces the credit limit for an overdraft.
Can Excel be counted as a complete customer file?
No. The files are for process logging and secure evidence references. The customer's personal data and credit basis belong in an access-protected system.
Can I use the package for older credit agreements?
Only after checking the transition rules. Older agreements are basically covered by the earlier law with certain express exceptions.
Are the PDF files digitally fillable?
No. The PDFs are searchable and suitable for printing; DOCX and XLSX are the editable files.
Are English customer letters or credit agreements included?
No. The work templates are Swedish. English User Guide helps English-speaking users understand them.
Version and legal transparency
Version 1.0 · November 12, 2026. Sources have been reviewed with AI assistance based on public Swedish law and authority information. No external legal review, actual credit assessment, legal attestation, payment calculation, or authority certification has been carried out. Check the legal status, applicable supervision, and your customer agreements with an expert function before use. The ZIP customer file is not linked to Digital Products until the product draft has been approved for publication.