Svenska Dokumentmallar
Consumer Credit 2026 – SECCI Pre-contractual Information, Proof of Delivery and 14-Day Right of Withdrawal | Word/PDF/Excel
Consumer Credit 2026 – SECCI Pre-contractual Information, Proof of Delivery and 14-Day Right of Withdrawal | Word/PDF/Excel
- File format
- DOCX, PDF, XLSX
- Document language
- 5 Swedish work templates + Swedish user guide; separate English User Guide; Swedish Excel workbook.
- Number of files
- 7
Digital download. No physical product is shipped.
Couldn't load pickup availability
About this template
Check that the correct pre-contractual information has been provided before the credit agreement and that this can be proven. For Swedish lenders and affected credit intermediaries working with the new Consumer Credit Act (2026:1011). Specialized check of SECCI’s 27 information points, timely dispatch, readable durable medium, and renewed right of withdrawal information when the special seven-day rule applies.
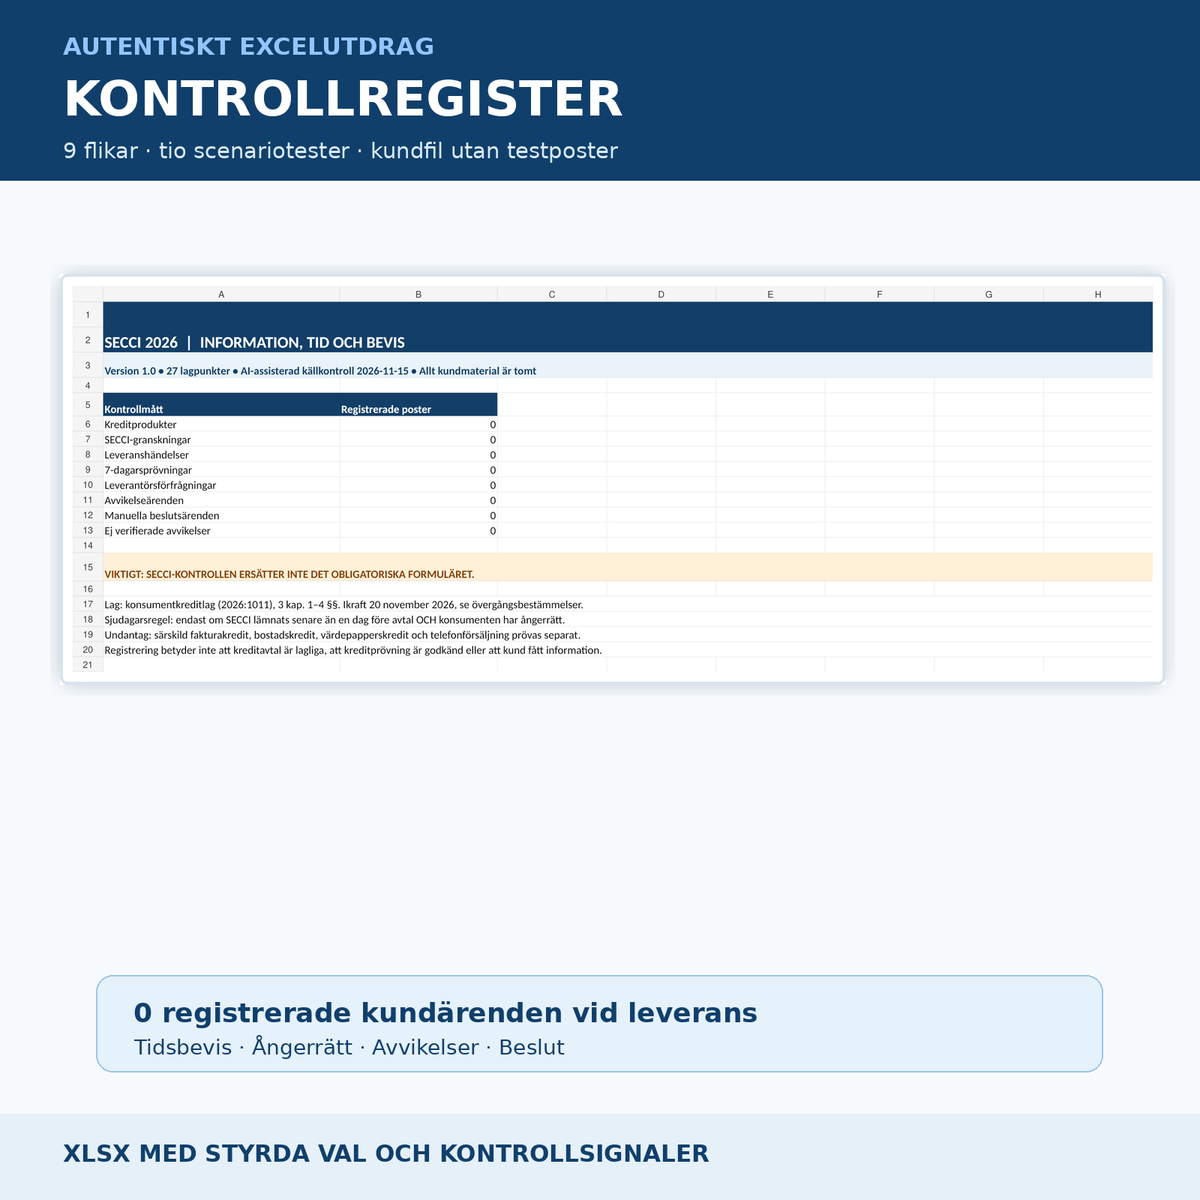
Quick facts: Swedish law coming into force on 20 November 2026 · 5 Swedish working documents, 1 Swedish guide, and 1 separate English User Guide · 7 editable Word (DOCX) files, 7 corresponding searchable and printable PDFs, and 1 Excel workbook (XLSX) with 9 tabs. Total 15 customer files via ZIP after separate activation of digital delivery. The PDF files do not contain interactive form fields.
01 · Package contents
Five Swedish check templates, one Swedish user guide, and one separate English user guide. All seven documents are available in both DOCX and corresponding PDF formats. In addition, there is a Swedish register with 9 tabs and tested check formulas. 7 DOCX + 7 PDF + 1 XLSX = 15 actual files – not 15 different legal documents.
02 · What the files contain
Role and applicability check and relevant exceptions; a point-by-point comparison of all 27 information points under Chapter 3, Section 1; protocol for the actually selected durable medium and time of delivery; renewed right of withdrawal information under Chapter 3, Section 2 only when the conditions are met; the supplier’s version and delivery proof; and a deviation and decision log. Excel separates completed, documented, and separately verified items.
Who can benefit from the SECCI package?
Example 1 – lender: A financial company changes its individual pricing details before 20 November and must check that the actual standardized pre-contractual information contains the correct interest rate, fees, payment plan, and right of withdrawal notice for a specific offer.
Example 2 – intermediaries and suppliers: A credit intermediary and its system supplier need to show which form was generated, which party delivered it, when the consumer actually read it, and what checks were taken after an incorrect version.
Not the right package: A standard Shopify store with external invoice/BNPL options that primarily needs to test its checkout and credit partner should instead use BNPL & Invoicing in E-commerce. For credit advertisements, use Credit Advertising 2026. This package is not the credit agreement itself, the credit assessment model, the standardized EU fact sheet for housing credit, or an official SECCI form.
Exact file contents
| File | Function | Format |
|---|---|---|
| 01 – Role and applicability check | Lender/intermediary, credit type, exceptions, older agreements, and liability | DOCX + PDF |
| 02 – SECCI: 27-point check | Check of all 27 numbered items under Chapter 3, Section 1 against the actual SECCI original | DOCX + PDF |
| 03 – Timing, delivery, and 7 days | Reasonable time, readable durable form, actual dispatch log, and conditional right of withdrawal information | DOCX + PDF |
| 04 – Supplier issues and chain of evidence | Liability issues, supplier certificate, form versions, and proof of receipt | DOCX + PDF |
| 05 – Deviation, correction, and Go/No-Go | Deviations, re-testing, manual decision, and stop signal | DOCX + PDF |
| 06 – Swedish user guide | Swedish workflow, sources, scope, and four test scenarios | DOCX + PDF |
| 07 – English User Guide | English instructions for the Swedish working templates, not translated main documents | DOCX + PDF |
| 08 – Excel register with nine tabs | Credit products, SECCI points, delivery, right of withdrawal, suppliers, deviation, and decision | XLSX |
All five main forms are in Swedish. The English file is an English User Guide for the Swedish templates, not translations of the main documents.
Excel – nine working tabs with check signals
The tabs are Overview, Credit Products, SECCI-27, Delivery Log, Right of Withdrawal 7d, Suppliers, Deviations, Decisions, and Read Me. The overview contains eight administrative key figures. The customer register is empty upon delivery – all key figures show 0. In SECCI-27, one row is kept per actual credit product and legal point; the check tool does not automatically fill in any mandatory consumer information.
Tested status logic distinguishes, for example, between: information provided too late without a right of withdrawal, unclear right of withdrawal, missing renewed information, information sent after seven days, and a deviation marked as “Completed” that still lacks independent verification proof. Excel does not calculate the effective interest rate, determine legal applicability, or certify legal compliance.
Workflow
- Determine who is the lender and the affected credit intermediary, the credit law, and the time of the agreement.
- Check the scope: special invoice credit, securities credit, housing credit, telephone sales, and transitional rules.
- Retrieve the correct consumer-specific standard form “Standardised European Consumer Credit Information”.
- Review the 27 information points of the law against each concrete version of the form.
- Document when and in what readable, durable form the consumer actually received the information.
- If the information was provided less than one day before the agreement: check whether the consumer has a right of withdrawal; if so, renewed information about the right of withdrawal and how it is exercised is required within seven days after the agreement.
- Follow up on deviations and conduct separate authorized manual checks. Store only pseudonymous case IDs in the workbook.
Legal requirements and important limitations
New law: The Consumer Credit Act (2026:1011) comes into force on 20 November 2026 with special transitional rules for older credit agreements.
Pre-contractual information: Chapter 3, Section 1 contains 27 numbered information points. According to Chapter 3, Section 3, the information must be provided in accordance with the form Standardised European Consumer Credit Information. It must be clear, understandable, and all information must be equally prominent. According to Chapter 3, Section 4, the consumer must be able to choose an available readable, durable form.
Late information: According to Chapter 3, Section 2, information must be provided in a reasonable time before the agreement. When it is provided less than one day before the agreement, a consumer who has a right of withdrawal must be provided with renewed information about the right of withdrawal under Chapter 3, Section 1, paragraph 1, point 10, and how it is exercised, within seven days after the agreement is concluded. This is not a general seven-day requirement for all credits.
Special rules: For housing credit, the rules in Chapter 8 and another standardized EU fact sheet may apply. For certain telephone sales, special rules apply under Chapter 3, Section 5. Special invoice credit requires checking against the law’s special definition and exceptions. A supplier’s assurance or internal check does not replace legal liability for the actual credit product.
Questions and answers
Does the SECCI form itself that is to be given to the consumer apply?
No. The product contains internal check and evidence templates for the actual mandatory standard form. Retrieve and fill in the correct official format for the credit agreement.
Do I always need to send new right of withdrawal information within seven days?
No. The special rule in Chapter 3, Section 2 presupposes both that information was provided less than one day before the agreement and that the consumer has a right of withdrawal. The actual right of withdrawal must be assessed separately.
Do the documents also apply to housing loans?
Not as a completed main workflow. Housing credits require a special assessment under Chapter 8 and normally another standardized EU fact sheet.
Can Excel prove that a consumer has received SECCI?
No. The workbook records references to actual delivery logs and archive evidence that must be checked in the responsible system.
Can I enter personal identity numbers and credit checks?
This is not recommended. Use pseudonymous internal reference IDs and handle personal data in secure, access-controlled systems.
Are all documents in Swedish and English?
Five check templates and Excel are in Swedish. One Swedish guide and a separate English User Guide are included. The main documents are not translated into English.
Can I edit the PDF files?
The PDFs are text-based and printable without interactive fields. Use the Word files for editing.
Legal sources, dates, and quality
Primary legal source: SFS 2026:1011, especially Chapter 1, Chapter 3, Sections 1–5, Chapter 8, and the transitional provisions. Supplementary: The Swedish Consumer Agency’s guidance for affected businesses; Directive (EU) 2023/2225. Product version 1.0 · AI-assisted source check 15 November 2026. No independent external legal review, regulatory certification, or guarantee of legal compliance has been carried out.