Svenska Dokumentmallar
Revoke the accounting firm's permissions – tax return agent, SKV 4804 and access certificate | Word/PDF/Excel
Revoke the accounting firm's permissions – tax return agent, SKV 4804 and access certificate | Word/PDF/Excel
- File format
- DOCX, PDF, XLSX
- Document language
- Five Swedish work templates Swedish guide English User Guide; Excel in Swedish
- Number of files
- 7
Digital download. No physical product is shipped.
Couldn't load pickup availability
About this template
Has the company terminated its accounting firm – but does it know if the former consultant's tax representative status, tax account access, bank authorization, and system logins have actually ceased? Terminating a service agreement does not automatically remove all registered authorizations. This document package for Swedish companies helps those responsible for finance inventory each authorization, choose the correct revocation method, document actual receipts, and keep access issues open until they are verified.
15 customer files in Word/PDF/Excel: five Swedish working documents, one Swedish user guide, and one English User Guide – all seven editable DOCX and seven searchable, printable PDF files – plus one XLSX with nine tabs. The PDFs are not interactively fillable. The working templates and Excel file are in Swedish; the English guide is for instruction and is not a complete English translation of the agreement. Software for DOCX, PDF, and XLSX is required.
01 · Package Contents
Authorization inventory; Swedish Tax Agency revocation basis for the correct e-service or official form; bank and financial system access; GDPR/return/archiving; final receipt with deviation report; Swedish guide and English User Guide. 7 DOCX + 7 PDF + 1 Excel = 15 files. In addition, nine Excel tabs for tracking the Swedish Tax Agency, bank, system access, personal data, and archives.
02 · What the Files Contain
Fields for organization type, outgoing accounting firm, representative role, portal, actual revocation method, submission receipt, post-check of registration status, bank and authorization permissions, payroll system, API integrations, data processor return responsibilities, retention requirements, and separate evidence references. All statuses must be filled in after an actual check; clicking “send” is not the same as a terminated authorization.
Who Is This Useful For?
Example A – a limited company changes accounting firms: the former accounting consultant may still be able to submit or view information for the company with the Swedish Tax Agency. Collect the current representative list and check the revocation separately from the termination of the agreement. Example B – multiple bank/system roles: the agency representative has been removed, but an old bank authorization or financial system user account remains. Follow the bank's and the provider's own procedures and verify the removal. Example C – accounting and payroll data: check return, deletion, and statutory retention before any party deletes old files.
The package is not a power of attorney or official form SKV 4804, does not terminate a service agreement, does not perform any automatic agency or bank action, does not actually block access, does not include SIE export, and does not guarantee that accounting materials are correct. It does not contain BankID codes, passwords, API secrets, or actual customer data.
Complete Table of Contents
| Document | Actual Function | Format |
|---|---|---|
| 01 Authorization Inventory | Separate inventory of Swedish Tax Agency representatives, bank authorizations, financial systems, and powers of attorney | DOCX/PDF |
| 02 SKV De-registration Basis | Prepare the e-service or official SKV 4804, document actual revocation | DOCX/PDF |
| 03 Bank and System Access | Action plan and post-check of banks, authorizations, API, and accounting/payroll systems | DOCX/PDF |
| 04 GDPR and Archiving | Return/deletion according to role and agreement, with separate review of statutory retention | DOCX/PDF |
| 05 Final Receipt and Deviations | Evidence of actually removed rights, open risks, and responsible decision | DOCX/PDF |
| 06 Swedish User Guide | Agency differences, step-by-step procedures, and practical scenario checks | DOCX/PDF |
| 07 English User Guide | Instructions in English; the main templates are in Swedish | DOCX/PDF |
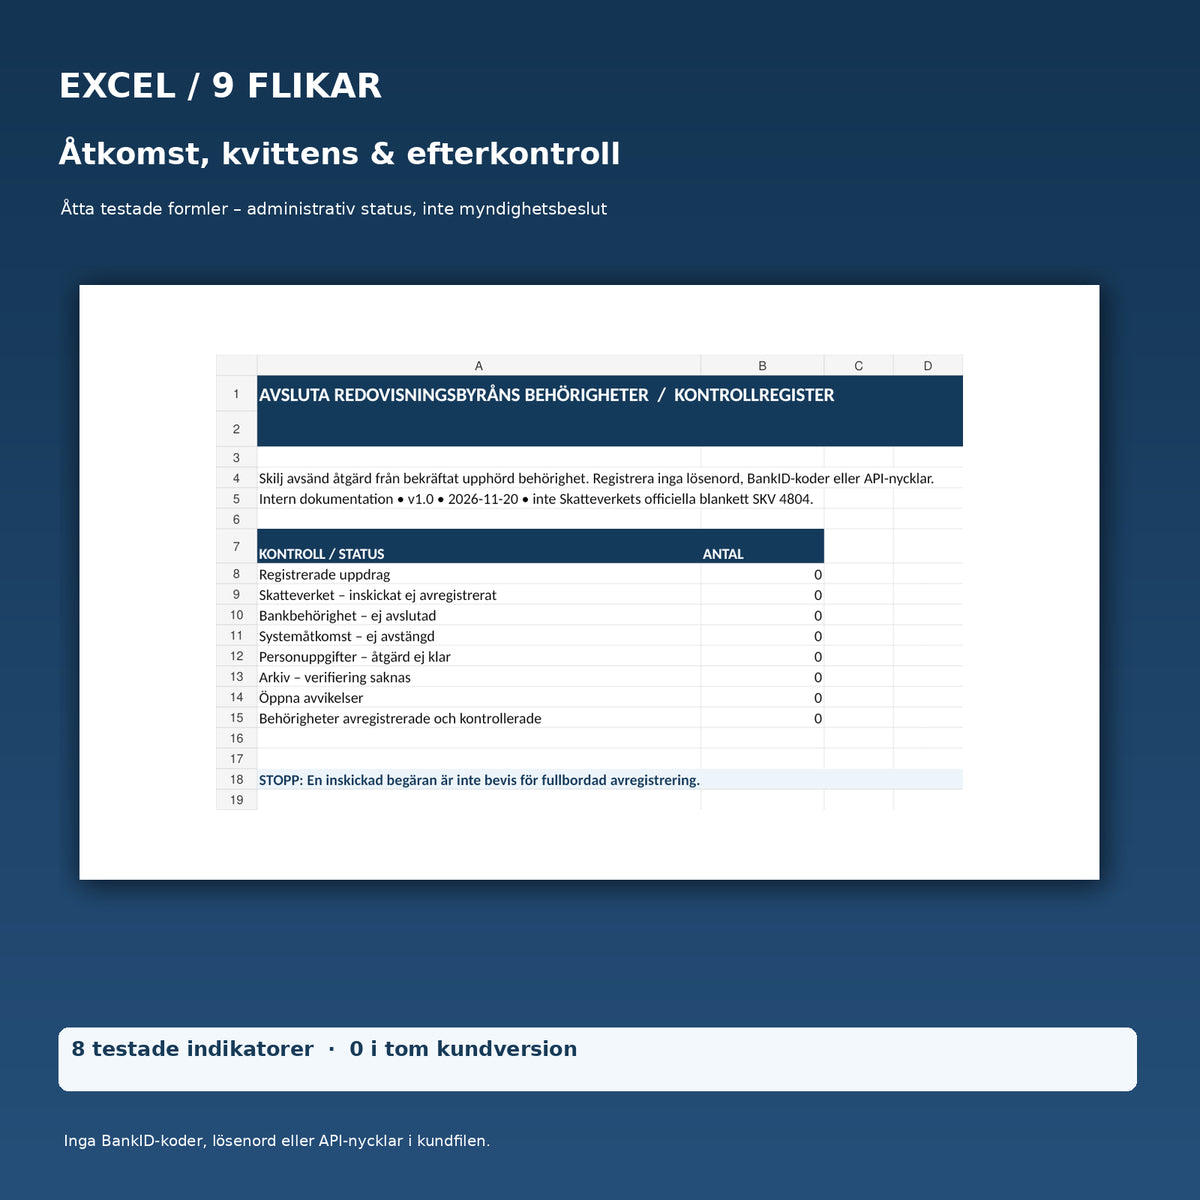
| 08 Excel Access Register | Nine tabs, eight tested formula indicators, and data-validated status fields | XLSX |
Step-by-Step Workflow
- Check the service agreement: define the last working day, already agreed authorizations, and who handles VAT, AGI, payroll, and tax returns during the transition.
- Inventory separately: tax representative status, read-only access to the tax account, VAT/employer declarations, bank powers of attorney, payroll systems, financial systems, API, and external integrations.
- Choose the correct agency path: Swedish Tax Agency Representatives and Authorizations or official form SKV 4804, where applicable. Check special instructions for sole traders and private individuals.
- Perform it yourself in the correct portal: our Word template prepares checkpoints but is never a substitute for the agency's submission.
- Remove other authorizations: use the bank's and each system provider's own de-registration/blocking procedures. Do not share BankID or password details.
- Check personal data and accounting: assess the actual role, data processor agreement, return/deletion, and retention of accounting information.
- Verify afterward: document the actual de-registration status and match the new authorized consultant before the next agency reporting. Keep deviations open until proof of verification is available.
Excel with Nine Tabs – What Works?
The workbook contains Overview, Assignment, Swedish Tax Agency, Bank, Systems, Personal Data, Archives, Deviations, and Read Me. Eight formula indicators show: number of registered assignments, submitted but not verified as terminated Swedish Tax Agency authorizations, active bank authorizations, active system accounts, open personal data actions, archives that have not yet been verified, open deviations, and verified removed Swedish Tax Agency authorizations.
Each indicator has been tested against realistic fictitious administrative conditions and showed the expected value of 1. After all test cases were cleared, the eight indicators showed 0. The formulas provide administrative counts, not agency decisions, automatic bank blocks, or legal proof of termination. Never enter passwords, personal identity numbers unnecessarily, or authentication secrets.
Legal and Practical Boundaries
Swedish Tax Agency: The company can remove a representative via the Representatives and Authorizations e-service or with SKV 4804 when the form is applicable. The Swedish Tax Agency expressly states that sole traders and private individuals should use the e-service instead of the form for certain removals of tax representative status and read-only access. The relevant form should always be obtained directly from the agency. Authorizations have different scopes – a revoked tax representative role does not mean the bank or accounting system is blocked.
GDPR: IMY's guidance on data processor agreements addresses GDPR Article 28.3 g, where deletion or return after the termination of a processor agreement is based on the data controller's choice, with statutory exceptions. The accounting firm is not automatically a processor for every piece of data; for example, its own customer due diligence may have a different legal basis.
Archiving: The Accounting Act (1999:1078) contains obligations to retain accounting information and the systems required for readability. The general rule is that materials are retained until the seventh year after the end of the calendar year in which the financial year ended. An ongoing change of accounting firm or a general deletion request does not override these obligations.
Frequently Asked Questions
Does the tax representative status disappear automatically when I terminate the accounting firm?
No, do not assume that. Check and de-register separately with the Swedish Tax Agency and actually save proof that the mandate has ceased.
Can I send the package's Word template as SKV 4804?
No. The package's working template is not the Swedish Tax Agency's official form and should never be described as such. Use the Swedish Tax Agency's current e-service or the official form when applicable.
What if the company is a sole proprietorship?
The Swedish Tax Agency specifically states that sole traders and private individuals should use the e-service for certain de-registrations instead of SKV 4804. Check the current matter and authorization type.
Is it enough that the Swedish Tax Agency has de-registered the consultant?
No. It does not say anything certain about bank authorizations, financial and payroll systems, private powers of attorney, or linked API accounts.
Can I request that the outgoing firm deletes all files?
Not without a legal review. The data processor's return/deletion obligations, the firm's own potential obligations, and the retention requirements of the Accounting Act must be considered separately.
Can Excel show that the authorization has been terminated?
Excel can only display the status that someone has entered. An actually de-registered and verified authorization requires proof from the correct portal or responsible party.
Are the English documents complete working templates?
No. Five working documents and Excel are in Swedish; a separate English User Guide is included.
Are the PDF versions interactively fillable?
No. Use DOCX for editing. PDF is searchable and printable.
Related Products – Choose the Right Step
If you need a broader handover plan for the entire assignment, including SIE and reconciliations, see Change of Accounting Firm & Handover Plan. If the task concerns the change of accounting software itself, see Change Accounting Software – SIE Export and Balance Check. For a new agreement with the accounting consultant, see Service Agreement for Financial Services. This product concerns the termination of the authorization itself and its verifiable audit trail.
Version, Sources, and Transparent Audit Status
Release 1.0, AI-assisted legal source check and technical file tests November 20, 2026. Primary sources: Swedish Tax Agency guidance on representatives, official SKV 4804, IMY on data processor agreements, and the Accounting Act.