Svenska Dokumentmallar
CSRD & ESRS Sustainability Reporting 2026/2027 – Swedish + English | Scope, Double Materiality, IRO & VSME Word/PDF/Excel
CSRD & ESRS Sustainability Reporting 2026/2027 – Swedish + English | Scope, Double Materiality, IRO & VSME Word/PDF/Excel
- File format
- DOCX, PDF, XLSX
- Document language
- Swedish
- Number of files
- 17
Digital download. No physical product is shipped.
Couldn't load pickup availability
About this template
CSRD & ESRS Sustainability Reporting 2026/2027 – complete 2-in-1 package in Swedish + English
A professional work and document package for companies, groups, and advisors who need to structure CSRD/ESRS scope, double materiality assessment, IRO register, disclosure index, value chain data, internal controls, and assurance readiness.
2-in-1: eight separate document templates are available in both Swedish and English. The package contains 16 DOCX + 16 PDF + an advanced Excel register – 33 delivery files in total.
The package is updated in accordance with Directive (EU) 2026/470, the new voluntary standard in Delegated Regulation (EU) 2026/1560, and the revised ESRS in Delegated Regulation (EU) 2026/1563. It clearly distinguishes between current EU law, upcoming entry into force, and Swedish implementation that is not yet finalized.
Included in this package
| Document | Swedish | English | Usage |
|---|---|---|---|
| Compliance plan & scope assessment | Yes | Yes | Scope, governance, reporting tracks, and ESRS version. |
| Double materiality assessment | Yes | Yes | Impact materiality + financial materiality. |
| IRO register & stakeholder process | Yes | Yes | Impacts, risks, opportunities, dependencies, and stakeholder evidence. |
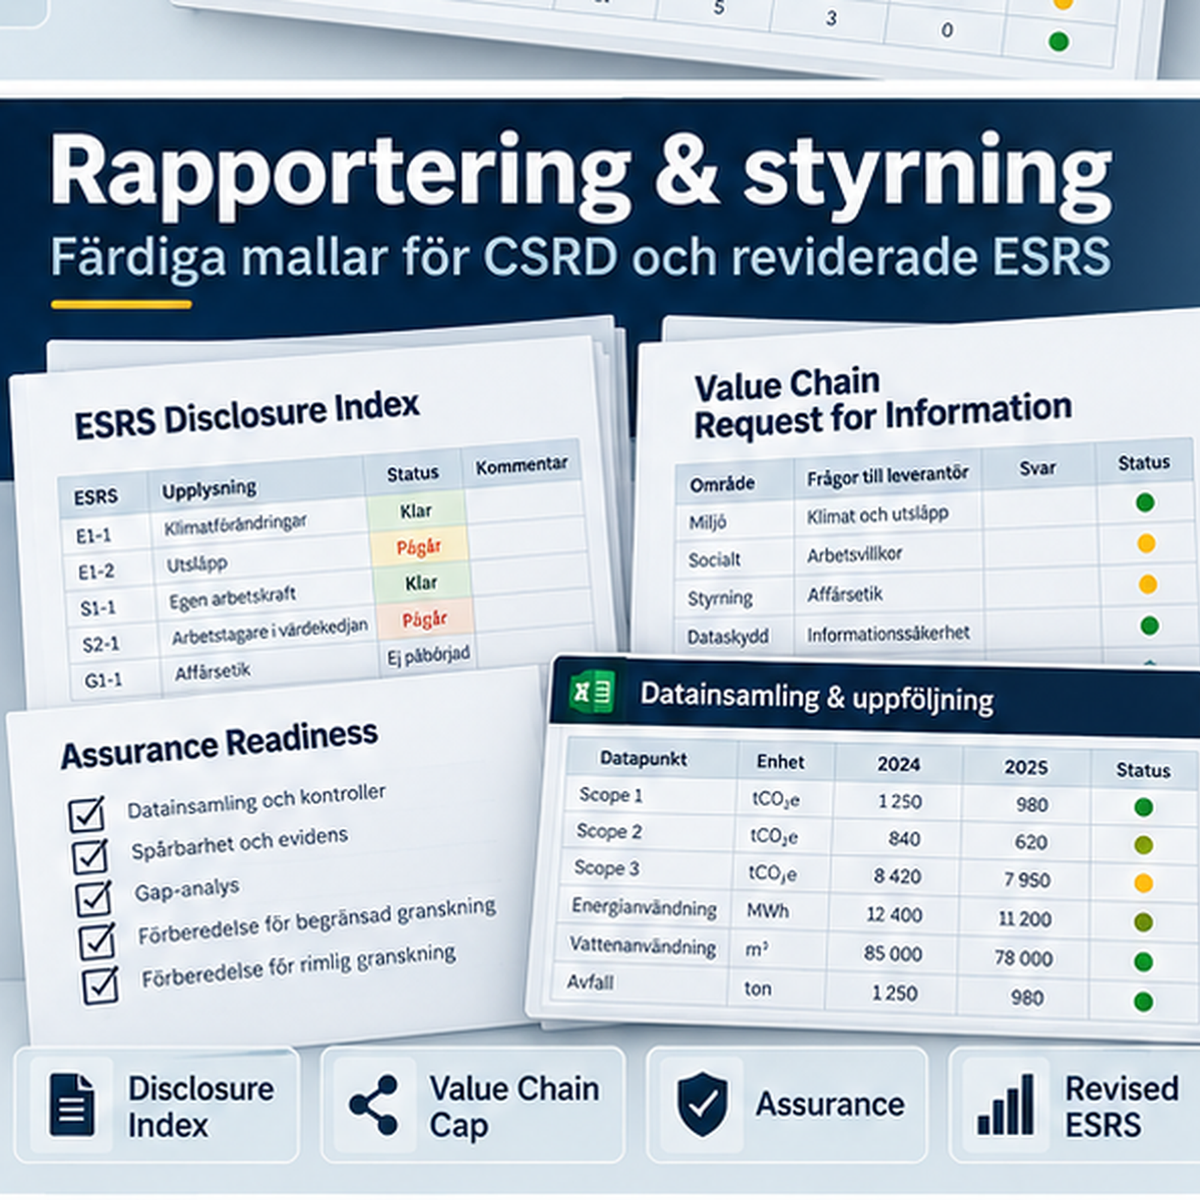
| ESRS report structure & Disclosure Index | Yes | Yes | Report structure, datapoint mapping, and status. |
| Value Chain Request & Self-Declaration | Yes | Yes | Proportionate information requirements and value-chain cap. |
| Data governance, controls & evidence | Yes | Yes | Data owners, methods, controls, estimates, and audit trail. |
| Assurance Readiness & Management Sign-off | Yes | Yes | Preparation for audit, issue log, and management representation. |
| Detailed user guide | Yes | Yes | Step-by-step for 2026/2027 and legal status. |
| CSRD & ESRS Compliance Register | Excel (XLSX) | Dashboard, scope, IRO, materiality, datapoints, value chain, controls, assurance, and deadlines. | |
Directive (EU) 2026/470 limits the EU scope to companies exceeding both 450 million euros in net turnover and 1,000 employees. In Sweden, implementation as of October 6, 2026, is still ongoing. SOU 2026:27 proposes over 1,000 employees and over 4.9 billion SEK in net turnover in each of the last two financial years. The package therefore marks the Swedish 4.9 billion SEK threshold as a proposal, not as final applicable law.
CSRD scope after Omnibus I
The new EU rule means that mandatory sustainability reporting under Articles 19a and 29a of the Accounting Directive is targeted at the largest companies and groups. The directive must be implemented nationally by March 19, 2027. The package's scope assessment therefore documents both the EU test and the current Swedish implementation status.
Revised ESRS 2026 – correct transition
The revised ESRS were published on September 21, 2026, as Delegated Regulation (EU) 2026/1563 and take effect on November 10, 2026. For financial years beginning in 2026, the regulation contains a transition option. For financial years beginning on January 1, 2027, or later, the revised ESRS are used by companies within scope.
The revised standards are shorter and more focused. The Commission states that the number of mandatory datapoints has been reduced by over 60 percent and the total number of datapoints by more than 70 percent. The package is therefore built around materiality, IRO, and traceable data governance – not an uncritical checklist of every datapoint.
Double materiality and IRO
The templates separate impact materiality from financial materiality and document IRO in a traceable manner. The assessment can be linked to stakeholder evidence, policies, actions, targets, metrics, financial planning, and control environment.
Voluntary standard and value-chain cap
Delegated Regulation (EU) 2026/1560 entered into force on September 24, 2026, and establishes a voluntary standard. The value chain cap applies to financial years beginning on January 1, 2027, or later, and limits what information CSRD reporters can demand from value chain companies with a maximum of 1,000 employees.
The package's Value Chain Request therefore starts with a protection assessment/self-declaration and is designed to request the minimum necessary information.
Excel dashboard for the entire reporting process
- Dashboard – IRO, materiality, datapoint gaps, value-chain requests, controls, assurance, and deadlines.
- Scope & Governance – reporting tracks, ESRS version, and responsibility.
- Materiality Topics and IRO Register.
- Disclosure Index and Datapoints.
- Value Chain, Controls, Assurance, and Stakeholders.
- Deadlines and Sources.
How to use the package
- Perform the scope assessment and document Swedish implementation status.
- Determine the reporting year and the correct ESRS version.
- Conduct double materiality and build the IRO register.
- Create the Disclosure Index and link material disclosures to data owners.
- Request value chain data proportionately and respect the value-chain cap.
- Document methods, estimates, evidence, and internal controls.
- Run assurance readiness and management sign-off before the final report.
Frequently asked questions
Are 450 million euros and 1,000 employees already Swedish law?
That is the new EU level under Directive (EU) 2026/470. Swedish implementation must be checked separately. As of October 6, 2026, SOU 2026:27 is still a proposal.
Are the revised ESRS already in effect on October 6, 2026?
No. EU 2026/1563 is published but takes effect on November 10, 2026.
Can companies outside the CSRD scope use the package?
Yes. The scope assessment and the voluntary reporting section can be used for proportionate ESG/sustainability reporting, customer requirements, or group reporting.
Are both Swedish and English included?
Yes. Eight documents are available in separate Swedish and English versions.
Is Excel included?
Yes. An operational XLSX register with a dashboard and follow-up is included.
Format and delivery
- 16 Word files + 16 PDF files + 1 Excel file = 33 files.
- Word (DOCX), PDF, and Excel (XLSX).
- Digital product – no physical goods are shipped.
- The documents are version-labeled for 2026/2027.
Legal basis and regulatory sources
- Directive (EU) 2026/470
- Delegated Regulation (EU) 2026/1560 – voluntary standard/value-chain cap
- Delegated Regulation (EU) 2026/1563 – revised ESRS
- European Commission – Corporate Sustainability Reporting
- SOU 2026:27 – Reliefs in sustainability reporting requirements