Svenska Dokumentmallar
Denied or closed bank account – appeal, KYC and ARN | Word/PDF/Excel
Denied or closed bank account – appeal, KYC and ARN | Word/PDF/Excel
- File format
- DOCX, PDF, XLSX
- Document language
- Five Swedish work templates Swedish user guide separate English User Guide and Swedish Excel register
- Number of files
- 7
Digital download. No physical product is shipped.
Couldn't load pickup availability
About this template
Has the bank refused you an account, requested extensive customer due diligence, or terminated your existing payment account? This specialized document package for Swedish consumers helps you draft a clear application for a payment account with basic features, respond securely to the bank's questions, request a review of a refusal or termination, and compile a factual supporting document for ARN if the dispute remains unresolved.
Important before purchase: a right to a payment account with basic features is not a general right to receive BankID, Swish, a credit card, a mortgage, or a business account. Banks may refuse or terminate payment accounts when the special conditions of the law are met, including in certain cases of money laundering risk. The package does not guarantee a specific outcome.
What does the package contain?
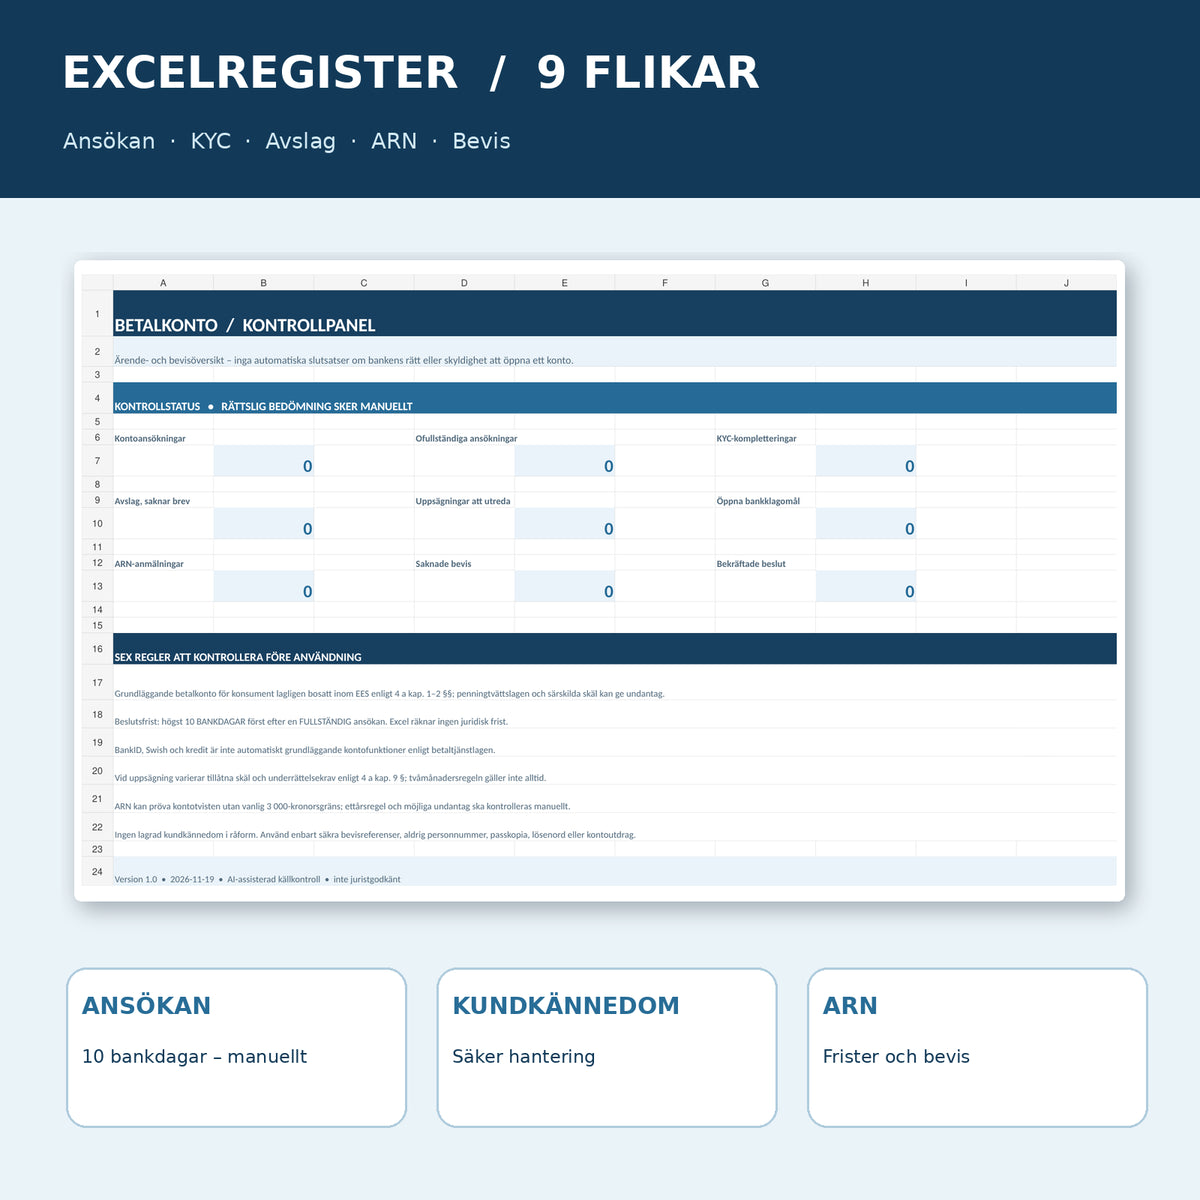
15 files: five Swedish working documents, a Swedish user guide and a separate English user guide, all in editable Word (DOCX) and corresponding searchable and printable PDF format. In addition, a Swedish Excel workbook (XLSX) with nine tabs and 709 administrative formula cells. There are seven different text documents in two file formats, not fourteen different legal forms. The PDF files lack interactive form fields; use the Word version to edit the text. The files work in Microsoft Office and compatible programs. The delivery format is a digital ZIP.
01. Package contents
Five Swedish working templates: (1) application for a payment account, (2) request for clarification of customer due diligence and secure completion, (3) complaint after refusal, (4) objection to termination and (5) ARN supporting document. Also a Swedish user guide and English User Guide in Word/PDF, as well as an Excel register with nine tabs. 7 DOCX + 7 searchable PDFs + 1 XLSX = 15 files.
02. What the files contain
Specific letter texts and fields for the bank, account application ID, date of a complete application, the bank's request for additional information, secure submission channel, written decisions, complaint references, grounds for termination according to Chapter 4 a, Section 9 of the Payment Services Act, ARN claim, document list and secure evidence ID. Excel flags deficiencies such as INVESTIGATE COMPLETENESS, MISSING SECURE CHANNEL and CHECK ARN DEADLINE – not the bank's legal liability or right to a specific account.
Do you have a right to a bank account?
According to Chapter 4 a, Section 1 of the Payment Services Act (2010:751), a credit institution or a branch of a foreign credit institution in Sweden shall, as a general rule, offer consumers who are lawfully resident within the EEA a payment account with such basic features as the institution provides to other consumers. Exceptions apply if this conflicts with the Anti-Money Laundering Act (2017:630) or if special reasons exist.
Basic features according to Chapter 4 a, Section 2 include opening and maintaining an account, depositing and withdrawing money, and making certain payments by debit card and via transfer. BankID, Swish, credit, and loan products are not automatically part of the statutory right. A person who owns their own business cannot simply use the consumer provision to demand a business account.
When must the bank respond – ten banking days?
The bank shall process an application for a payment account with basic features promptly and make a decision no later than ten banking days after a complete application has been received, according to Chapter 4 a, Section 3. The deadline cannot always be calculated from the first contact, a booked meeting, or an application where necessary customer due diligence information is still missing. Therefore, there are special fields for completion, secure receipt confirmation, and when the bank considers the application complete.
If the bank refuses the application, it must immediately provide a free written notice with information about complaints and the appeals process. If possible, the reasons shall be stated. This does not mean that the bank always may or can disclose all internal money laundering assessments.
Customer due diligence and money laundering – what can you do?
Banks must understand the customer's identity, the purpose of the account, and the transactions. The Swedish Financial Supervisory Authority's guidance describes that risk management must be individual and that high risk does not always in itself give reason to refuse an account. At the same time, the bank may be prevented from opening or maintaining the account if it cannot obtain sufficient customer due diligence or manage unacceptable risks.
Document 02 helps you request a clear list of what information is missing and which secure channel should be used. It is not a way to bypass the bank's legitimate controls. Never put copies of passports, full account numbers, personal identity numbers, passwords, codes, or sensitive account statements directly in the open Excel register.
Terminated account – does a two-month notice period always apply?
No. Chapter 4 a, Section 9 of the Payment Services Act states certain grounds for terminating a payment account with basic features. For example, after 24 months of inactivity and certain special reasons, at least two months' written notice is required. Certain other grounds may take effect immediately, such as intentional illegal use or providing grossly false information when opening the account. The real reason for the bank's decision must be checked. A block on a payment instrument or a separate BankID service is not automatically a termination of the entire payment account.
All files – exact delivery contents
| No. | Document | What you can do | Format |
|---|---|---|---|
| 01 | Application for a basic payment account | Written consumer application with a request for confirmation when the application is complete. | DOCX + PDF |
| 02 | Customer due diligence – completion via secure channel | Request clarification of the bank's KYC questions and securely document the submission materials. | DOCX + PDF |
| 03 | Complaint after refusal | Specific request for a new individual review and a written decision from the complaint handler. | DOCX + PDF |
| 04 | Objection to a terminated payment account | Request that the bank clarify which termination ground and notice rule was applied. | DOCX + PDF |
| 05 | ARN application – supporting document | Factual supporting document for ARN's official bank form, with complaint history and evidence ID. | DOCX + PDF |
| 06 | Swedish user guide | Decision tree, legal basis, secure data routines, and practical steps. | DOCX + PDF |
| 07 | English User Guide | English instructions for the five Swedish working forms and Swedish Excel workbook. | DOCX + PDF |
| 08 | Excel case register | Nine tabs for applications, KYC, refusals, terminations, bank complaints, ARN, and evidence. | XLSX |
Excel – nine tabs with control formulas
Overview · Applications · KYC materials · Refusals · Terminations · Bank complaints · ARN cases · Evidence · Read me. Excel counts the number of applications, administrative documentation deficiencies, KYC completions, missing decision letters, and open bank complaints. It helps you follow an actual chain of evidence between documents, complaints, and a potential ARN case.
Tested fictional cases: an incomplete account application triggered the signal INVESTIGATE COMPLETENESS; a complete and confirmed application gave CHECK 10 BANKING DAYS; a KYC request without a confirmed secure channel gave MISSING SECURE CHANNEL; a termination with a stated reason gave CHECK NOTICE. An ARN application without a selected official form gave OFFICIAL FORM. These signals are administrative, not legal conclusions. The test data has been removed from the consumer version.
How to use the templates
- Determine which situation you are in: new application, refused account, terminated account, or a limited additional service.
- Keep the bank's actual notice: save the date, original letter, and secure evidence reference.
- For a new application: use document 01 and request confirmation of what documents the bank needs for a complete application.
- For KYC completion: use document 02, provide information through the bank's secure channel, and save the receipt confirmation.
- For refusal: use document 03 and complain to the bank's complaint handler with factual and verifiable supporting materials.
- For termination: use document 04 to request the applied ground and check which notice period is required.
- If the dispute is not resolved: use document 05 as a supporting document for ARN's official bank complaint. Check deadlines and the bank's previous answers.
ARN and FI – what is the difference?
ARN can review disputes about the right to a basic payment account. The usual value limit of SEK 3,000 does not apply to this account category. A complaint normally needs to have been submitted within one year from the consumer's first complaint to the bank, with special exceptions when the bank's internal complaint handling has been ongoing for a long time. Read ARN's current instructions and use its official forms.
The Swedish Financial Supervisory Authority (FI) is responsible for supervising banks. FI's information is valuable for understanding the rules, but a supervisory signal to FI is not the same as FI reviewing your private dispute or automatically opening an account for you.
Who can benefit from the package?
Newly arrived consumer within the EEA: has legal residence but needs to clarify the bank's identity and customer due diligence requirements before the application can be complete.
Person with a payment default: wants to know if that circumstance can really justify a refusal of basic account functionality; FI emphasizes that a payment default or late credit payment is not in itself a special reason.
Consumer whose account has been terminated: needs a timeline of the bank's written notice and the ground the bank invokes, without automatically assuming that two months always apply.
Customer with an ongoing bank dispute: wants to attach a structured chronology, written complaints, and evidence in an ARN application without unnecessarily sharing confidential bank information.
What is not included?
No bank contact on your behalf, no guaranteed decision, no digital account opening, no BankID or Swish connection, no credit check, no AML risk assessment for the bank, no legal services, and no automatic authority notification. The documents must not be used to provide false information or withhold necessary customer due diligence information. A secure and truthful KYC process is a prerequisite for the legal review.
Related document templates
If the dispute concerns an unauthorized direct debit withdrawal rather than the bank refusing an account, Incorrect direct debit withdrawal – refund and stop request may be more suitable. For a more general consumer dispute, there is ARN application – consumer dispute and evidence. This product is specialized for the consumer's statutory access to a basic payment account and the bank's KYC/termination decision.
Frequently Asked Questions (FAQ)
Do I always have a right to get a bank account?
No. Consumers lawfully resident within the EEA have, as a general rule, a right to a basic payment account, but the bank can refuse if anti-money laundering legislation prevents it or if special reasons exist.
Does the bank always have ten days?
Decisions must be made no later than ten banking days after a complete application has been received. It is not always the same date as the first contact.
Can the bank refuse me because of a payment default?
FI explains that a payment default or late credit payments in themselves do not constitute special reasons to refuse a basic payment account. An individual assessment of other circumstances must still be made.
Must the bank give me BankID and Swish?
No. Those services are not automatically basic payment account features according to Chapter 4 a of the Payment Services Act.
Must the bank always give me a two-month notice period?
No. Chapter 4 a, Section 9 contains different grounds and time rules. Certain grounds require at least two months' notice while others can take effect immediately.
What do I do if the bank requires ID or information about the origin of the money?
Request clarification of what is needed and provide truthful information through the bank's secure channel. The bank is obliged to follow anti-money laundering rules and may otherwise be prevented from offering the account.
Can ARN review the dispute without me claiming 3,000 kronor?
Yes. ARN's usual value limit does not apply to disputes about access to a payment account according to Chapter 4 a of the Payment Services Act. Other review conditions and deadlines still apply.
Is Excel an automatic legal prescription calculator?
No. It shows administrative reminders about decisions, evidence, and manual deadline checks; it does not calculate binding complaint or ARN deadlines.
Can I send this package directly to the bank without changes?
No. Choose the document that corresponds to your case, fill in only real information, check the bank's address, and send relevant KYC documents separately through a verified secure channel.
Are the files fillable in English?
The five working templates and Excel are in Swedish. English User Guide is included. The Word files can be edited; the PDF files are searchable and printable but lack interactive form fields.
Legal sources and review status
Product version 1.0 · AI-assisted source check November 19, 2026. Primary source the Payment Services Act (2010:751), especially Chapter 4 a, Sections 1–3 and 9. For exceptions and KYC see the Anti-Money Laundering and Terrorist Financing Act (2017:630), FI's rights information and FI's application guidance. ARN's rules: Bank disputes – ARN. No independent lawyer has reviewed or approved the documents, and neither the bank nor any authority has certified the package. Check the current legal situation and the conditions in your individual case.