Svenska Dokumentmallar
Service agreement for accounting services – Word/PDF + GDPR & guides
Service agreement for accounting services – Word/PDF + GDPR & guides
- File format
- DOCX, PDF
- Document language
- Swedish (master version) + English (reference according to Swedish law)
- Number of files
- 32
Digital download. No physical product is shipped.
Couldn't load pickup availability
About this template
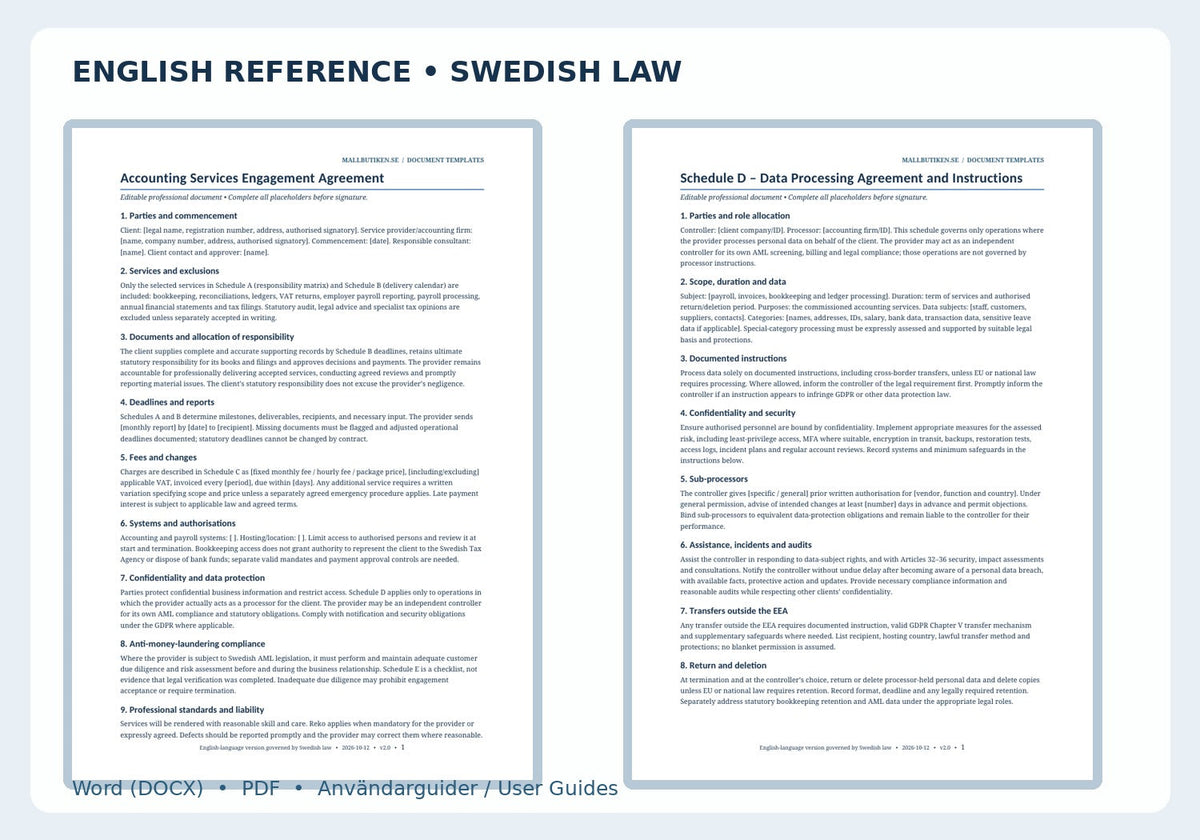
Engagement agreement for accounting services – professional Word/PDF template for accounting firms and corporate clients. Regulate day-to-day bookkeeping, payroll, VAT, reconciliations, year-end closing, reporting, remuneration, and liability with a clear engagement agreement. The package also includes concrete appendices for division of labor, delivery schedules, GDPR, KYC (Know Your Customer), and handover – with Swedish master documents and English reference versions based on Swedish law.
The client retains overall responsibility for their bookkeeping and statutory reporting, even when an accounting firm is engaged. At the same time, the firm is responsible for the performance of the duties it has undertaken. FAR's Reko is a professional standard that must be followed by those subject to it – a general template is not automatically Reko-certified. A data processing agreement is required where the firm actually processes personal data as a processor on behalf of the client. KYC procedures in accordance with the Anti-Money Laundering Act may need to be performed prior to the start of the assignment.
Legally reviewed: October 12, 2026 · Document version 2.0 · Swedish law.
What is included in the package? 32 files
| Document type | Content and function |
|---|---|
| 1. Engagement agreement | Parties, scope, source documents, deadlines, fees, systems, powers of attorney, confidentiality, liability, termination, and disputes. |
| 2. Appendix A – Responsibility matrix | Select bookkeeping, payroll, VAT, AGI, year-end accounts, and tax returns; specify who performs, checks, and approves each step. |
| 3. Appendix B – Delivery calendar | Client submission deadlines, firm delivery dates, report recipients, and procedures for missing documents. |
| 4. Appendix C – Fees | Fixed price or hourly rate, VAT, invoicing, licenses, and written approval of additional work. |
| 5. Appendix D – Data processing agreement | Roles, instructions, security, sub-processors, incidents, third-country transfers, and return of data per Article 28 GDPR. |
| 6. Appendix E – KYC (Know Your Customer) | Checklist for applicable AML obligations. Does not replace identity verification or the firm's internal risk assessment. |
| 7. Appendix F – Handover | Trial balance, ledgers, open matters, export formats, system access, and responsibilities when changing firms. |
| 8. User guide | Twelve steps from engagement review to signature, reconciliation, GDPR, completion, and archiving. |
All eight document types are available in Swedish and English, and each language version is provided in editable DOCX and searchable A4-PDF: a total of 16 Word files and 16 PDF files. English-language versions governed by Swedish law. The file package is an editable template; no client data or actually performed KYC measures are included.
Digital delivery: The 2027 ZIP package is already attached to this product in Shopify Digital Products and is currently the only listed download file for this variant.
What is an engagement agreement for accounting services?
It is an agreement between the client and the accounting firm that specifies exactly which accounting services are to be performed, what source documents the client provides, who has authorization to review and approve, when reports are to be delivered, and the cost of the services. Such an agreement is particularly valuable when outsourcing day-to-day bookkeeping, payroll, VAT, employer tax returns, year-end accounts, and delimited financial administration.
Who is responsible for bookkeeping and reporting?
According to the Bookkeeping Act and company law principles, the entity with the bookkeeping obligation and its responsible representatives retain their overall obligations. Responsibility cannot be contracted away simply by engaging an external accounting consultant. The firm, however, may have its own contractual and professional responsibility for professional execution, control, and reporting of material discrepancies. Appendix A is used to distinguish between source documents, registration, review, approval, and submission to authorities.
Reko and requirements for a professional engagement agreement
Reko – Swedish standard for accounting and payroll services is used by authorized FAR consultants and other entities covered by the standard. It contains fundamental requirements regarding, among other things, engagement agreements, understanding of the client's business, planning, execution, reporting, and closing. The template is designed with these topics in mind, but does not constitute a guarantee that a firm meets all requirements of Reko. Firms subject to the standard must check the full, current standard and quality procedures themselves.
Deadlines for bookkeeping, VAT, payroll, and year-end accounts
An accounting firm depends on the client delivering the correct source material on time. Appendix B therefore specifies separate deadlines for the client's material and the firm's work, including contact persons, discrepancy handling, and report recipients. Agreed internal deadlines do not override the statutory deadlines of the Swedish Tax Agency or the Swedish Companies Registration Office. A firm that is to submit tax returns or represent the company also needs valid and current authorization; access to the accounting system is not the same as a power of attorney to represent the client.
Fixed price, hourly rate, and extra work
Appendix C allows the parties to specify a fixed monthly fee, hourly rate, or package price, applicable VAT, invoicing intervals, software licenses, and the agreed price for additional services. Examples of extra work include late source documents, corrections, complex year-end closing issues, or assignments added after the start. A clear ordering procedure reduces the risk of unspecified additional costs. The agreement is not intended to automatically authorize all future additional work.
GDPR and data processing agreements for accounting firms
When the firm processes, for example, employee payroll data or invoice personal data on behalf of the client, the client may be the data controller and the firm the data processor. In such cases, the processing of personal data needs to be regulated in accordance with Article 28 of the GDPR. Appendix D includes, among other things, rules on documented instructions, authorization, confidentiality, security, sub-processors, incidents, auditing, and return or deletion. It also includes a concrete instruction appendix where the client enters systems, data types, data subjects, storage country, and security measures.
The firm is not automatically a processor for all data. KYC measures to comply with anti-money laundering legislation and the administration of the firm's own operations may involve independent data controller responsibilities. If you need a standalone and more general document, there is also the Mallbutiken separate data processing agreement.
Anti-money laundering, KYC, and risk assessment
An accounting firm subject to the Anti-Money Laundering Act needs, among other things, to identify the client, verify authorized representatives and the beneficial owner, understand the purpose of the business relationship, and conduct a risk-based KYC assessment. There may be requirements for enhanced due diligence and ongoing monitoring. Appendix E assists with the documentation structure but does not imply that the client has been vetted or that the assignment may be accepted. Insufficient KYC may mean that an assignment cannot be initiated or continued.
What happens when the collaboration ends?
When changing accounting firms, a handover of the trial balance, general ledger, vouchers, subsidiary ledgers, payroll and tax data, as well as open items and authorizations is required. Appendix F contains a practical handover list. Accounting information must be preserved in accordance with the Bookkeeping Act, normally until the end of the seventh year after the end of the calendar year in which the financial year ended. The agreement must not be used to block access to the client's bookkeeping due to a payment dispute.
How to use the template
- Perform engagement review and KYC before accepting work.
- Identify parties, contact persons, and authorized signatories in the main agreement.
- Fill in the responsibility matrix with precisely ordered services and specific exceptions.
- Fill in the delivery calendar based on actual submission and reporting dates.
- Determine remuneration as well as ordering and approval procedures for extra work.
- Clarify GDPR roles and supplement with processing agreements and written instructions when needed.
- Document systems, access, and powers of attorney as well as separate payment authorizations.
- Establish a closing and handover procedure so that material can be preserved and transferred.
- Sign applicable documents and store the agreed version securely.
- Follow up on the assignment regularly when services, regulations, data processing, or the parties' situation change.
When is a standard template not suitable?
Assignments involving consolidated financial statements, international taxation, extensive payroll outsourcing, auditing, financial supervision, complicated personal data transfers, notes according to the Anti-Money Laundering Act, extensive outsourcing of approval functions, or disputes should be reviewed specifically by a relevant specialist. An engagement agreement is not an audit agreement or a power of attorney for the Swedish Tax Agency or the bank.
Common questions
Does an accounting firm need a written engagement agreement?
A written engagement agreement is good professional practice and a requirement within relevant Reko applications. The content of the agreement should reflect the services actually performed.
Does the client's responsibility for bookkeeping disappear when accounting is outsourced?
No. The client retains their overall statutory responsibility. At the same time, the firm has responsibility for its own accepted assignment according to the agreement and applicable law.
Is a data processing agreement included?
Yes, a separate editable GDPR data processing agreement with an instruction appendix is included in Swedish and English. It is used where the firm actually has the role of processor and should be adapted to the specific processing of personal data.
Can the template be used by a non-authorized accounting consultant?
Yes, as a general contractual basis. However, the firm may not claim to be FAR-authorized or compliant with Reko solely because it uses this template.
Are KYC documents included?
Yes, a specific checklist is included. It does not replace actual client identification, risk assessment, verification of the beneficial owner, or other regulatory requirements.
How many files do I get?
The new edition contains 32 files: 16 DOCX and 16 PDF. It needs to be connected to Digital Products by the store owner before it is the file version actually delivered upon purchase.
Does the English version apply to UK or US law?
No. It is written in English as a reference for assignments governed by Swedish law, not for UK or US jurisdictions.
Legal basis and sources
- Bookkeeping Act (1999:1078)
- Anti-Money Laundering Act (2017:630)
- IMY – Data processing agreements and Article 28
- FAR – Reko and accounting assignments
- Swedish Companies Registration Office – responsibility when the company engages external help
- Swedish Tax Agency – bookkeeping responsibility
Document version 2.0 · Reviewed October 12, 2026. The material is a general documentation aid in accordance with Swedish law and not individual legal, tax, or data protection advice. The parties must assess their actual assignments and regulatory requirements before use. The 2027 ZIP is already linked to the product's digital delivery.