About this template
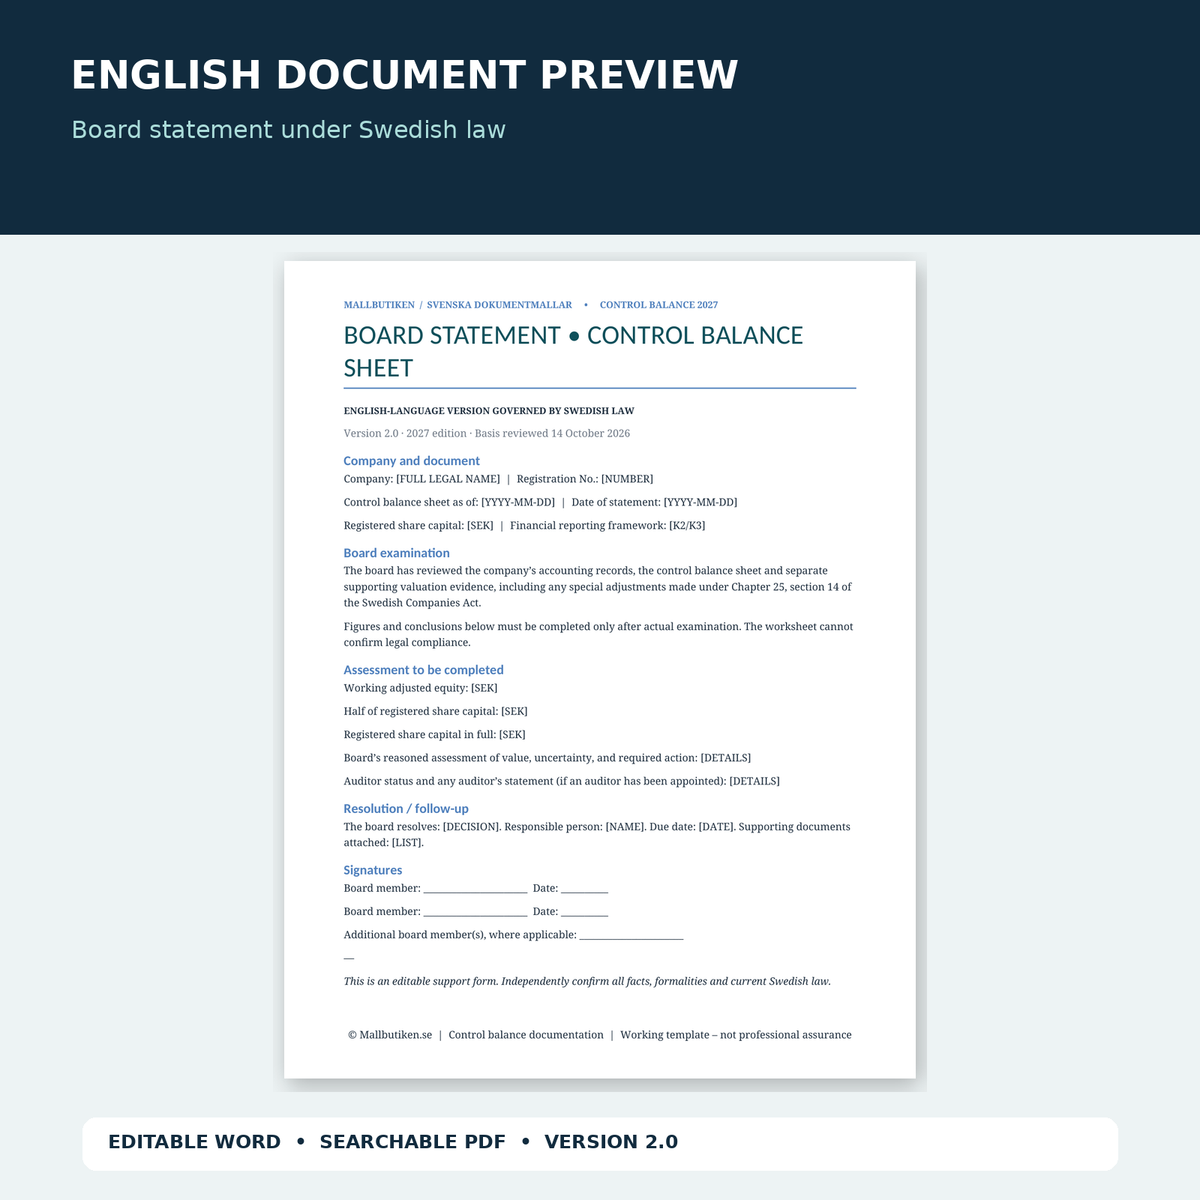
Prepare a structured control balance sheet (kontrollbalansräkning) for a Swedish limited company under Swedish law. This English-first working template supports board documentation, separate valuation adjustments and a transparent calculation of equity relative to registered share capital. It does not determine compliance or replace an accountant, an elected auditor or legal advice.
What's included / What's included
2027 upgrade package prepared: 29 files – 1 XLSX, 14 editable DOCX and 14 PDF; 7 English and 7 Swedish Word/PDF documents.
- Excel control balance model with 11 sheets
- Board statement and valuation adjustment records
- First control meeting notice and minutes
- Second control meeting minutes and board checklists
- Detailed user guides in English and Swedish
Delivery transparency: The 2027 ZIP is prepared but has not yet been attached to this Shopify product variant. Automatic delivery currently remains the original Control_Balance_Sheet_Template_EN_v2.xlsx. The new files become part of the automatic customer delivery only after the separate ZIP is uploaded and linked in Digital Products.
What the files do / What the files do
Excel: company inputs, assets and provisions/liabilities, ordinary accounting figures, separately recorded proposed adjustments, untaxed-reserve allocation, linked calculations of residual equity, capital comparison, completeness flags, evidence log and board-action tracker. Warnings indicate areas requiring human review.
Word/PDF: customizable board record, adjustment justifications and source documentation, meeting notices and minutes, procedural checklists, bilingual detailed walk-throughs including a worked example, auditor considerations and official references.
Important limitations: Valuations and reserves require individual assessments; the workbook cannot confirm legality, approve an auditor's review, establish statutory deadlines or remove directors' potential liability.
Who should use this Swedish-law template?
Directors, business owners, finance managers and accounting advisers working with Swedish AB companies. English is the principal language; Swedish documents are supplied as references in the planned expanded edition. This is not a UK or US company-law template.
Key legal guidance
Under Chapter 25, section 13 of the Swedish Companies Act (2005:551), the board must act without delay when there is reason to assume adjusted equity is below half of the registered share capital, or when qualifying enforcement reveals insufficient assets. Section 14 governs permitted adjustments and requires untaxed reserves to be split into equity and deferred tax. If the company has an elected auditor, the auditor reviews the control balance sheet. First and second control meetings and any liquidation application must follow the requirements of sections 15–17.
The statutory comparison at a second control meeting generally concerns restoration of full registered capital, not only 50%. Board signatures, source evidence and possible professional review remain necessary.
How to use the template
- Check registered share capital, bookkeeping completeness, financial reporting framework and the relevant valuation date.
- Record assets, liabilities and individual legally supported adjustments; keep written evidence.
- Check the working equity and capital comparisons; evaluate whether the workbook's completeness flags indicate missing data.
- Prepare board and meeting records tailored to the company's actual facts and applicable procedures.
- Archive signed documents, accounting evidence and an auditor's statement when applicable.
Read more on Mallbutiken
See our guide to when a control balance sheet is required, valuation of balance-sheet items, and K2/K3 differences. Browse control balance templates.
Frequently asked questions
Does the Excel file determine whether my company is legally solvent?
No. It supplies linked calculations and warnings, not a legal or auditor conclusion.
Does every Swedish company need an auditor for a control balance sheet?
A company with an elected auditor must use that auditor for the statutory review. Bolagsverket explains that a company lawfully without an elected auditor need not automatically engage one just to prepare this document.
What if equity is below half the registered share capital?
The board must evaluate its immediate duties, including the first control meeting. Formal assessment depends on the facts and the statutory process.
Are all 29 new files available as an automatic download now?
No. The original XLSX remains connected. The separately produced 2027 ZIP must be manually added in Digital Products before it is delivered with purchase.
Official sources and limitations
Swedish Companies Act, Chapter 25; Bolagsverket control balance guidance; Swedish Accounting Standards Board (BFN). Checked 14 October 2026 for this 2027 edition. The templates have not been certified or externally reviewed by an attorney. Seek individual advice where valuations, deadlines, audit duties, insolvency or liability are in dispute.