Om dokumentmallen
Deed of Gift for Swedish Real Property – English Word/PDF template under Swedish law. An editable English-first document package for documenting a straightforward gift of an existing Swedish property (fastighet) or a clearly defined undivided ownership share. It includes an English deed, a step-by-step English user guide, a Swedish reference deed (gåvobrev för fastighet) and a Swedish guide.
The documents are designed around Swedish real-property formalities, not UK conveyancing or US real-estate law. They must be completed for the actual parties and property. The English wording does not remove requirements for Swedish official property identification, wet-ink signatures, witnessed donor signature, required consents or land registration.
This is a general drafting and documentation aid for a genuine, uncompensated gift of an existing registered property or undivided share. Real-property transfers are subject to strict requirements under Chapter 4 of the Swedish Land Code (Jordabalken), with additional land-registration and family-law rules. Not a guarantee of title transfer or registration.
What's included?
| Document | Purpose |
|---|---|
| English Deed of Gift – Real Property | Identifies donor, recipient, official property designation, fractional share, express transfer, optional inheritance and separate-property instructions, signatures, witnesses and applicable consent. |
| English User Guide | Detailed preparation, clause-by-clause guidance, land registration, consent, stamp duty and post-signing checklist. |
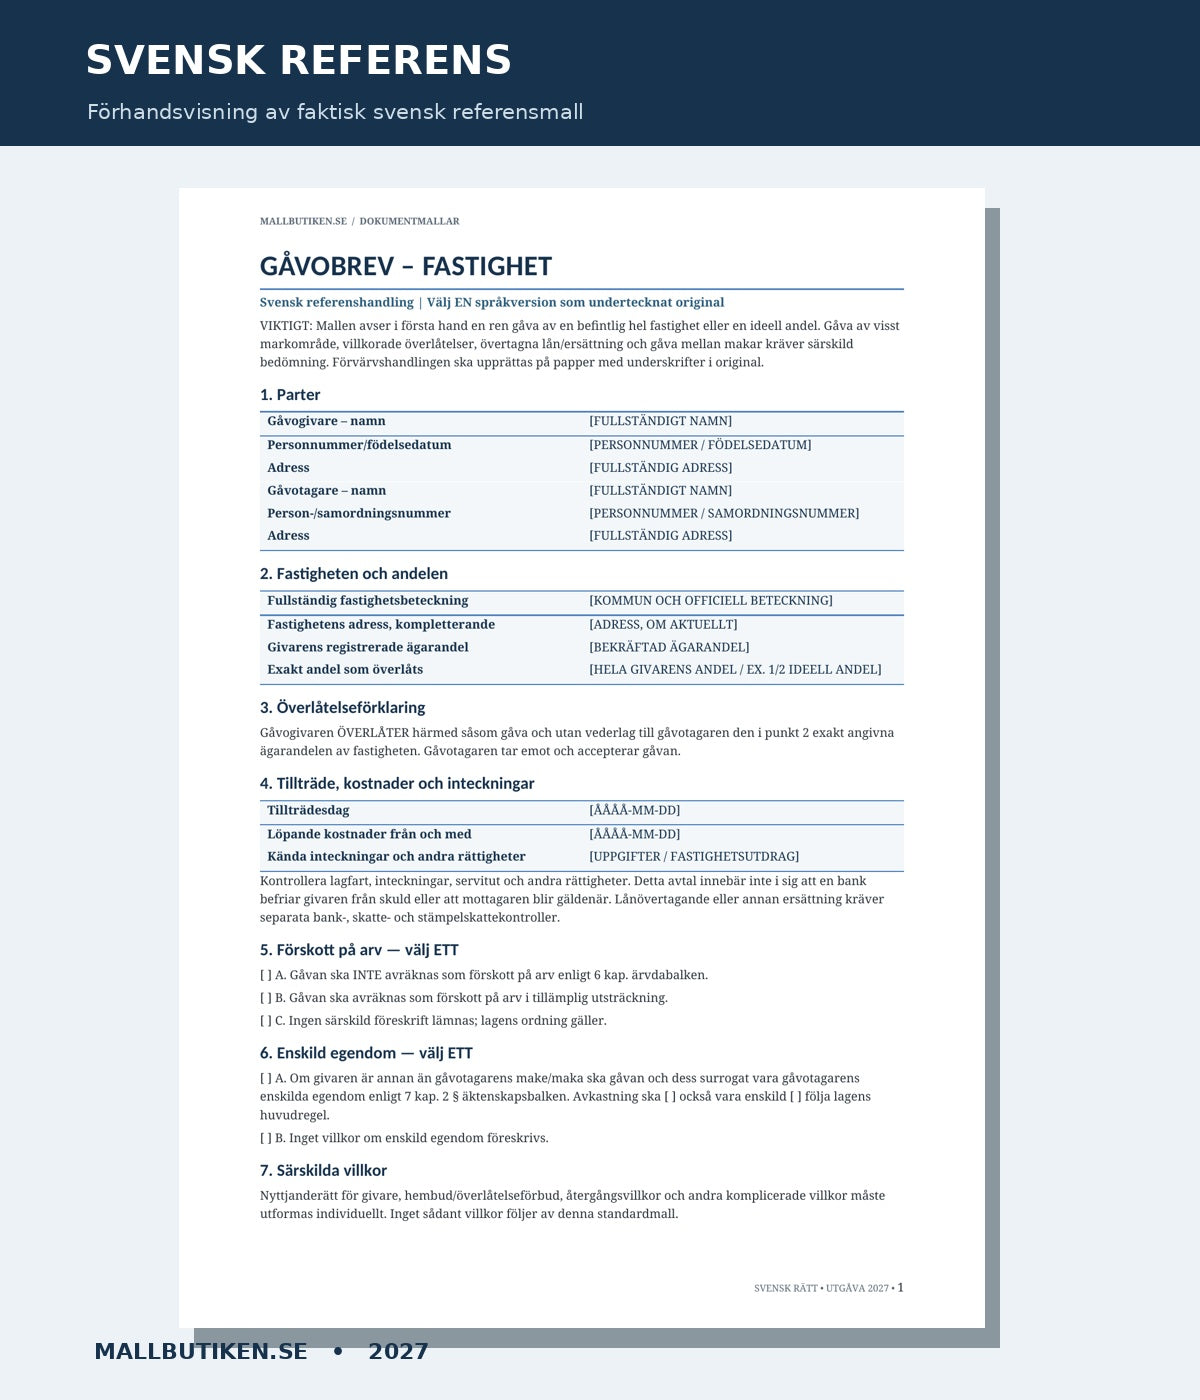
| Swedish reference deed | Gåvobrev – fastighet, designed to assist Swedish-language review, using the same underlying Swedish legal setting. |
| Swedish User Guide | Svensk användarguide med anvisningar om formkrav, lagfart, medgivanden och skatt. |
8 customer files: each of the four documents is delivered as an editable DOCX and a searchable A4 PDF. The new 2027 ZIP must be manually connected to the product's digital delivery by the shop owner; previously attached originals are retained.
What is a Swedish real-property deed of gift?
A deed of gift (gåvobrev) is the legal acquisition document by which the donor transfers specific Swedish real property or a specific ownership share to the recipient without the standard form's requiring any price or consideration. The deed must clearly identify the property by its full official cadastral designation (fastighetsbeteckning) and identify exactly what fraction is being transferred. A street address alone is insufficient.
Swedish legal requirements you must understand
Written deed and both parties' signatures
Chapter 4, Section 29 of the Swedish Land Code applies key provisions on transfers of property, including Section 1, to gifts. The deed must be in writing and contain the relevant parties' signatures, property identification and a clear declaration of the gift. Lantmäteriet's registration guidance also requires two people witnessing the donor's signature. Do not confuse that requirement with a universal rule that every gift of any property always needs witnesses.
Paper original versus digital application
The land-registration application can be submitted digitally, but Lantmäteriet does not accept an acquisition deed bearing only electronic signatures as the basis for registering ownership. Complete the deed in Word, print it, sign the original physically and keep it safe. Verify with Lantmäteriet whether an English-language acquisition deed is accepted and whether a Swedish translation is needed before signing. The included Swedish file is a reference; do not sign both language versions as two independent transfers.
Land registration (lagfart) within three months
The recipient must apply for registration of ownership with Lantmäteriet within three months after acquiring the property. Supporting documentation may include the original signed deed, spousal or cohabitant consent, and any documents demonstrating fulfillment of special conditions. For acquisitions from 1 July 2026, strengthened identification requirements mean recipients applying for registration need an applicable Swedish personal identity number, coordination number or organization number. Foreign recipients should check the practical requirements in advance.
Spousal consent and gifts between spouses
A donor who is married, previously married or transferring the couple's shared home may need written consent from a current or former spouse. Cohabitation circumstances may also require review. For a gift of Swedish real property between spouses, register the deed with Skatteverket's marriage register first, then submit the registered original with the land-registration application to Lantmäteriet. The general template is not a substitute for verifying those requirements.
Gift without payment versus mixed gift and sale
This main deed is drafted for a pure gift without purchase price, assumed debt or other consideration. If the recipient takes over the donor's mortgage loan, pays compensation or issues a promissory note, the transaction may have tax and stamp-duty consequences and must be redrafted. For Swedish stamp duty, Lantmäteriet generally uses a threshold of 85% of the previous year's assessed tax value for the transferred share. The income-tax classification of a mixed real-property transfer follows a different assessment — commonly the transfer-year assessed value and gift intent (the huvudsaklighetsprincipen). The tests are not interchangeable. A lender's consent can also be required.
Inheritance and separate-property provisions
If the donor gifts property to a descendant, Swedish inheritance law may presume an advancement of inheritance (förskott på arv). The deed offers mutually exclusive alternatives to express the donor's intended treatment, subject to applicable inheritance rights. For a suitable third-party gift, the donor may prescribe that the property becomes the recipient's separate property (enskild egendom). Gifts between spouses must not use this clause mechanically; a separate marital-property arrangement may be required to achieve the intended outcome.
Who is this template suitable for?
- An adult owner wishing to gift an existing Swedish property or a clearly identified undivided fractional ownership share.
- Family gifts, such as a parent gifting a 1/2 share in a holiday home to an adult child, where all financing and ownership issues have been checked.
- English-speaking donors and recipients who need accessible wording while complying with Swedish property law.
- A straightforward transfer without compensation, complex conditions, subdivision or special acquisition permits.
When is a specialized agreement or legal review necessary?
- Gifting a physical part of land to be subdivided: specific cadastral rules and a six-month application deadline may apply.
- Mortgage assumptions or payment: lender consent, mixed-transfer tax treatment and potential stamp duty require individual review.
- Rights of residence, restrictions on onward transfer, reversion rights: must be assessed under the Swedish Land Code and registration requirements.
- Spouses, cohabitants or former spouses: consent and registration rules may be central.
- Minor recipients, companies, agricultural properties or overseas parties: representation, permits, identification and other restrictions may apply.
- Bostadsrätt: a housing-cooperative apartment is not an ordinary real-property title transfer and needs a different document.
How to complete the English deed
- Order an updated property register extract; verify legal title, the exact fastighetsbeteckning, mortgages and the donor's registered ownership share.
- Enter both parties' legal names and correct identity information; confirm the recipient can meet the registration requirements.
- State whether the gift is the entire property or an exact fractional ownership share; use a clear fraction such as 1/2.
- Confirm that the gift is wholly gratuitous. Stop and seek advice if any payment, loan assumption or counter-performance is involved.
- Decide on any inheritance-advance or separate-property options, and delete all unused alternatives.
- Assess spouse/cohabitant consent, possible Skatteverket registration between spouses and any other special requirements.
- Verify the acceptance of an English deed and any translation requirements with Lantmäteriet. Sign one chosen language version on paper, with two witnesses to the donor's signature.
- Apply for lagfart within three months, include the proper documentation, and separately deal with financing, insurance and tax issues.
Example: a gift of a half share
A parent owns a Swedish property identified by its official cadastral designation and wants to gift an undivided 1/2 share to an adult child. The parties describe the exact share, include a clear gift declaration, determine whether it should count as an advancement on inheritance, and assess whether consent from the donor's spouse is necessary. They sign the deed in ink and the donor's signature is witnessed by two people. The recipient then applies for lagfart. This example is informational, not a guarantee of legal suitability.
Frequently asked questions
Can I use an English deed of gift to transfer real property in Sweden?
The deed is drafted in English under Swedish law, but language and documentary acceptance must be confirmed with Lantmäteriet in the specific case. A Swedish translation may be required. An English-language form is not a waiver of the Land Code's form requirements.
Do I need two witnesses?
For Lantmäteriet's land-registration procedure, two witnesses must attest the donor's signature on the acquisition document. This is different from the general rules for gifts of ordinary movable items.
Is a digital signature sufficient?
Not for a real-property acquisition deed presented as the basis for lagfart. An electronically signed application may be allowed, but the deed itself requires an acceptable original signed form.
When must the recipient apply for lagfart?
Within three months after the acquisition, under the applicable rules. Check additional steps if the property is a gift between spouses or involves subdivision.
What if the recipient assumes an existing mortgage?
This no-consideration form should not be used unchanged. Lender approval and careful assessment of the stamp-duty and income-tax consequences are needed.
Does every gift of Swedish property avoid stamp duty?
No. For example, a gift with compensation, including assumed loans, may trigger stamp duty if it meets the relevant statutory test. A processing fee can also be charged on an ordinary gift registration.
Are the Swedish and English deeds meant to be signed together?
No. They are two language approaches to one intended gift. Check which version is suitable and accepted; do not execute two independent acquisition deeds for the same gift.
Related Mallbutiken product
Prefer Swedish as your main language? See Gåvobrev för fastighet – svensk Word/PDF-mall.
Official legal references
- Swedish Land Code, Jordabalk (1970:994), Chapter 4 and Chapter 20.
- Lantmäteriet – application for land registration after a gift.
- Lantmäteriet – registering ownership and identity requirements.
- Lantmäteriet – stamp duty and fees.
- Skatteverket – gifts between spouses.
Edition 2027. Legal framework checked 9 October 2026. General documentation support, not individualized legal, tax or property-transfer advice. No guarantee that a completed document is valid, suitable, accepted for registration or effective against third parties in all circumstances.