Svenska Dokumentmallar
Control Balance Sheet with Auditor – Excel + Swedish/English Guides
Control Balance Sheet with Auditor – Excel + Swedish/English Guides
- File format
- XLSX, DOCX, PDF
- Document language
- Swedish English
- Number of files
- 6
Digital download. No physical product is shipped.
Couldn't load pickup availability
About this template
Control balance sheet for Swedish limited company with an appointed auditor – a complete digital template package with Swedish and English Excel templates, automatic capital assessment, specific auditor documentation, and detailed user guides.
Legal references: October 4, 2026
Designed based on Chapter 25 of the Swedish Companies Act, annual report regulations, and the Swedish Accounting Standards Board's current guidance on control balance sheets.
What's included in the package
| Swedish Excel template | Complete workbook for control balance sheet with auditor workflow. |
| English Excel template | English language version for use under Swedish law. |
| Swedish user guide | Detailed step-by-step guide in Word and PDF. |
| English user guide | Detailed English guide in Word and PDF. |
| Digital delivery | All new files are delivered together in a ZIP package. |
Important: auditor's statement is not included
If the company has an appointed auditor, the control balance sheet must be audited by the company's auditor. The auditor's statement must be prepared after the actual audit and therefore cannot be replaced by a general template. Instead, the package contains a specific worksheet for compiling audit documentation, dates, attachments, and the status of the auditor's statement.
When must a control balance sheet be prepared?
The board must immediately prepare a control balance sheet when there is reason to assume that the company's equity, calculated according to the control balance sheet rules, is less than half of the registered share capital.
The obligation also applies if an attempt at execution shows that the company lacks assets to fully cover the debt for which execution was sought. If the company has an auditor, the control balance sheet must subsequently be audited by the auditor.
How the Excel template helps you
- separate columns for book values, KBR adjustments, and KBR values,
- automatic balance control,
- capital test against half of the registered share capital for the first assessment,
- capital test against the full registered share capital before the second general meeting on the issue of liquidation,
- separate specification of KBR adjustments and supporting valuation documentation,
- breakdown of untaxed reserves between equity and deferred tax,
- board signature page,
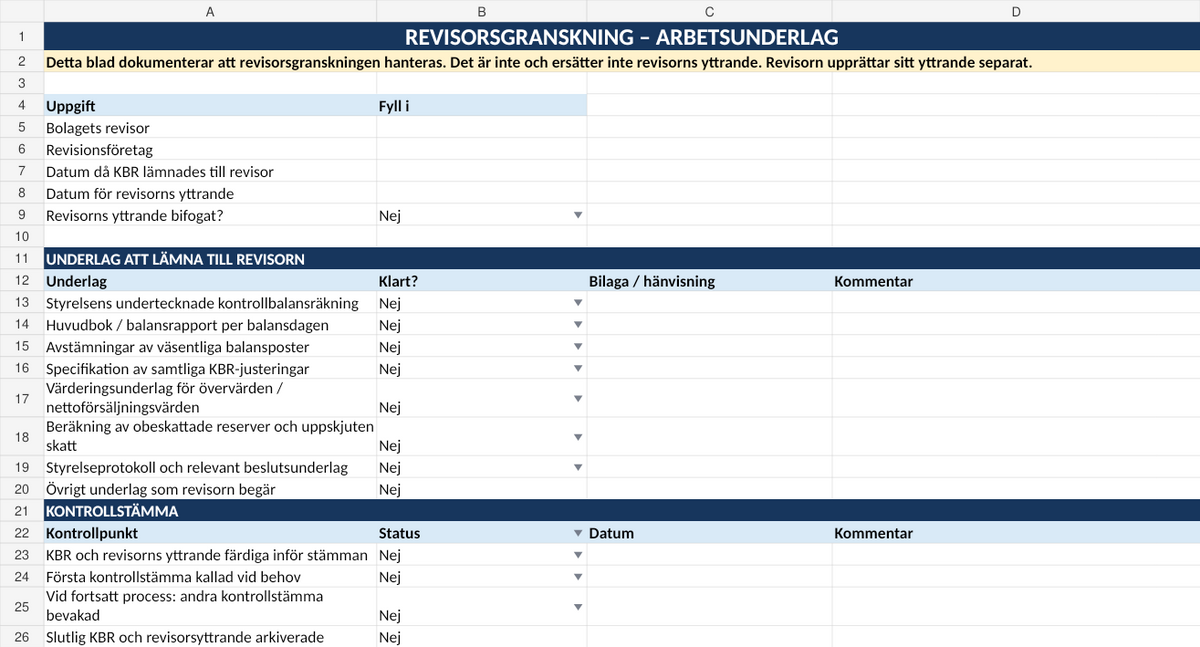
- a dedicated AUDITOR sheet with a checklist of documentation that may need to be provided to the auditor,
- checkpoints to ensure that the auditor's statement is available before the general meeting on the issue of liquidation.
The auditor workflow is built into the workbook
On the specific auditor sheet, the company can document who the auditor is, when the control balance sheet was submitted for audit, the date of the auditor's statement, and whether the statement is attached. It also includes a checklist for items such as the general ledger, balance reconciliations, valuation documentation, specification of KBR adjustments, and board minutes.
The sheet is only a work and documentation aid. The auditor decides for themselves which audit procedures are required and how the separate statement should be formulated.
KBR adjustments and valuation
The control balance sheet is based on the company's regular accounts, but Chapter 25, Section 14 of the Swedish Companies Act allows for specific adjustments. Under certain conditions, assets may be recognized at a higher value, provisions and liabilities at a lower value, assets can be recognized at net selling value, and untaxed reserves must be divided between equity and deferred tax liability.
Every adjustment must be justifiable and documented. In this version, this is particularly important as the documentation must be available for review by the company's auditor.
First general meeting on the issue of liquidation
If the audited control balance sheet shows that equity is less than half of the registered share capital, the board must call for a first general meeting on the issue of liquidation as soon as possible. Both the control balance sheet and the auditor's statement must be presented at the meeting.
Second general meeting on the issue of liquidation
If the capital is not fully restored and the first general meeting on the issue of liquidation does not decide on liquidation, a second general meeting on the issue of liquidation must normally be held within eight months. Before that meeting, the board must prepare a new control balance sheet and have it audited by the company's auditor. For the control balance sheet process to be concluded without liquidation, the control balance sheet needs to show that equity amounts to at least the registered share capital.
Swedish + English in the same package
The English Excel template and user guide are language versions of documents designed for Swedish law. They are not intended to be used as British, American, or other foreign corporate law documents.
Who is this package for?
- Swedish limited companies with an appointed auditor,
- boards that need to investigate suspected capital deficiency,
- companies that want to compile KBR and auditor documentation in a structured manner,
- accounting consultants who prepare documentation for the auditor's review.
File format and delivery
Format: XLSX, DOCX, and PDF.
Language: Swedish and English.
Delivery: digital download. No physical product is shipped.
Read more about the valuation of items in a control balance sheet →
Frequently asked questions
Is a completed auditor's statement included?
No. The auditor's statement must be prepared by the company's auditor after the actual audit.
Should the auditor sign the control balance sheet itself?
The control balance sheet must be signed by the board. The auditor provides their statement separately.
What happens if the KBR is changed after the auditor's review?
A significantly changed version should be resubmitted to the auditor for an assessment of whether a new or supplementary audit is needed before the document is used in the control balance sheet process.
Can the template be used for the second general meeting on the issue of liquidation?
Yes. The control step can be selected in the workbook, and the capital test is then adjusted to the requirement for full registered share capital.
The template package is a practical document and calculation aid and does not replace individual legal, accounting, or auditing advice. The board is responsible for the control balance sheet, and the auditor is responsible for their independent audit and statement.
Guides: calculation and review
- KBR calculation with examples and threshold values
- Documentation, valuation attachments, and documentation for review
- When must the board prepare a control balance sheet?
This variant is intended for companies with an appointed auditor. Here is the KBR template for companies without an appointed auditor. The auditor's involvement does not replace the board's own responsibility or the decision regarding any potential general meeting on the issue of liquidation according to Chapter 25 of the Swedish Companies Act.
Which control balance sheet template should you choose?
This documentation is intended for limited companies that have an appointed auditor. The company's auditor must review the control balance sheet and provide a statement; the template package itself does not replace the auditor's work. The board is responsible for taking action when there is reason to assume capital deficiency.
Does the limited company lack an appointed auditor? Compare control balance sheet without auditor – Excel template. Do you primarily need an English-language work document? See Control Balance Sheet – English Excel/PDF under Swedish law.
Follow the calculation guide for capital limits and permitted adjustments. Also read the Swedish Companies Registration Office's guidance on KBR and auditor review.
Control balance sheet with an appointed auditor: step-by-step guide
When the company has an appointed auditor, the auditor must review the control balance sheet. The board remains responsible for preparing and signing it and following the capital-deficiency procedure, including control meetings when required. Read the Swedish step-by-step guide. BFN.
The version with an auditor includes working documentation for the auditor's independent review; the template does not replace the audit or the auditor's statement.
K2 and K3 when preparing a control balance sheet
The accounting framework used is a separate question from whether the company has an appointed auditor. Read how K2 and K3 affect the calculation and permitted valuation adjustments. Do not combine rules from different frameworks arbitrarily; the board retains responsibility and an auditor must review the control balance sheet when appointed. K2 and K3 when preparing a control balance sheet (The linked guide is in Swedish).